What Actually Works As Proof Of Address
You need to submit proof of address when opening a bank account, signing up for utilities, registering a business, or dealing with government paperwork. The requirement is universal but the accepted documents vary by institution. Most places want something dated within the last 3 months. A utility bill from 6 months ago will get rejected even if the address on it is current. That is not up for debate with most compliance teams. I spent three years handling KYC documentation for a mid-size fintech company and watched hundreds of applications fail because of address proof issues. The most common reason was not that people lacked documents but that they submitted the wrong format. A printed screenshot of a mobile banking app does not count as a bank statement. A PDF you downloaded yourself sometimes passes, sometimes does not, depending on whether the verifier can confirm it came directly from the issuing institution. This is one of those gray areas that depends entirely on which reviewer is on shift.
Proof Of Address Examples And What You Need To Know Bills Bank Statements And Digital Alternatives
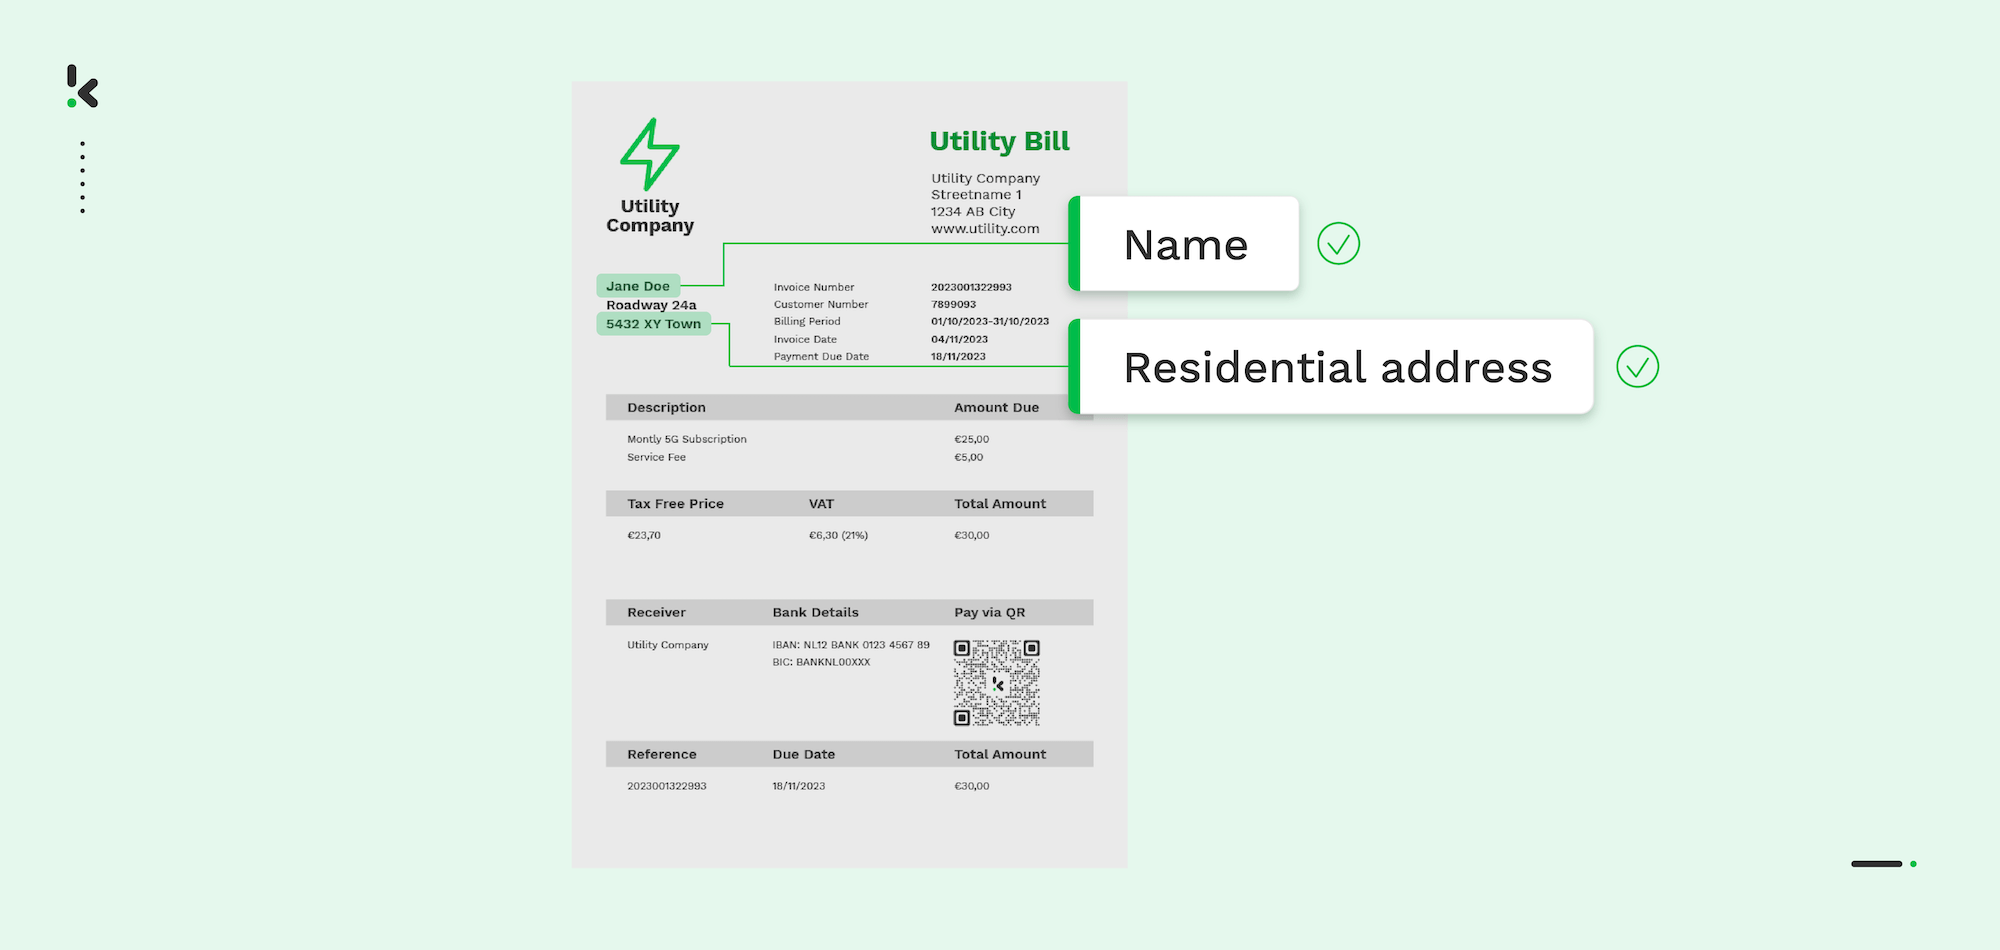
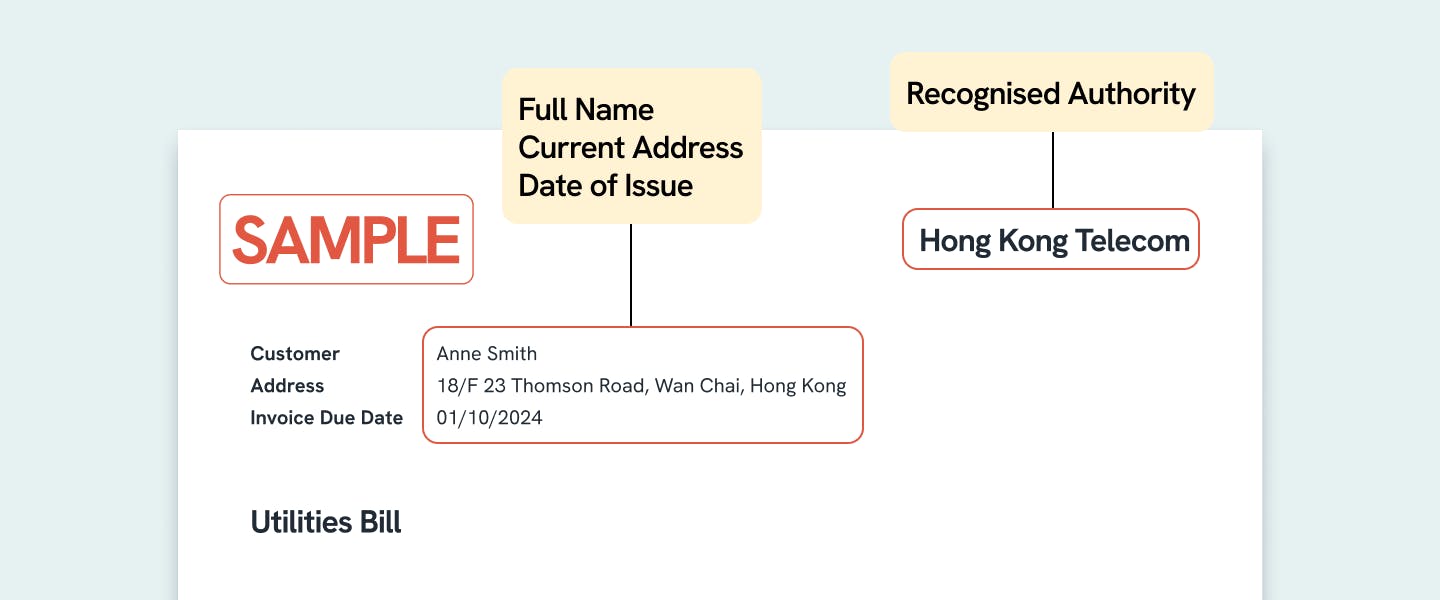
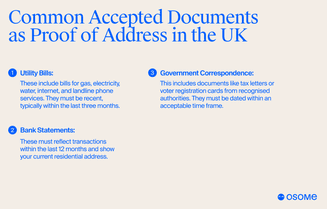
Standard accepted documents fall into a few categories. Bank and credit union statements are the most widely accepted. They need to show your full name and current residential address. Post-dated or pre-addressed envelopes do not count. The document itself must contain the address printed on it. Utility bills work too, but some companies reject them if they look like courtesy copies rather than official billing statements. A water bill that looks like a reminder notice from a mobile app may be turned away. Government-issued correspondence is another category. Tax documents, voter registration cards, letters from your local council or municipal office. The key word here is correspondence. It has to be an actual letter sent to your home, not something you filled out yourself and printed. A driver's license alone is usually not enough because that is an ID document, not an address verification. Some institutions accept a combination of a photo ID plus a separate address document, but that is their policy, not a rule. Digital alternatives have become more common since 2020. Many banks now accept digital bank statements delivered through their own secure portals. A statement with a verifiable document ID or QR code that a verifier can check against the issuing bank's system is generally accepted. However, a screenshot exported from your phone gallery is almost never sufficient. The verifier needs to authenticate the source. This is why some people who relied on mobile banking statements ran into trouble when applying to institutions that require third-party verified documents.
I had a client once who submitted a digital utility bill generated from his electricity provider's online portal. It had his name, address, account number, and a date stamp. The institution rejected it outright because the document could not be independently verified through the provider's system. The workaround was straightforward but annoying: he called the utility company and requested that a statement be mailed to his address. It arrived five business days later as a proper printed bill on company letterhead. That version was accepted immediately. The moral is that convenience does not always align with what institutions will accept. Another edge case that comes up frequently involves people who share an address. If you live with a partner or family member and their name is on the lease or the utility bill, your own name may not appear on any document at that address. Some institutions accept a notarized letter from the primary resident confirming your address, combined with a copy of their utility bill and a photo ID. Others will not accept this at all. There is no universal standard here. You have to check the specific requirements of whoever is asking for the document before you invest time gathering anything. Let me mention a nuance that most guides skip over. Some institutions accept a lease agreement as proof of address, but only if it is a formal lease registered with a government authority or stamped by a notary. An informal rental agreement you signed with your landlord is typically not accepted. This is because anyone can write a lease. A registered document carries more weight because it has passed through a verification layer. If you are renting and need to prove your address, check with the institution first about whether they accept unregistered lease agreements before you waste time getting one notarized.
Get the Full Details

Digital documents are improving but acceptance is uneven across institutions. A growing number of banks now support instant address verification through Open Banking APIs, where they pull your transaction data directly from your existing bank. This eliminates the need to upload any document at all. If you are applying at an institution that offers this, it is significantly faster and removes the whole problem of finding acceptable paperwork. But many smaller lenders and some government offices still do not support this method. You will still need traditional documents in those cases. One practical tip that saves time: keep a folder of your most recent statements from every relevant institution. Bank, credit card, utility, internet, and insurance. Update it every quarter. When you need a proof of address, you should be able to grab a document that is less than 90 days old within two minutes. The alternative is scrambling to request a late statement from multiple providers, which can take anywhere from 3 to 10 business days depending on each organization's response time. Sometimes the address on your document does not match exactly what you entered in the application. A unit number missing, an abbreviation instead of a full street name, a PO box used in place of a physical address. Minor discrepancies like this cause rejections more often than you would think. A verifier matching "St" against "Street" might flag it, or they might not. There is no consistent standard. The safest approach is to ensure the address on your document matches your application entry character for character. If you cannot change the application, contact the institution's support line before submitting and ask them to note the discrepancy on your file.
Another thing worth noting is that some documents carry more weight than others purely based on institutional bias. A bank statement is almost universally accepted. A utility bill is accepted by most but not all. A government letter is generally trusted but some private institutions do not recognize certain types of correspondence. Insurance documents are the weakest category and are rejected by a notable number of verifiers. If you have flexibility in which document you submit, choose a bank statement first, then a utility bill, then a government letter, and treat insurance documents as a last resort. The biggest bottleneck people face is timing. Most institutions require a document dated within 3 months, and some insist on 60 days or even 30 days. If your last bill was generated four months ago, you cannot simply request an old one and use it. You need to generate a new statement. For a bank, this is as simple as logging in and downloading the latest statement. For a utility provider, it may require calling them or waiting for your next billing cycle. Plan ahead so you are not caught waiting on a document while a deadline looms. There is also the question of what counts as a residential address. Some institutions will not accept a mailing address or a virtual office address as proof of residence. They want evidence that you actually live at the location. If you are using a registered agent service or a mail forwarding company, expect pushback. A handful of institutions accept commercial addresses for business registrations but residential verification for personal accounts is almost always required to be a physical dwelling location.
When everything else fails and you cannot produce an accepted document, some institutions offer alternative verification methods. A video call where you read aloud from an ID and a utility bill, a notarized affidavit of residence, or even a reference from someone who can vouch for your address. These are exceptions, not the norm, and they usually add significant processing time. Relying on them is fine if you have no other option, but it will slow your application down considerably compared to simply uploading a standard bank statement.