Why Everyone Is Talking About Problemnocash The Rise Of Noncash Transactions In The Digital Age
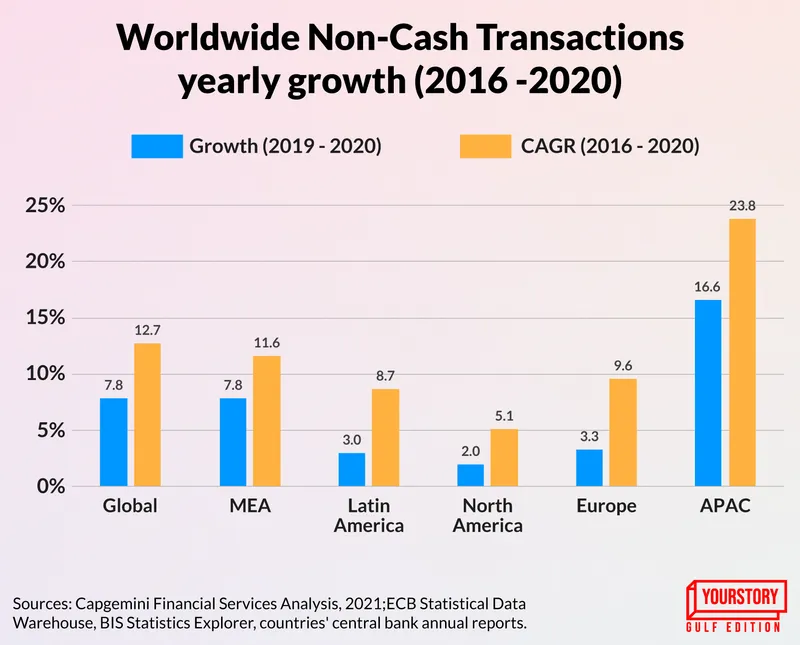
The shift away from physical currency isn't happening because of some grand conspiracy or sudden change in consumer preference. It is happening because the infrastructure around digital payments matured faster than anyone outside banking predicted, and businesses realized the margins on card processing are thin enough to barely matter when volume is high enough. I have watched this transition play out across multiple sectors over the last decade. The early adopters treated it as a novelty. The ones who stuck with it treated it as a logistics problem. That distinction matters more than anything else in this space. Noncash transactions now account for somewhere between 60 and 75 percent of all consumer purchases in developed economies, depending on how you define the categories and whether you count peer-to-peer apps as separate from traditional payment rails. The number sounds clean. The reality underneath is messy. Different regions use completely different infrastructures. Europe runs on SEPA, instant payment schemes, and local card networks that often predate even some of the newer US fintech players. Southeast Asia operates on QR-based systems that bypass traditional merchant acquiring entirely. Africa has mobile money ecosystems like M-Pesa that handle more transaction volume than many national banking systems. There is no single model here. There is just convergence toward less physical money changing hands.
Problemnocash The Rise Of Noncash Transactions In The Digital Age
The core concept behind this movement is straightforward but the mechanics are anything but simple. It involves replacing physical currency and checks with electronic payment methods including debit and credit cards, digital wallets, bank transfers, real-time payment systems, and increasingly blockchain-based settlement layers. What makes it non-obvious is that every one of those methods operates on different clearing timelines, different fee structures, and different regulatory frameworks. A same-day bank transfer through a real-time payments network like FedNow or UPI costs fractions of a cent. A cross-border card swipe can run three to four percent in interchange plus network fees plus cross-border markup. Both are noncash. They feel completely different to merchants and consumers. When I started implementing payment systems for small to mid-market merchants, the first thing I learned was that accepting noncash does not mean you have one integration. It means you have multiple. A typical mid-size retailer might need to support card-present, card-not-present, QR code scanning, ACH pulls, and wallet providers simultaneously. The overhead of managing chargeback windows across five different processor relationships is significant. Most small businesses underestimate this by a factor of three. One practical insight that took me months to learn the hard way: interchange fees are not fixed percentages. They vary based on card type, transaction method, merchant category code, and even the issuing bank's relationship with the card network. A co-branded airline card running through a card-not-present channel in a retail category will hit a different rate tier than a contactless debit transaction at a grocery store. If you are building a payment strategy around average processing costs and your weighted rate ends up 0.5 percent above benchmark, you are likely missing optimization opportunities in your merchant category code classification or your transaction routing logic. That 0.5 percent on two million in monthly volume is ten thousand dollars a year. That is the difference between a payment operations team being fully staffed or running on a single person doing everything by hand.
Another counter-intuitive point that most guides skip: fraud detection in noncash environments actually gets harder as adoption increases, not easier. Early adopters of digital payments tend to be lower-risk demographics. As the population saturates, fraudsters shift strategies. Account takeover attempts, synthetic identity creation, and friendly fraud through chargeback abuse all scale with transaction volume. The tools exist to mitigate these, but they introduce friction that pushes some legitimate customers toward abandonment. The sweet spot between conversion rate and fraud loss rate is not obvious and it shifts constantly as both sides adapt. Here is a specific scenario I dealt with that illustrates how brittle some of these systems can be. A client was processing through a major payment gateway and suddenly their transaction approval rates dropped from about 94 percent to 61 percent over a single weekend. No configuration changes were made. No API keys rotated. Investigation revealed that a major issuing bank had updated its fraud routing rules overnight, and the payment gateway's default risk engine was soft-declining thousands of perfectly legitimate transactions because the bank's own detection models had tightened. The workaround was not technical in any conventional sense. It involved filing a formal dispute through the gateway's merchant support channel with transaction-level evidence packages, getting the client's account flagged for manual review, and then implementing a fallback processor that routed declining transactions through a different risk scoring path while the primary issue was being resolved. Total downtime: approximately 36 hours. Total revenue impact: roughly fourteen thousand dollars in lost sales plus an estimated additional eight thousand in chargeback disputes that piled up during the confusion window. The lesson was that redundancy is not optional. Having a secondary payment route that can handle traffic during a primary processor degradation is the difference between a minor inconvenience and a genuine business crisis. For individuals looking to participate in the noncash ecosystem, the barrier to entry is essentially zero. Open a bank account. Get a debit card. Download a few payment apps. That is it. For businesses, the barrier is operational complexity and cost structure. Setting up merchant acquiring takes anywhere from two days to six weeks depending on your industry risk profile, existing credit history, and which processor you approach. High-risk industries face extended underwriting and rolling reserves that can hold back 10 to 20 percent of incoming revenue for six months or more. This is standard practice and it is not negotiable with most mainstream processors.
Get the Full Details
The technology stack has simplified considerably. APIs from providers like Stripe, Square, Adyen, and PayPal cover most use cases out of the box. Webhooks handle async event notification so your system does not need to poll for transaction status. Settlement feeds provide daily reconciliation data in structured formats. The hard part is never the initial integration. It is the ongoing maintenance, the edge cases, the regulatory reporting, and the fraud operations that nobody budgets for until something breaks. Looking ahead, the trajectory is clear but the timeline is not uniform. Central bank digital currencies are still in pilot or early rollout phases in only a handful of countries. The European digital euro is years from full deployment. China's digital yuan has the most advanced implementation but operates in a closed ecosystem. Private stablecoins face persistent regulatory uncertainty in most Western jurisdictions. What is happening instead is incremental improvement to existing rails. Real-time payment networks are expanding. Open banking frameworks in Europe and the UK are beginning to enable direct bank-to-bank payment initiation that bypasses card networks entirely. This is where the most meaningful cost reduction will come from, not from speculative crypto innovations. There are genuine downsides to this transition that get glossed over. Payment fatigue is real. Consumers encountering checkout flows with eight different payment options and five different authentication steps will abandon carts at rates that increase logarithmically with each additional friction point. Small merchants absorbing interchange fees on low-average-ticket transactions see their net margins compressed to unsustainable levels. The digital divide excludes populations without bank accounts or reliable internet access, and while financial inclusion programs exist, they move slowly. Data privacy concerns around payment information tracking are legitimate and increasingly regulated under frameworks like GDPR and upcoming state-level privacy laws in the United States.
If you are evaluating whether to expand your noncash acceptance or build a new payment system from scratch, start by mapping your actual transaction flows rather than assuming what your customers want. Audit your current processing costs by payment method and card type. Identify your top three fraud vectors and assess whether your current controls address them. Build in processor redundancy before you need it. And do not treat payment infrastructure as something you set up once and never revisit. The landscape changes every quarter. The fee schedules change twice a year. The fraud techniques evolve continuously. Staying current is not optional if you want your payment operations to remain competitive and secure.