What Actually Happens When Money Changes Hands
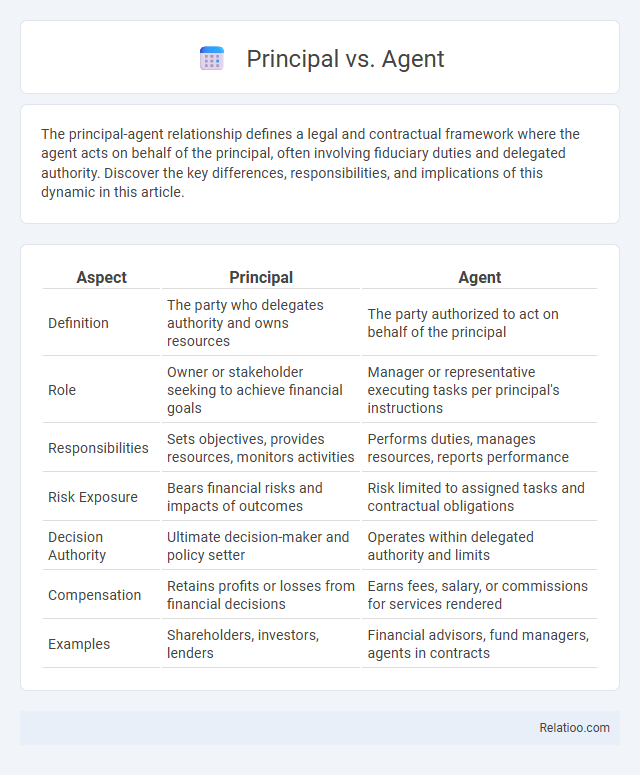
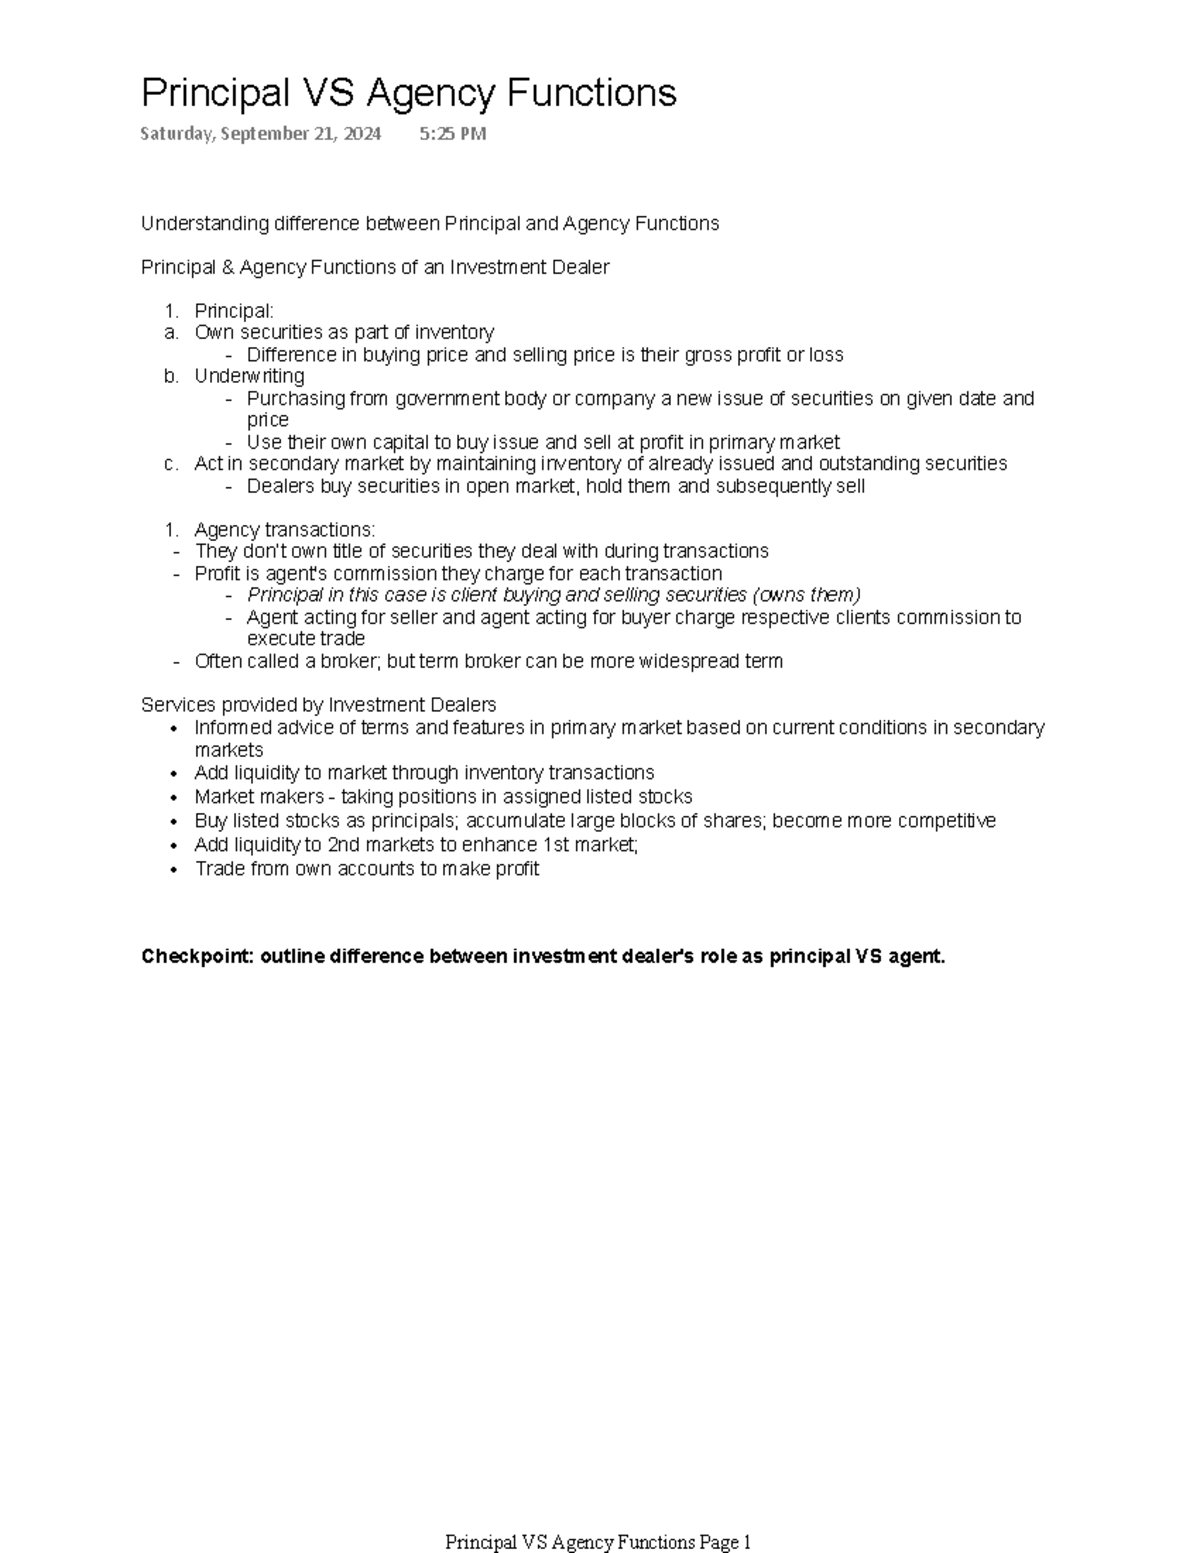
Most people in finance understand the basic split between principals and agents, but they usually get tripped up on the details when something goes wrong. Here is how the distinction actually plays out in practice, and where the real headaches show up. A principal is the party who owns the asset or bears the risk. An agent is the party hired to act on behalf of that principal. That sounds simple, but the moment you start dealing with layered fund structures, discretionary mandates, or custody chains, the lines blur faster than most compliance teams want to admit. I was working on a cross-border bond arbitrage execution a few years back when the custody layer created a genuine mess. The client's investment manager gave trading instructions to a prime broker, who then routed orders through a sub-custodian in a different time zone. When settlement failed because of a local market holiday the sub-custodian hadn't flagged in time, the principal-versus-agent question became the entire dispute. The investment manager argued the sub-custodian was their agent and should have known. The prime broker pushed back, saying they were merely executing and the client's own due diligence should have covered it. The workaround came down to tracing the exact mandate language in the custody agreement, which specified notification timelines in writing. We pulled those clauses, confirmed the sub-custodian had breached their explicit communication duties, and the client recovered the timing loss. Without that paper trail, it would have been a he-said-she-said that went nowhere.
The core mechanic is this: principals put up capital. Agents expend effort. In a standard discretionary portfolio, the fund manager is the agent and the LP is the principal. In an embedded banking setup, the relationship gets messier. Your bank might be both your custodian and your lending agent, which creates dual loyalties you need to map explicitly. Here is something most introductory guides won't tell you: the agency problem isn't symmetric. Principals lose money when agents underperform or take hidden risks. Agents, meanwhile, face different downside exposure. They lose reputation and future fee income, which often matters more to them than any single transaction. This asymmetry shows up in fee structures. A flat management fee decouples agent compensation from performance in a way that incentivizes asset gathering over alpha generation. A pure performance fee inverts that dynamic and can push agents toward reckless concentration. The real-world sweet spot is usually a low base fee plus a high-water-marked carry structure, but even that doesn't fully align incentives if the agent has a guaranteed salary underneath. Another thing beginners consistently miss is the difference between legal agency and economic agency. You can have someone who looks like an agent on paper but functions as a principal in practice. Consider a family office that nominally delegates to external managers but retains veto rights over every position change. They're technically an agent arrangement, but economically they're acting as principal. Regulators sometimes treat these hybrid setups differently depending on jurisdiction, so the label matters for reporting even if the P&L looks the same.
Practical classification rules: Look at who signs the trade confirmation. Look at who bears the market risk after execution. Look at who has the right to override instructions. If all three point to the same party, you have a clean principal-agent relationship. If they're scattered across multiple entities, you have a chain, and each link in that chain is its own agency relationship with its own risk profile. Disclosure requirements also vary significantly by context. Registered investment advisers in the US file Form ADV Part 2A, which requires them to describe their agency relationships and any conflicts. Private equity general partners operate under a different framework where the limited partner agreement itself becomes the primary governance document, not a regulatory filing. The agent's duty of loyalty in PE is contractual and heavily negotiated, not imposed by regulation. That means the terms you see in the LPA are the real terms. Reading the conflict of interest section of an LPA will tell you more about how the principal-agent relationship actually works than any textbook summary.
Get the Full Details
There are scenarios where the principal-agent framework simply breaks down. Co-investment deals are one. When a GP offers limited partners the option to invest directly alongside the fund, the GP is simultaneously acting as the fund's agent and as a principal in the direct investment. The economics shift entirely. Fee structures change. Information flow changes. Managing both roles without creating a breach requires firewalls that most smaller funds don't actually maintain properly. Emerging market execution presents another failure mode. Local market rules sometimes require agents to hold positions in their own names for regulatory reasons, even though the economic benefit flows to the principal. This is common in certain Asian and Latin American markets. The agent appears as the beneficial owner on paper, which complicates tax reporting and creates custody risk. The workaround is usually a segregated sub-account structure with clear beneficial ownership documentation, but not all local custodians are set up to handle it cleanly. In those cases, principals end up exposed to the agent's balance sheet risk even though they never intended to take it on. If you're trying to navigate this yourself, start by mapping every entity that touches a decision or a dollar. Write it down. Draw arrows showing who instructs whom and who bears the resulting risk. Then check whether the documented relationships match what actually happens on a trading day. The gap between those two maps is where your real risk lives.
The framework is useful but incomplete. It assumes clear lines of authority and measurable performance. Neither assumption holds in structured credit, special situations, or any deal where the agent has material proprietary information the principal doesn't. In those environments, the agency relationship exists alongside information asymmetry that no fee structure can fully correct. The best principals accept that and negotiate for transparency mechanisms instead of pretending alignment is achievable through contracts alone.