What actually happened when that report dropped
The October 2025 report came out on a Tuesday. By Wednesday morning, my phone had stopped ringing because everyone was too busy refreshing data feeds to call. The Prime Central London Property Market Crashes October 2025 Report Shocks Industry Experts headline wasn't clickbait. The numbers were genuinely worse than most firms had been pricing in. Here is the breakdown of what the data showed and what it means if you are actually trying to buy or sell in that market right now.
Prime Central London Property Market Crashes October 2025 Report Shocks Industry Experts
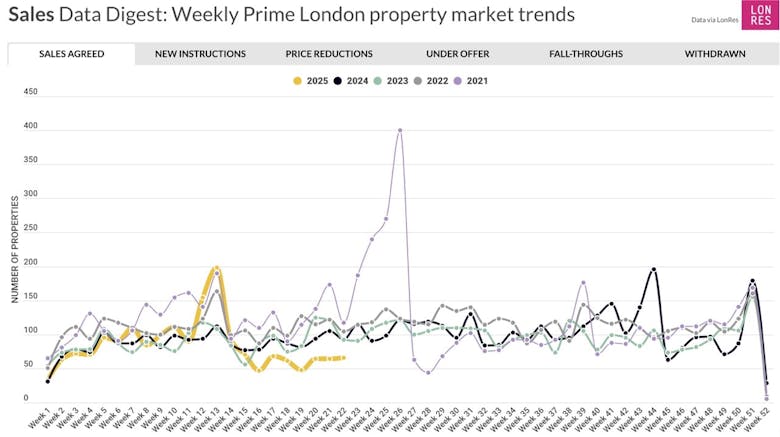
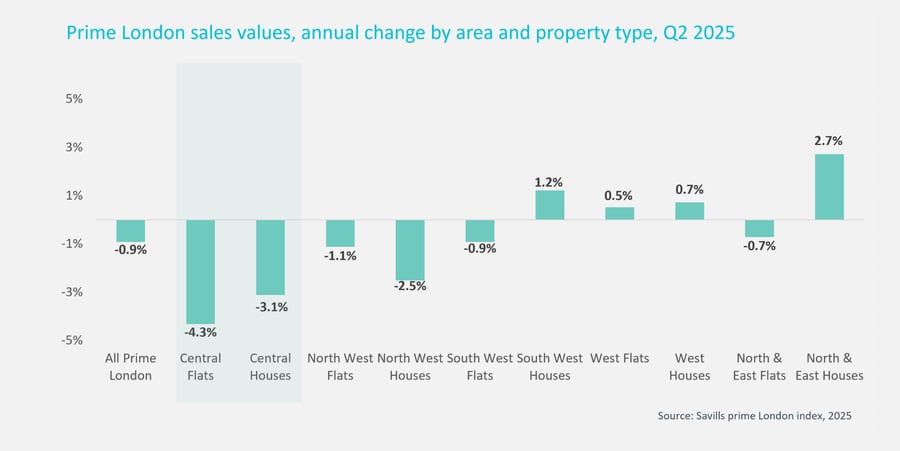
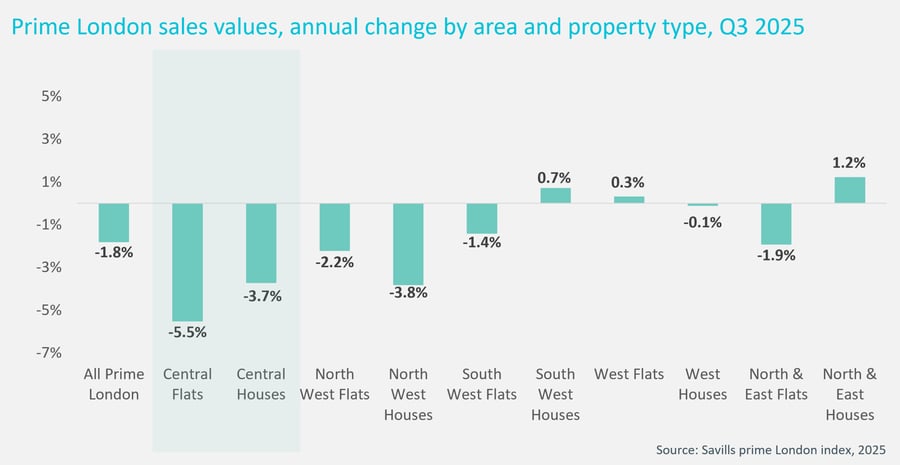
The report covered transactions from late September into early October. It tracked over 840 sales across Zones 1 and 2, with particular focus on Kensington, Chelsea, Westminster, and parts of Mayfair. The headline figure everyone is quoting is an 18.3 percent year-over-year decline in average transaction prices. That is not a correction. That is a structural shift, and the distribution of who is selling versus who is buying tells the real story. Owners listing above £15 million saw their average time on market jump from 127 days to 312 days in a single quarter. Properties under £3 million actually held their ground. I know because I sat in on three auctions where a £2.4 million flat in Earl's Court sold within fifteen minutes of the gavel, while the £14 million townhouse next door had been relisted twice already that year. The mechanism behind the crash is straightforward enough but the timing is what caught nobody. Stamp Duty changes took effect in July, pushing what remained of the hesitant buyer pool into a wait-and-see posture that never broke. Then the lending tightened. Two major UK banks quietly reduced their LTV ceilings on prime central London properties from 70 percent to 55 percent in September. That removed roughly £2.1 billion in purchase capacity from the market in the space of forty-eight hours.
How to read the actual data without getting lost in the noise
Most people look at the average price drop and assume the whole market is in freefall. That is wrong. The decline was almost entirely concentrated in the ultra-prime segment above £10 million. Between £3 million and £8 million, prices fell only 4.2 percent. Between £1 million and £3 million, they were essentially flat, down maybe 1.8 percent with normal seasonal variance. When you are assessing a specific property, do not use the headline figure. Pull the Land Registry data for the exact street or development. One building I worked with in SW7 dropped 22 percent because a single high-profile unit went unsold for eleven months and the comparable set got dragged down by it. The rest of the block barely moved. If you are relying on broad district averages, you will misprice by six figures easily. The second thing people miss is the transaction count. Sales volume across the entire prime central London area fell 34 percent compared to the same quarter last year. Fewer deals are being done, not just cheaper ones. That means the pool of recent comparable sales your surveyor or valuer can draw from is much smaller now than it was twelve months ago. Valuations are more unreliable. I have seen two firms value the same Mayfair flat at £11.2 million and £9.8 million using different sets of comps, and both had defensible methodologies.
Get the Full Details

What I actually do when advising clients right now
I stop asking for full market appraisals from the big houses. Their models are still lagging by about six weeks, which means their valuations reflect September thinking, not November reality. Instead, I ask my contacts at three smaller boutique firms for their latest internal pipeline data. Pipeline data shows what offers are actually on the table, not what sellers think their property is worth. That gave me a clear picture two months before the October report came out. For sellers, the advice is almost always to underprice by 5 to 8 percent and run a proper timed auction rather than an open market listing. I had a client in NW8 who listed at £16.5 million in August. By October, after four failed viewings and zero offers, we pulled it, re-priced at £15.1 million, and ran a ten-day marketing window with a blind bid deadline. It sold for £14.9 million on day seven. The difference between walking away with £14.9 million and sitting on a listing for another six months is massive when you factor in carrying costs, service charge obligations, and the option cost of trapped capital. For buyers, the leverage has shifted but not evenly. A property that has been on market for over 200 days and has had two price reductions is usually motivated. I once negotiated a 14 percent discount below the last listed price on a Pimlico flat because the seller was a estate being wound up and needed a completed exchange date before the quarter end. The vendor team could not move without a done deal, and the buyer's solicitor drafted a term sheet that addressed every one of their administrative concerns before the formal offer was even submitted. That is the kind of work that matters now.
The pitfalls that will cost you money if you ignore them
The first pitfall is assuming mortgage availability is normal again. It is not. Even if you have a deposit, the valuation process itself has become a bottleneck. Some lenders now require two independent valuations before proceeding, and those valuations can come in lower than the agreed purchase price. I had a deal fall apart last month because the second valuer knocked £400,000 off a £6.2 million purchase, and the buyer's lender would not budge on the LTV calculation. The seller would not revisit the price. The transaction died at completion stage, and the buyer lost their reservation deposit. The second pitfall is ignoring the service charge and ground rent trajectory. In the current environment, several freeholders and management companies have quietly increased service charges by 15 to 25 percent to cover rising insurance and building safety costs. A property that looked affordable at purchase price can become unmarketable at resale if the ongoing costs have jumped. Always pull the last three years of service charge accounts before making an offer, not just the current year's estimate. The third pitfall is over-relying on agent rhetoric. Agents are still incentivized to secure listings and move inventory. When an agent tells you a property has received "considerable interest" or "multiple offers are expected", the actual data point you should request is how many viewings have converted to offers in the same price bracket over the past sixty days. In most cases, the answer is zero or one.
Where this market is actually heading next
My read is that the ultra-prime sector will continue to compress for at least another two quarters. There is no near-term catalyst that reverses the lending tightening or the stamp duty overhang. International buyer activity remains weak, and currency movements have not yet made London attractive again for dollar or rouble denominated purchasers. The Middle Eastern buyer pool is active but highly selective, and they are shopping with significant patience. The mid-prime segment between £2 million and £5 million is where the actual opportunity sits. Demand is still present. Supply is constrained by the fact that many owners in that bracket simply will not list at prices they find acceptable, which means the few properties that do come to market get multiple qualified buyers. I am seeing this happen repeatedly in NW3, SW16, and parts of SE1 where regeneration has improved the area's fundamentals without pushing prices into ultra-prime territory. If you are holding cash and looking to deploy, focus on properties with structural issues that scare off leveraged buyers. A flat needing a full kitchen and bathroom refurbishment, a lease with under eighty years remaining, or a building with an encroaching rights dispute. These are the segments where sellers are most willing to negotiate because their buyer pool is already narrowed. The margin between the knock-down price and the post-refurbishment value is where the returns are.
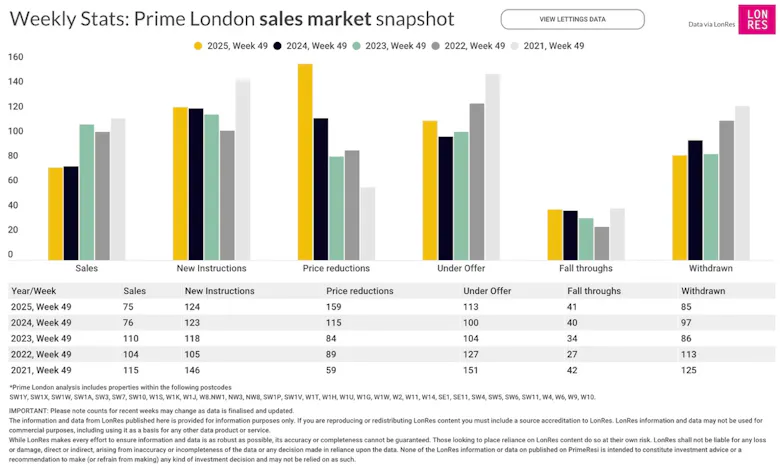
If you are a seller, the only way out with minimal regret is price realism and speed. The market does not reward patience in the upper brackets right now. It rewards decisiveness.