How Postal Money Orders Actually Work
Most people today assume digital payments are the only secure option. They are wrong. A postal money order is a prepaid payment instrument issued by a postal service, funded with cash or a debit transaction at the point of purchase. The recipient receives a guaranteed form of payment that cannot bounce. It exists outside the banking clearing system, which is both its greatest strength and its biggest drawback. I learned this the hard way in 2019 when I was handling a rental deposit for a property in rural Kentucky. The landlord had no bank account at a local branch. His credit union was forty miles away and he refused to accept a personal check, citing prior fraud. Cash was not an option because of the amount involved. A postal money order was the only thing that worked. I went to the post office, paid in cash with a valid photo ID, and the teller printed the order on the spot with a unique serial number. The landlord received it the next day by mail. It cleared without any issues. That was the last time I needed to do something like that.
Postal Money Order The Forgotten Secure Payment Method You Still Need
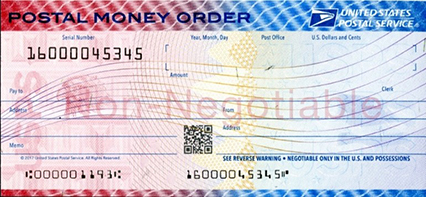
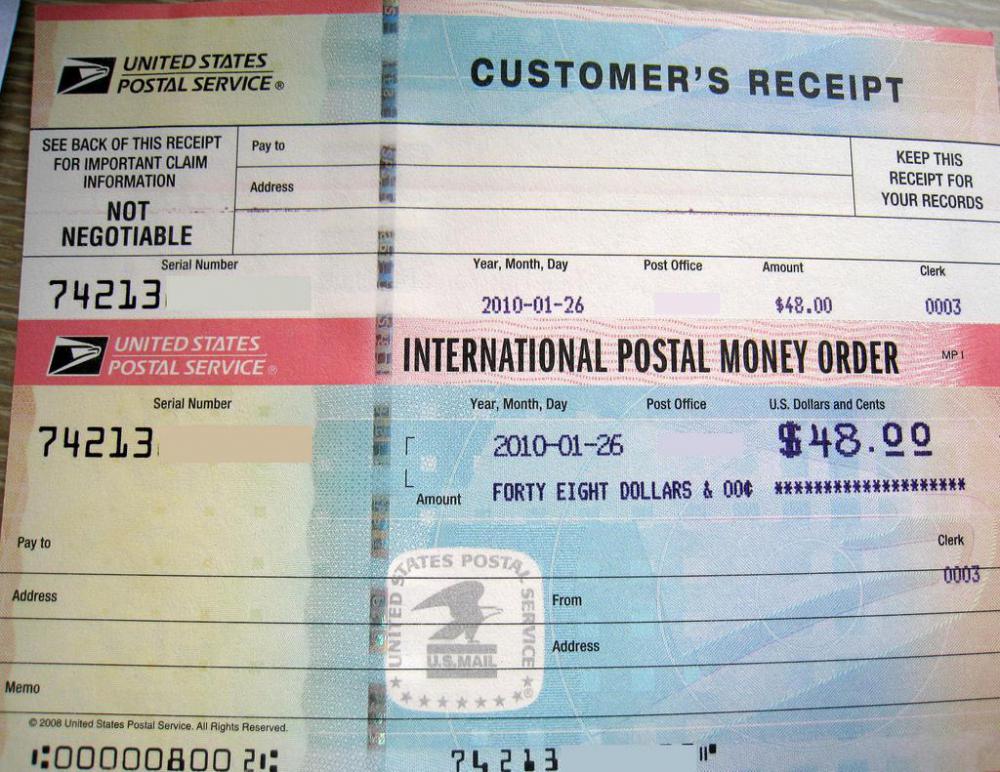
The mechanics are straightforward but there are details most guides skip. You go to a post office or an authorized retail location that sells them. You state the exact amount you want the money order to be for. Then you pay that amount plus a fee. In the United States, USPS money orders are capped at $1,000 per instrument. If you need to send more, you buy multiple money orders. Some private retailers like Western Union and MoneyGram sell their own versions with different limits and fee structures. The fee for a USPS money order is currently $1.95 for amounts up to $500 and $3.45 for amounts between $500.01 and $1,000. Private retailers may charge more. You always keep the receipt stub. That stub is your proof of purchase and contains the serial number. If the money order gets lost or stolen, the stub is what lets you request a cancellation and reissuance. Without it, you are basically out of luck and will likely never see that money again. One thing nobody warns you about: some recipients will refuse a money order older than a year. USPS money orders do not expire and do not carry an expiration date printed on them, but the policy is that any money order over one year old may require additional verification before it can be cashed. I encountered this when trying to cash a money order from a small invoice I had not processed quickly enough. The receiving bank asked me to call the issuer. I called USPS, they verified the serial number against their records, and within twenty minutes they confirmed the funds were good. The bank then processed it. The whole delay was about an hour and a half. Worth knowing so you can anticipate it instead of panicking.
Another nuance is the endorsement. You sign the back of the money order just like a check. But you must also write "for deposit only" followed by your account number in the restriction line if you are depositing it through a bank app or mobile check capture. This prevents anyone who intercepts the mail from cashing it at a check-cashing store. It is a simple step that adds a meaningful layer of security. The downsides are real and not worth glossing over. Postal money orders are slow. Same-day availability is impossible unless you hand-deliver it. Processing through the postal system or standard mail typically takes two to five business days for domestic delivery. International money orders take longer and involve higher fees. You also lose liquidity the moment you buy one. That money is gone from your wallet until the recipient deposits it. There is no interest earned in the meantime. And if you send it via regular mail without insurance, you have no recourse if it is lost in transit. For large transactions, the $1,000 cap per order becomes annoying fast. Sending $3,500 means buying four separate money orders. That is four purchase receipts, four tracking numbers if you insure them, and four potential points of failure. A cashier's check from your own bank solves that problem more efficiently for most domestic uses. Wire transfers solve it faster. But neither of those options works when the recipient lacks a traditional bank account or when the payer does not want to share account information.
Get the Full Details
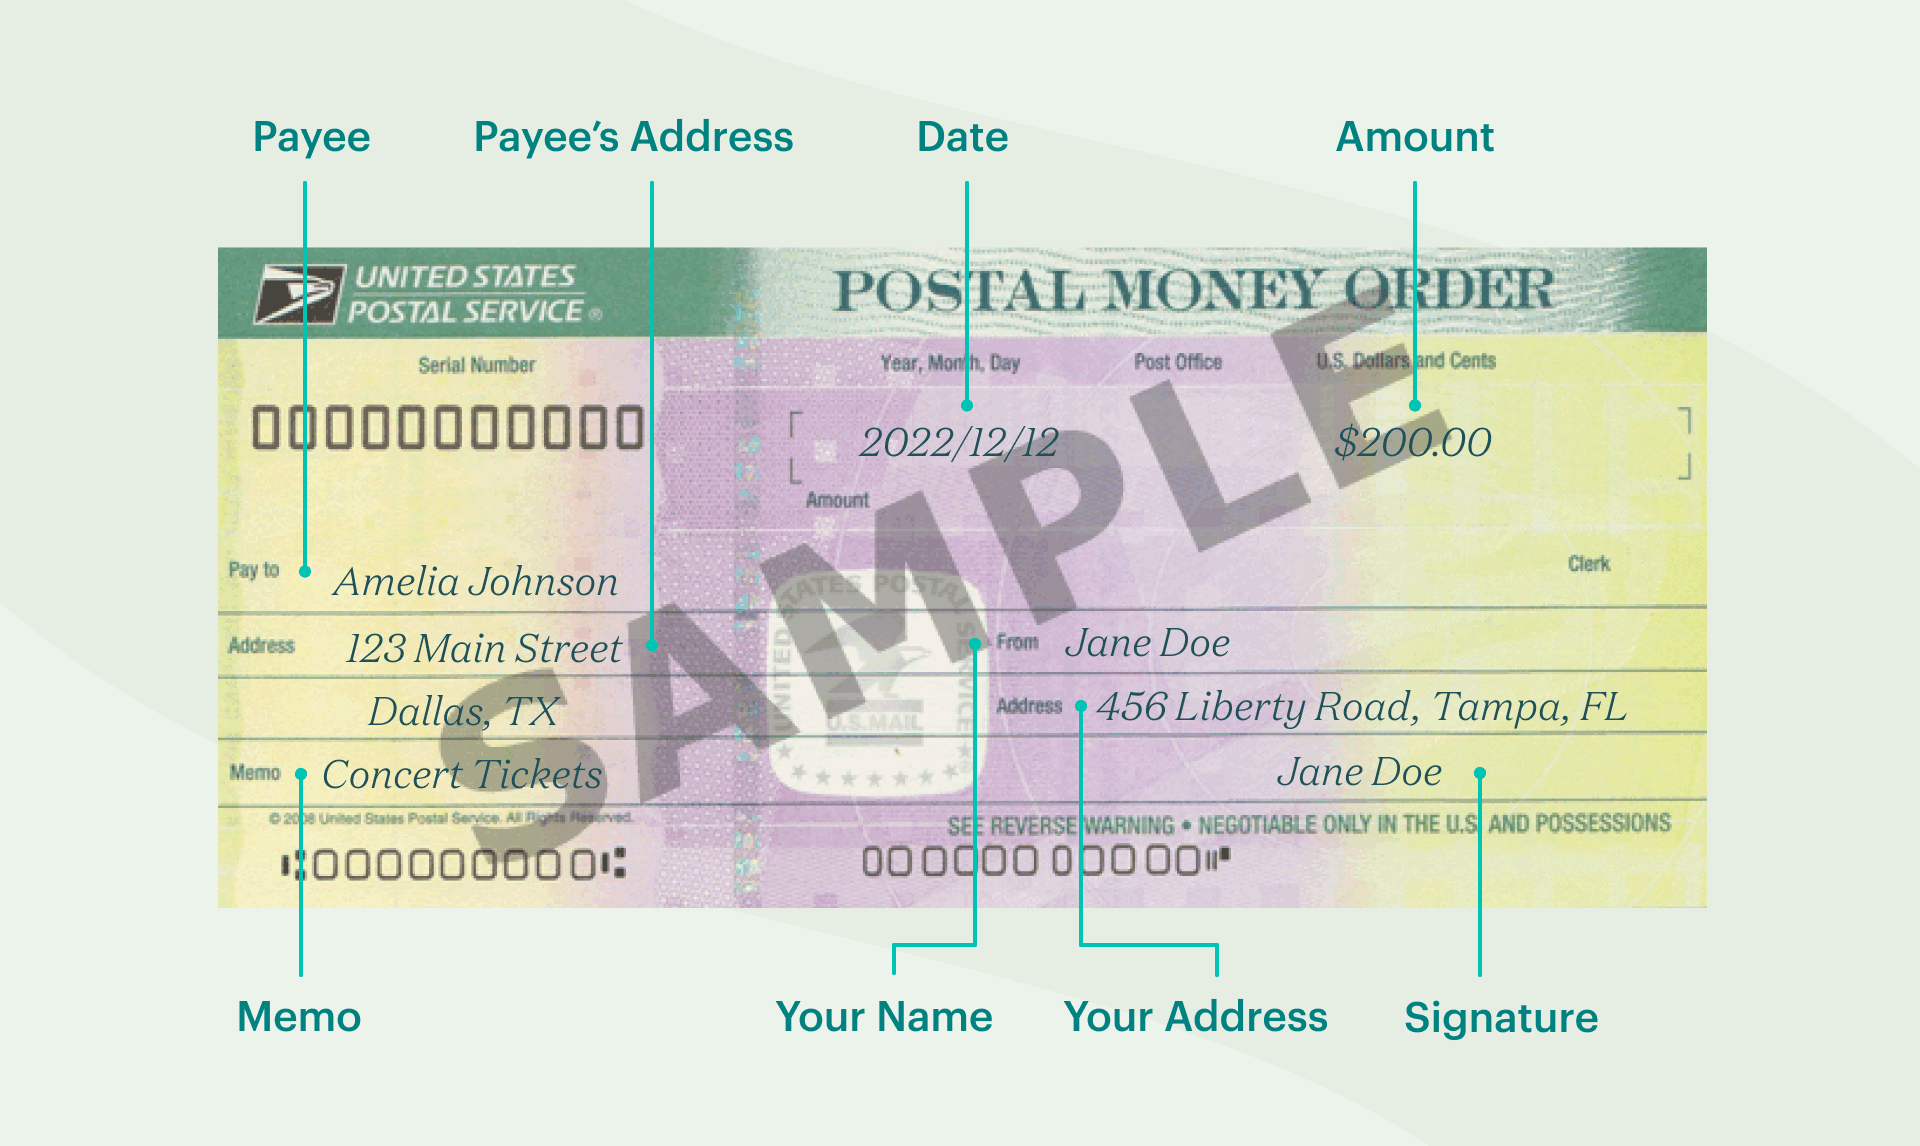
Here is the practical guide for using one correctly: Fill in the payee name on the front immediately. Do not leave it blank. A blank payee field makes the money order payable to bearer, which means whoever possesses it can cash it. Write it clearly in permanent ink. Sign the back only when you are ready to deposit or hand it to the recipient. Keep the receipt stub in a separate place from the money order itself. If possible, record the serial number and purchase date in a secure note on your phone. Take a photograph of the front and back of the money order before mailing it. This creates a visual record of exactly what you sent. When mailing it, use tracked and insured mail. USPS MoneyOrder.com allows you to purchase and print money orders online for pickup at your local post office, which eliminates the line and reduces the chance of someone seeing the amount at the counter. The online purchase price is the same, but the convenience is real. After purchasing online, you pick it up within the hour on a typical weekday.
If you are the recipient, verify the money order before accepting it. Check the serial number against the stub. Inspect the security features printed on the paper. USPS money orders have a watermark that is visible when held up to light. They also feature microprinting that should be legible under normal reading conditions, not blurred or smudged. Counterfeit money orders exist, and while they are not extremely common, they do show up in rental scams and certain types of freight payments. A quick call to USPS customer service with the serial number will confirm authenticity in most cases. The broader context matters here too. Postal money orders exist precisely because a significant portion of the population remains unbanked or underbanked. In the United States, roughly five million households do not have a traditional bank account. Globally, the number is in the billions. Money orders provide a bridge between the cash economy and the formal financial system. They are not elegant. They are not fast. They are reliable, and reliability is what makes them still useful despite how outdated they appear on the surface. If you need to send money to someone who cannot deposit a check, whose identity you want to verify without sharing banking credentials, or who is in a situation where digital payment platforms are unavailable or unreliable, a postal money order is the right tool. It is not the only tool. It is not the fastest tool. But it is one of the few tools that works across the full range of financial inclusion gaps, and that specificity is why it has not disappeared entirely.