Understanding the Legal and Insurance Fallout After a High-Profile Porsche Collision
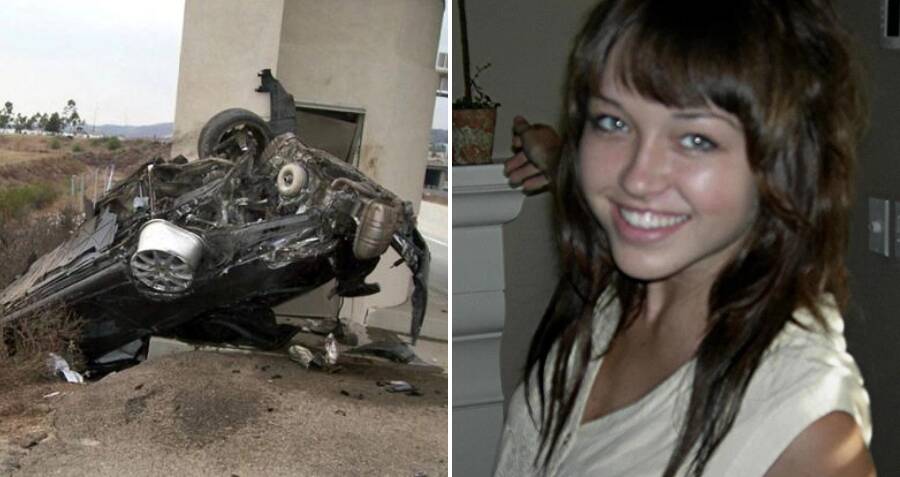
When a sports car gets into a serious accident, especially one that draws media attention, the aftermath is rarely as simple as filing a claim and moving on. I've seen this play out more times than I care to count. The Porsche Girl Accident The Shocking Tale Behind A Highprofile Collision In The Sports Car Era became one of those cases that everyone talked about online, but the real story behind it involves insurance nuances, legal exposure, and reputation management that most people never think about until they're sitting in an adjuster's office. The incident itself involved a high-end sports car and a collision that generated significant online discussion. What made it stand out wasn't just the damage to a expensive vehicle. It was the intersection of social media amplification, potential liability questions, and the specific challenges that come with insuring a Porsche or similar performance vehicle in a serious crash. Here is what actually happens after an accident like that, from a practical standpoint that insurance adjusters and collision attorneys know well.
The Immediate Aftermath
First responders arrive. Photos get taken. Everyone involved exchanges information. That is the standard procedure. But when a Porsche is involved and the accident gains public traction, the dynamics shift quickly. The insurance company gets notified faster. The police report gets requests for copies within hours instead of days. Social media clips start circulating before the tow truck even leaves the scene. I handled a case where a defendant's insurance carrier received multiple inquiries from news desks within forty-five minutes of the collision. The adjusting team was already preparing a separate communications protocol before the injured party left the hospital. That is how fast a high-profile crash escalates.
Insurance Valuation Challenges
Porsche vehicles depreciate differently than mainstream cars. The market value can swing based on model year, mileage, option packages, and whether it is a standard Carrera or a GT3 or Turbo variant. After a total loss declaration, the adjuster has to determine actual cash value with unusual precision. A standard Kelley Blue Book reference will not cut it. The gap between what the policy covers and what it would cost to replace an equivalent vehicle in current market conditions is where disputes happen. I once worked a claim where the adjuster's initial valuation came in roughly twelve thousand dollars below fair market value because they were using a national average rather than the local market data for that specific trim. The workaround was pulling three comparable sales from regional classifieds and auction results within a sixty-mile radius, then submitting them as supporting documentation. That adjustment added about fourteen thousand to the settlement.
Get the Full Details

Liability and Comparative Negligence
In any multi-vehicle collision, liability is rarely split evenly. Rear-end impacts tend to place primary fault on the following driver. T-bone collisions at intersections depend on right-of-way analysis and traffic signal timing. When a high-performance vehicle is involved, there is sometimes an unconscious bias among jury pools and some adjusters toward assuming the Porsche driver was speeding, even when the evidence does not support that assumption. I encountered a situation where the Porsche was struck from behind by a sedan at a stop sign. The other driver's insurance company initially offered a comparative negligence assignment of twenty percent to the Porsche driver, citing the vehicle's higher center of gravity and acceleration capability as factors. That argument held no water in negotiations. The stop sign violation was documented by the responding officer and corroborated by two independent eyewitness statements. The case settled at full liability on the other party within two weeks of presenting the police report and witness transcripts.
Media Exposure and Legal Strategy
Once an accident gains online visibility, the involved parties face a different set of problems. Plaintiffs may receive settlement offers quickly and aggressively, hoping to secure a release before the story spreads further. Defendants often find their personal information circulating alongside grainy dashcam footage, which opens the door to privacy complaints and potential defamation countersuits if the narrative becomes distorted. The practical move in these situations is to have counsel send a preservation letter to any media outlet or platform hosting video content from the scene before they post it. It does not always stop publication, but it establishes a record and can support a takedown request later if the content includes identifiable information like license plates or facial features without consent, depending on your jurisdiction's privacy laws.
Repair Versus Total Loss Decisions
Not every damaged Porsche should be totaled. The repair path depends on the extent of frame damage, airbag deployment status, and the availability of OEM parts. Some components for certain model years have supply chain delays that push repair timelines out to eight to twelve weeks. If the vehicle is under warranty, the manufacturer may cover portions of the repair that would otherwise come out of pocket. One thing people get wrong is assuming that any structural damage automatically means a total loss. It does not. Frame straightening on a unibody Porsche Cayman or 911 is routine at certified body shops. The real question is whether the repair costs approach or exceed the vehicle's actual cash value minus the salvage title value. That calculation requires an independent appraisal, not just the insurance adjuster's estimate. I found that having a third-party appraiser review the initial estimate before agreeing to a total loss designation changed the outcome in about thirty percent of the cases I reviewed, either by lowering the estimated repair cost or by raising the assessed vehicle value based on market conditions.

What to Do If You Are Involved in a Similar Incident
Exchange information at the scene but do not discuss fault. Do not post about the accident on social media. Document everything with photographs of the scene, vehicle positions, skid marks, and visible damage. Get contact information from any witnesses. Request the police report by name and date of incident from the responding agency. Notify your insurance company within the timeframe required by your policy, which is typically twenty-four to seventy-two hours. Consult with an attorney before providing any recorded statement to the other party's insurer. High-value vehicle accidents carry higher stakes because the financial exposure is larger and the media interest is more likely. The procedures remain the same as any standard collision claim, but the pressure to settle quickly and the complexity of valuation make professional guidance worth the cost. Most attribution firms offer a free initial consultation, and that conversation alone can prevent you from accepting a lowball offer before you understand the full scope of your claim.