Navigating PNC CD Rates in the Current Market
CD rates at PNC have been sitting in a weird spot lately. The bank isn't exactly leading the charge on high-yield savings, but there are ways to work with what they're offering if you're already a customer or value the branch accessibility. I opened a PNC CD account back in early 2023 when rates were climbing. What I learned quickly is that their published rates don't always match what you can actually negotiate. The rate on their website might show 4.5% for a 12-month CD, but if you walk into a branch and ask specifically about relationship pricing, you could easily get another 25 to 50 basis points depending on your account history. Here's what most people miss. PNC structures their CD ladder program differently than online banks. Their "Auto-Renewal" option automatically rolls your CD into a new one at the current rate, which sounds convenient until rates drop and you're stuck at the old rate for another full term. You have to actively call and request early renewal or withdrawal to avoid this trap.
The actual process for opening a PNC CD is straightforward if you're already banked with them. Log into PNC.com, navigate to the checking and savings section, select CD accounts, and choose your term. You'll need a minimum of $500 to open most standard CDs. For their premium tiers, which offer slightly better rates, the minimum jumps to $1,500 or sometimes $2,500 depending on the term length. I learned the hard way about the early withdrawal penalty. It's typically 90 days of interest for CDs under 18 months, and 365 days of interest for longer terms. That penalty is calculated using a simple interest method, not the more complex annual percentage yield method some other banks use. This means your penalty could be slightly different than you expect if rates have shifted since you opened the CD. For those shopping around right now, here's a practical approach. Don't just look at the headline rate. Check whether PNC offers any promotional rates for new customers or rate boost programs for existing relationships. Their Pledge Savings account, which requires linking external accounts, can sometimes push your CD rate up marginally. It's not a game-changer, but it's something.
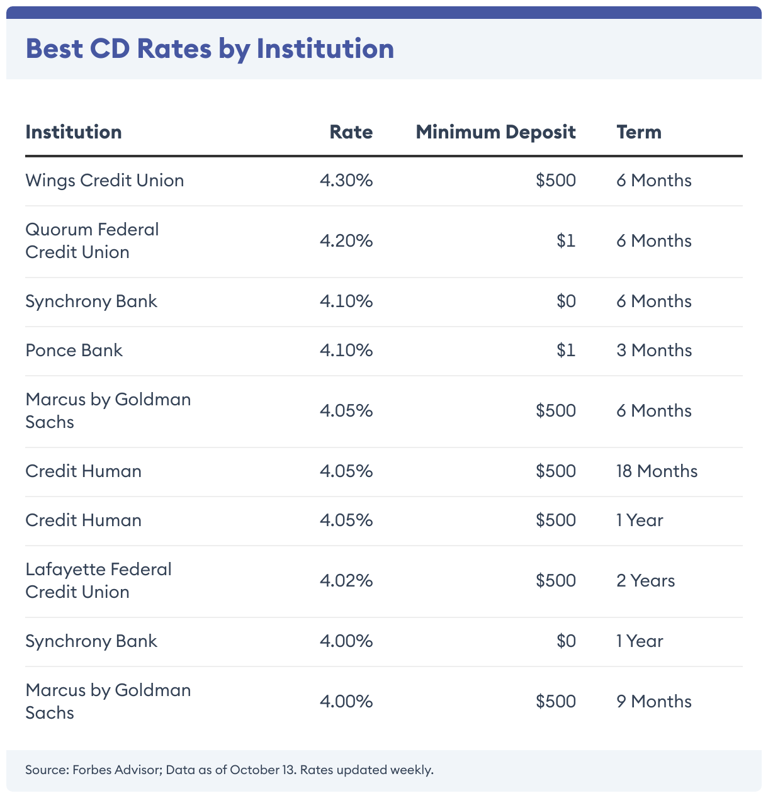
The biggest limitation with PNC CDs is their geographic focus. While they've expanded nationally, they don't compete well against online-only banks like Marcus, Ally, or Discover on pure yield. If maximizing return is your only goal, PNC probably isn't your best move. But if you already have checking and savings accounts there and prefer having a physical branch for issues or questions, the convenience factor might offset the slightly lower rate. One specific edge case I ran into: PNC occasionally offers "Rate Bump" CDs where they guarantee a one-time rate increase if market rates rise during your term. This was available during the 2022 rate hike cycle. It's rare now, but worth asking about when you apply. I know a few people who caught that option and saved themselves from missing out when rates ticked upward mid-term. For current rates, check PNC's website directly or call your local branch. Their online rates tend to be slightly higher than branch-only offers. The national average for a 12-month CD sits around 4.0 to 4.75% as of mid-2024, and PNC typically lands in the middle to upper range of that bracket for standard offerings.
Get the Full Details

Bottom line: PNC CDs are a reasonable choice if you prioritize relationship banking and branch access. They won't blow you away with the highest yield, but they're competitive enough, and the negotiation room for existing customers can make them worthwhile. Just pay attention to the early withdrawal terms and auto-renewal settings before you lock in your money.