The Rupee Is Under Pressure
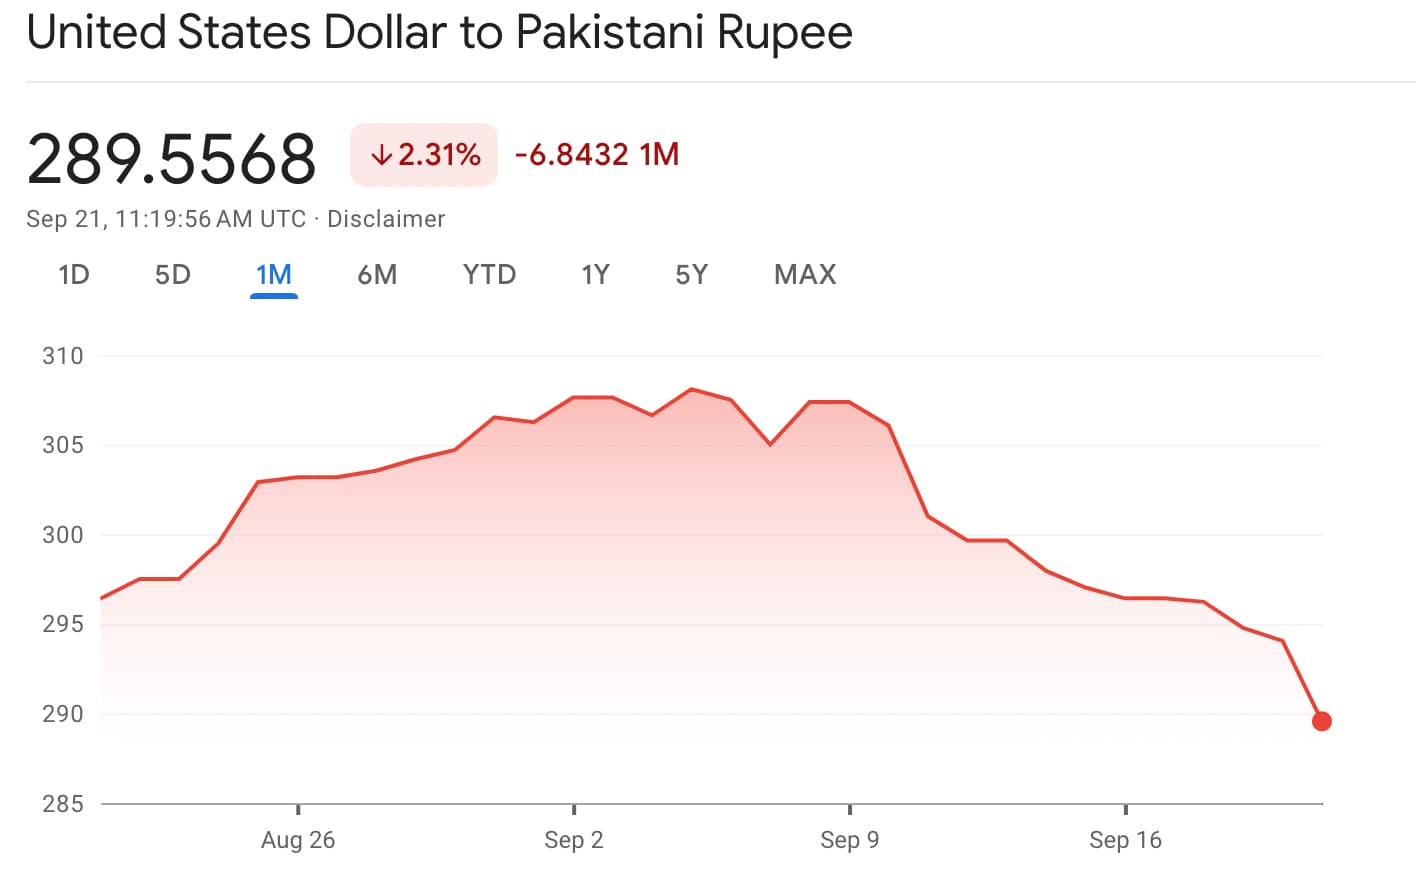
Pakistan's currency has been falling for a while now. The rupee loses value against the dollar, imports cost more, inflation rises, and ordinary people feel it at the supermarket. It is not a complicated story but it is also not something that resolves quickly. When I worked on trade finance deals in Karachi a few years back, the FX desk would call me at unpredictable hours because the interbank rate had moved ten paise overnight. That used to matter for letters of credit that were already negotiated. You learned to build buffers into your pricing and you accepted that the final settlement could differ from what you estimated three months earlier. The Pakistan rupee trades in a managed float. The State Bank intervenes when volatility threatens reserves, but they do not defend a fixed level. That is different from the old system where the rupee was pegged and everyone knew where it would close. In a managed float, you watch the Karachi Interbank rate, the official SBP display rate, and the open market rate, and they sometimes differ by a few paise. For most people the difference is noise. For importers it is the margin between making a deal or losing it. Devaluation fears come from a few structural problems. Pakistan runs a chronic current account deficit, meaning the country buys more goods and services from abroad than it sells. Energy imports alone consume a large slice of foreign exchange. Remittances help, usually flowing through formal channels because families sending money home prefer the safety of bank transfers over hawala. But remittances are not infinite and they respond to exchange rate incentives. When the rupee weakens, remittance flows tend to increase because senders get more local currency for the same dollar amount. That is one reason you see spikes in inflows right before elections or during festivals.
The IMF plays a big role here. Pakistan has borrowed from the fund many times since the 1950s. Each program comes with conditions. The usual list includes tightening monetary policy, raising energy tariffs, expanding the tax net, and allowing the currency to adjust rather than defending an unsustainable peg. The last time a program stalled, reserves dropped to a level where the country could barely cover two weeks of imports. That happened in 2023. Markets noticed. The rupee sold off. The SBP raised rates sharply and eventually secured another facility. I remember being in a meeting where a banker told me the exact threshold they use internally. If reserves fall below fifteen billion dollars, they start restricting certain import categories. It is not an official policy but it is how the system works in practice. Clothing, certain electronics, and vehicle parts faced delays because the letters of credit simply did not get opened. The workaround was to negotiate payment terms that shifted risk away from the importer, usually by using standby letters of credit from banks in Dubai or Singapore. That added cost but it kept supply chains moving. The countervailing force is that devaluation is not always bad. A weaker rupee makes exports cheaper. Textile suppliers in Faisalabad and Karachi benefit because their goods become more competitive in Europe and the US. But the benefit is slow. Orders take months to materialize and contracts are often priced in dollars anyway. The immediate pain comes from higher import prices. Fuel, machinery, medicine, and edible oils all cost more in local currency. That feeds into inflation quickly.
Interest rates rise as a response. The SBP's policy rate climbed above twenty percent at one point. That is very high by any standard. It helps attract portfolio flows and supports the currency, but it crushes domestic borrowers. Manufacturers with variable rate loans saw their interest expenses double in a year. Some closed factories temporarily. Others shifted production schedules to avoid holding inventory that would lose value in rupee terms. There is a common misconception that the IMF writes checks that Pakistan can spend however it wants. The reality is tighter. Fund disbursements are usually tied to specific performance criteria. Parts go toward balance of payments support, which indirectly backs the currency. Some tranches help with debt servicing to avoid defaults. A few are earmarked for structural reforms like tax administration changes. The money does not appear in some central bank vault ready for discretionary use. When I advised a small export house a few years back, they asked whether they should hedge their receivables. I told them to hedge about sixty percent and leave the rest unhedged. Full hedging costs too much in a high interest rate environment because the forward points reflect the rate differential. Leaving some exposure meant they could benefit if the rupee weakened further, which it tended to do over the contract period. That is not textbook advice but it works in practice when you know the trajectory.
Get the Full Details
The down side of IMF support is that it extends the life of a problematic system rather than forcing a clean correction. Critics argue this creates moral hazard. The counter argument is that unmanaged adjustment leads to deeper recessions, banking stress, and social unrest. Pakistan has seen all three during past crises. The 1998 default is the obvious example. Markets locked out for years. Growth stalled. It took a decade to recover credibility. For someone tracking this from outside, the key indicators are reserve levels, the budget deficit, inflation trajectory, and the pace of disbursement under the current facility. The most recent program is a forty-six dollar arrangement under the Extended Fund Facility. It runs for three years with quarterly reviews. If Pakistan misses a target, the next tranche gets delayed. That happened once during the negotiations in 2024 over tax reform targets. The delay lasted about six weeks and the rupee dropped roughly four percent during that window. The political dimension matters more than most analysts admit. Any government that agrees to IMF terms faces backlash. Subsidy removals, tax expansions, and fuel price hikes are unpopular. Elections often shift the timeline. A new administration may renegotiate or pause reforms. That uncertainty is baked into the exchange rate every time polls open.
If you are dealing with Pakistani rupees directly, keep three things in mind. First, the interbank rate and the street rate diverge during stress periods. The difference can reach half a percent or more. Second, correspondent banks sometimes apply extra due diligence on Pakistani transactions because of sanctions screening and anti-money laundering checks. Delays of two to three days are normal in peak stress periods. Third, the SBP occasionally changes rules on remittance repatriation or import financing without much notice. Checking the monthly monetary policy statement and the daily FX circulars saves headaches later. The rupee will not stabilize until the fiscal position improves enough that the current account deficit narrows without relying on short-term borrowing. That requires either higher exports, lower energy imports, or sustained remittance inflows. None of those happen quickly. The IMF facilities buy time but they do not solve the underlying imbalance. In practice, that means the currency will continue to trend weaker with periodic spikes during balance of payments stress. Traders who understand the rhythm make money. Everyone else just feels the price changes.