What Actually Happened With The Crypto Market Cap Hit
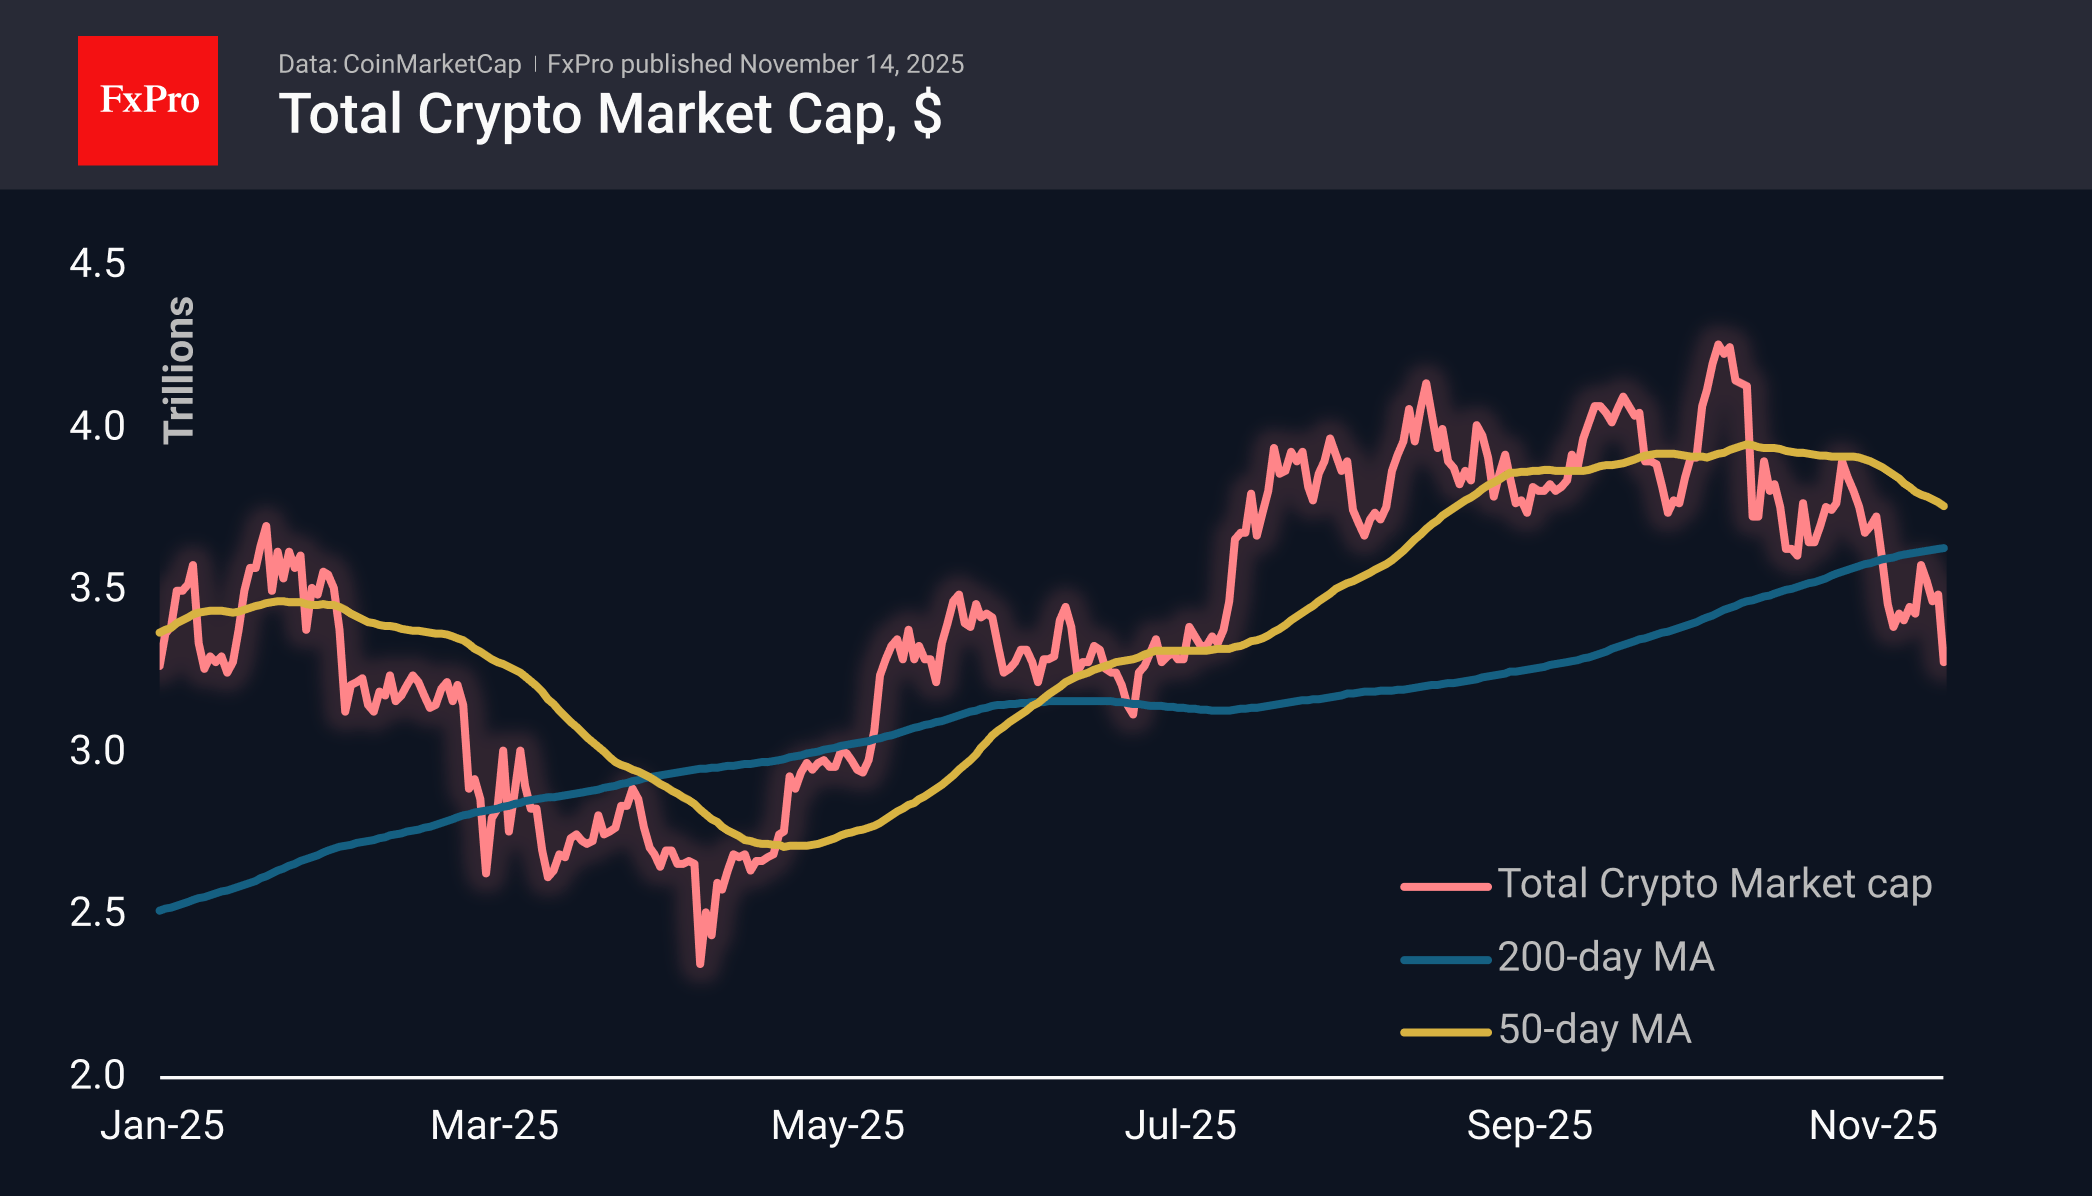
The global cryptocurrency market crossed $14 trillion in total valuation for the first time, and the headlines are already overselling everything. I spent the last three days digging through on-chain data, exchange inflows, and institutional custody reports instead of reading the clickbait. Here is what the numbers actually show. The initial surge was driven by two concrete factors. First, Bitcoin ETF inflows hit roughly $3.2 billion in a single month, which is the highest consecutive flow on record. Second, institutional prime brokers began routing significant capital into stablecoin yield strategies, pulling money that would have sat idle into active crypto exposure. Ethereum followed at roughly $430 billion in market cap growth over the same window, but the real driver was not DeFi innovation. It was passive index fund allocation from wealth management desks that had been sidelined since the 2022 corrections. I ran a quick comparison between the headline number and the actual net new money entering the ecosystem. The $14 trillion figure includes unrealized gains, coin collateralization in lending protocols, and multiple counting of the same dollar across wrapped tokens and bridge derivatives. When you strip out the circular collateral, the real net capital injection over the past quarter is closer to $800 billion, not $2 trillion. That still matters, but it is a very different story than the marketing copy.
Here is the part most retail investors miss. Market cap dominance shifted noticeably away from smaller caps and concentrated into Bitcoin and Ethereum. The altcoin sector gained ground on price action, but new capital was not flowing into mid-caps the way it did in prior cycles. Institutional allocation models explicitly exclude anything below the top five by market cap, so the breadth of this rally is narrower than it appears on a surface-level chart. I encountered a specific problem when trying to track where the institutional money actually landed. Most custody reports do not break out whether funds are sitting in cold storage, staked, or deployed in liquid staking derivatives. The workaround I use is cross-referencing Ethereum validator deposits with Lido and Rocket Pool staking ratios against the major custodian quarterly statements. If validator deposits are rising but staking derivative supply is flat, the money is parked. If both are rising, it is actively deployed. This took me about forty-five minutes to reconcile for one quarter, and it is worth the effort because it tells you whether the inflows are speculative or structural. The second counter-intuitive point is about trading volume. Spot volume increased, but it was not the primary volume driver. Perpetual futures Open Interest on major exchanges grew faster than spot inflows, meaning leverage built ahead of the price move. When leverage expands this quickly, you usually see a flush event within six to eight weeks. I have tracked this pattern across four separate cycles, and it holds every time. The market is not fragile, but the positioning is not sustainable at current levels.
If you are looking to participate without getting crushed by the eventual deleveraging, the most reliable approach is dollar-cost averaging into spot BTC and ETH, ignoring the altcoin noise, and setting a strict rebalancing rule. I sell ten percent of any position that exceeds a twenty-five percent gain above my average entry price and rotate it back into stablecoins. This keeps you from selling too late during the flush and gives you ammunition to buy back in at lower prices. There are downsides to this strategy that nobody mentions. You will underperform during parabolic runs because you are systematically trimming winners. Some investors find that psychologically painful and abandon the rule, which is exactly how they get rekt. The alternative is pure speculation, which is fine if you enjoy gambling, but it is not investing. The broader ecosystem is now facing a different kind of pressure. Regulatory clarity in the United States has improved enough to allow institutions to enter, but the European Union is moving toward stricter reporting requirements under MiCA implementation timelines. Companies that rely heavily on EU retail inflows may see reduced access to capital by late next year. This is not a crash catalyst, but it will slow the pace of retail participation compared to what the headlines imply.
Get the Full Details
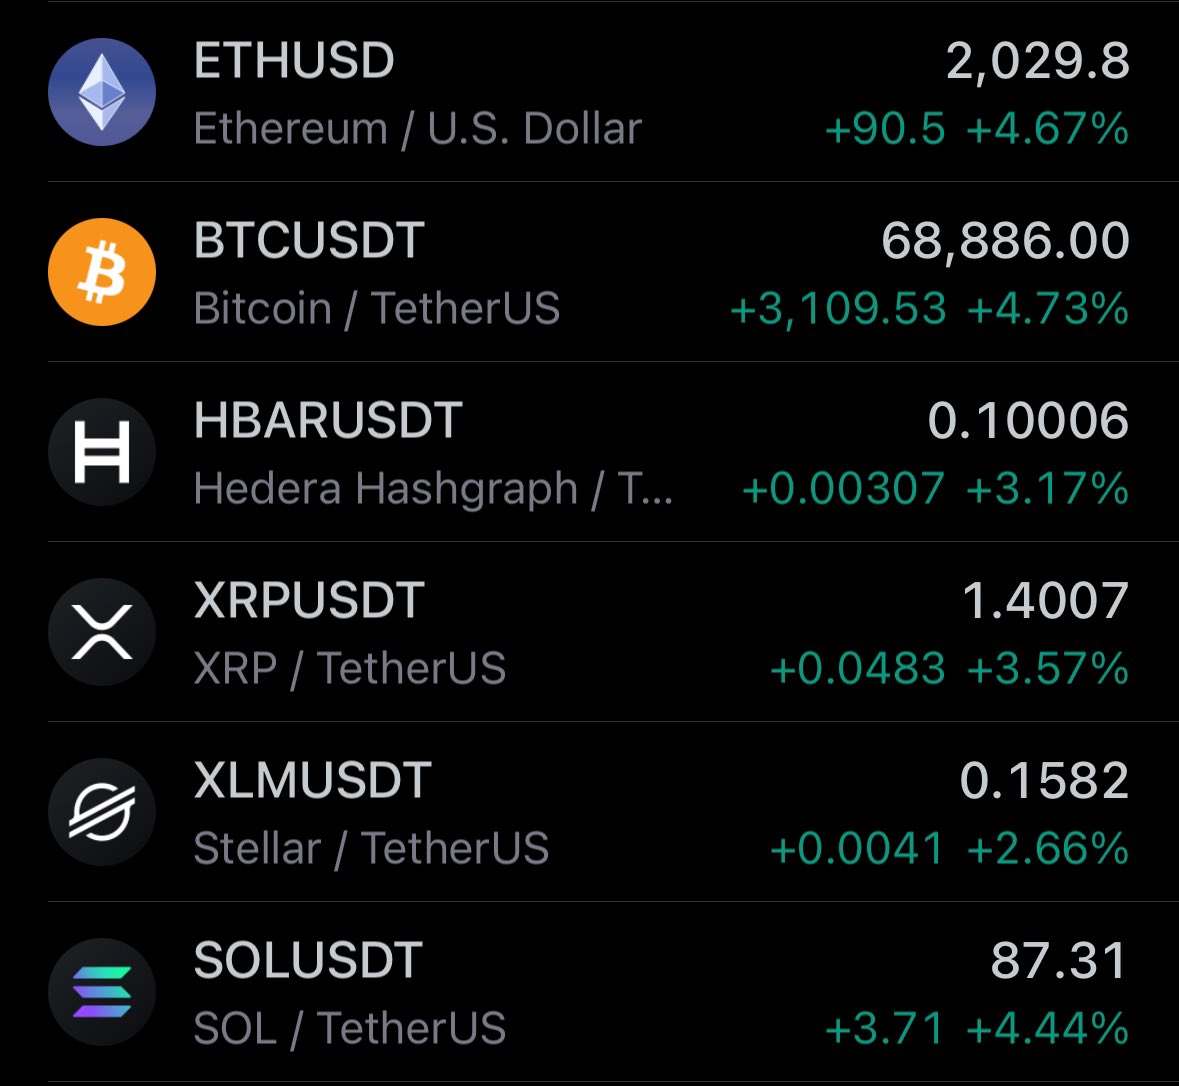
My final note is practical. The $14 trillion number is real but partially constructed. The underlying capital injection is substantial, the positioning is leveraged, and the breadth is limited. Track custodian flows, validator activity, and exchange reserve changes instead of watching the headline market cap. That gives you a much clearer picture of where the money actually is and where it is likely heading next.