Getting Started With Permatanet
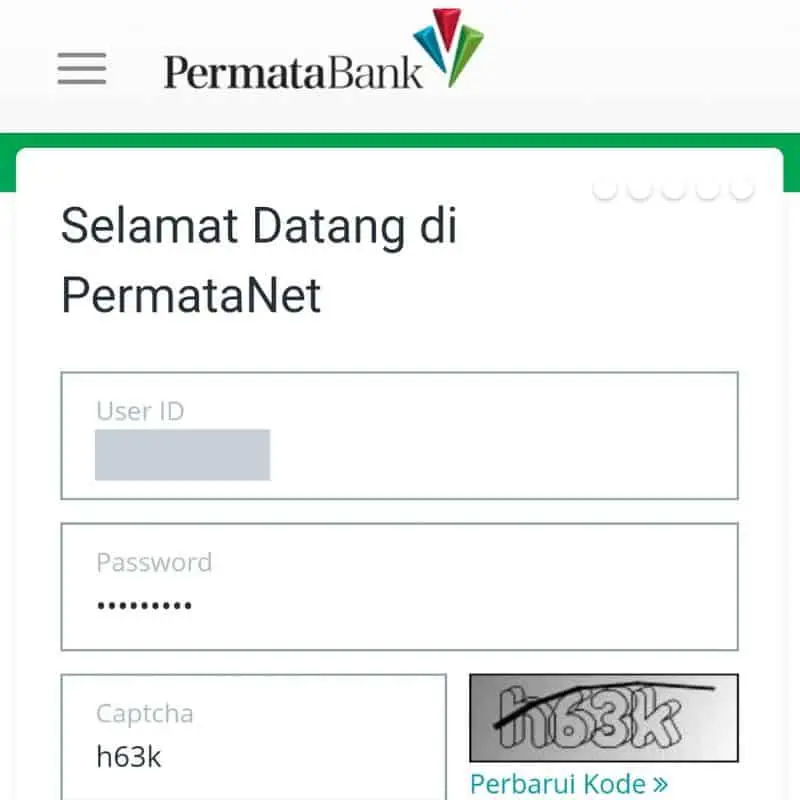
Permatanet is the online banking portal used by several Malaysian banks, including those tied to the Permatang region. If you run a small business and need to manage payments, check balances, or move money between accounts without visiting a branch, this is one of the interfaces you'll deal with regularly. It works through a browser on your computer or phone, and the general process is similar across most platforms that use this system. To get in, go to your bank's main website and look for the business or corporate banking section. The login page asks for an ID, which can be either your account number or a user ID your bank assigned when you signed up. Then you enter a password. On the next screen, you'll likely see a one-time PIN generated by a token device or sent to your registered phone. Type that in, and you're through. I spent about twenty minutes last year locked out because I mixed up my account number with my user ID. Both were available in the welcome email my bank sent, but they are different things. The account number identifies your business account. The user ID is your personal login credential. Use the wrong one and the system just sits there and gives you an error. Double-check which field is asking for which before you type.
What You Can Actually Do Once Inside
The interface lets you view account balances across all your linked business accounts. You can run fund transfers to other accounts, either within the same bank or to external accounts. There's also a bill payment section if your business needs to pay suppliers or utilities through the system. Some branches offer standing instruction setup so recurring payments happen automatically on a schedule you define. The transaction history is fairly detailed. You can usually filter by date range, amount, or transaction type. I find the export function useful when reconciling accounts at the end of the month. It gives you a CSV or PDF depending on your browser settings.
Common Problems And What To Do
The session times out after about ten minutes of inactivity. This happens whether you are working on a desktop or a phone. If you are mid-transfer and step away for a call, you will lose your progress. The system logs you out and you have to start over. It sounds minor but it wastes time when you are trying to process multiple payments. I once had a transfer fail silently because the system accepted my details but the OTP expired before the submission went through. The money did not leave my account but it also did not reach the recipient. I had to call the bank's business support line and they spent twenty minutes looking into it. The workaround is simple: do not use a token or OTP until you have filled in every field on the transfer page. Verify the recipient account number twice before generating the code. Another issue is the CAPTCHA sometimes failing to load on older browsers. If your IT department has not updated browsers across the office, you might hit a wall. Switch to Chrome or Firefox and disable any ad blockers on the banking domain. They can interfere with the security scripts.
Get the Full Details
Security Considerations That Matter
Your password should be something your bookkeeper cannot guess. I have seen businesses use the company registration number or the director's birthday as passwords because they seem easy to remember. Those are the first things someone guessing would try. Mix in special characters and keep it at least twelve characters long. Write it down in a physical notebook stored in a locked drawer rather than saving it in a shared document or browser. Never share your OTP with anyone, even if they claim to be from the bank. No legitimate bank representative will ever ask for it. I had a call from someone saying they needed my PIN to verify an account update. It was a scam. The real bank would handle updates through the portal, not a phone call.
Setting Up Standing Instructions
If your business has regular outgoing payments, standing instructions save time. You set up the recipient details once, define the amount and frequency, and the system handles the rest on the dates you specify. I use this for rent, insurance premiums, and a few recurring supplier payments. One thing people miss is that standing instructions usually require a confirmation from a second authorized user on the account. If you are the only person with access, you might need to add a secondary user through your bank branch first. Without that, you cannot set up automated payments. This step alone can delay your transition from manual processing to automation by a week or two depending on how quickly you can visit the branch.
When Permatanet Might Not Be Enough
The platform works fine for day-to-day banking tasks. It is not designed for high-volume corporate transactions or complex treasury management. If your business moves large sums regularly, processes dozens of payments daily, or needs multi-level approval workflows built into the transaction process, you should ask your bank about their corporate treasury platform instead. Permatanet does not support that level of workflow control. Some smaller regional banks also have outdated mobile versions of the portal. If you need to check balances or approve a transfer while away from the office, test the mobile experience before relying on it. I found the mobile interface to be sluggish and occasionally unresponsive on certain phone models. A desktop browser remains more reliable for anything involving actual money movement.