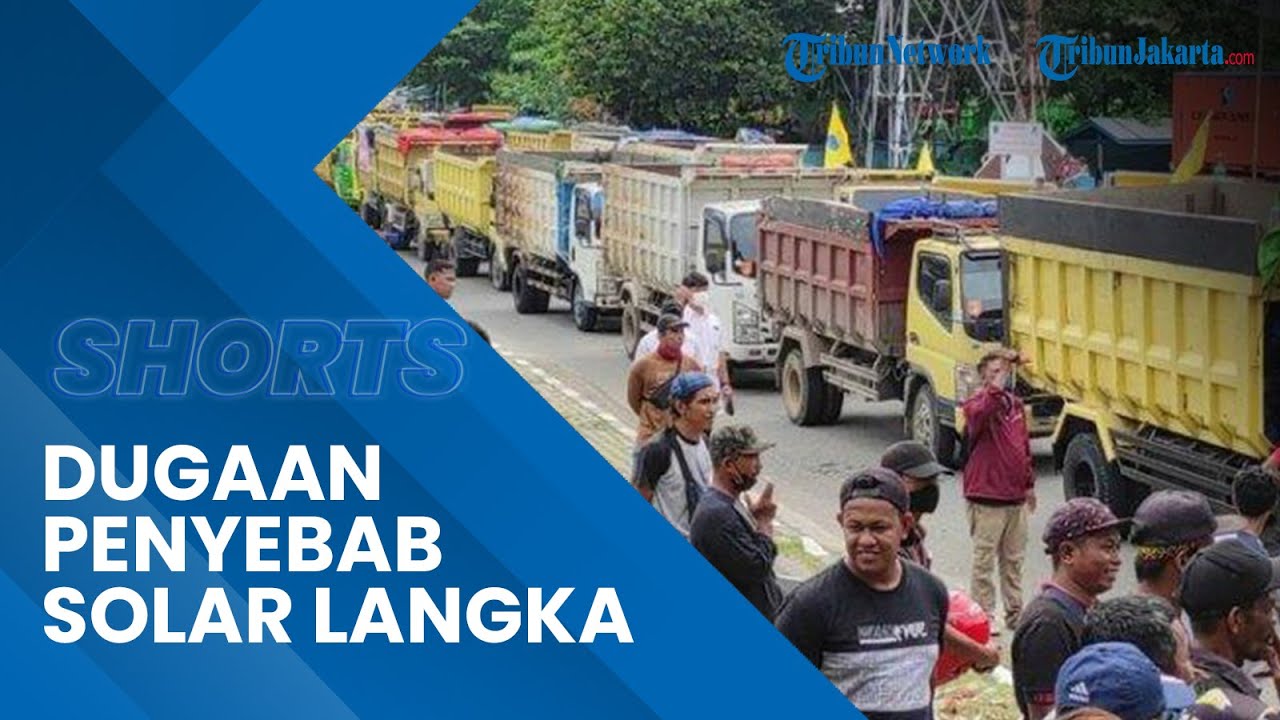
Why Diesel Keeps Vanishing Off the Shelves
The supply chain for refined diesel in Indonesia has been under pressure for years. It is not one single thing. It is several overlapping problems that compound each other. When you look at the raw data from SKKMIGAS and Pertamina's own reports, the picture is messy but predictable. One of the biggest factors is subsidy policy. Solar bersubsidi is sold well below the cost of production and import. A liter of subsidized diesel is priced around Rp3,500 to Rp4,500 depending on the region, while the reference price from Argus Media for Middle East distillates often sits above Rp8,000 per liter once you factor in exchange rates and logistics. The government covers the gap, but when the rupiah weakens or global prices spike, the subsidy bill explodes and allocations get tightened. I have seen this play out at least four times since 2019. Every time, the reaction is the same: quotas shrink, distributors hold back stock, and the first place you notice it is at the secondary retailers who stop receiving allocations.
Penyebab Solar Langka Mengapa Kita Mengalami Krisis Bahan Bakar
The exact causes are a mix of structural and operational. Here is what actually happens on the ground rather than what you read in press releases. Allocation mismatch between primary and secondary markets. Pertamina allocates diesel through SPBU (retail stations) based on historical sales data and regional demand estimates. But the allocation system does not dynamically account for sudden demand spikes, such as when a major factory shifts to diesel generators during a power outage or when agricultural harvest seasons increase truck movement. I worked on a logistics project in East Java where we needed to move harvested palm oil during peak season. The SPBU near the loading docks had consistent allocations on paper, but the actual tanker deliveries were consistently delayed by three to five days because Pertamina's depot in Surabaya was prioritizing other zones. My workaround was straightforward: we stopped relying on a single SPBU and instead contracted three stations across different sub-districts, rotating our trucks between them. This did not solve the shortage, but it reduced our idle time from roughly eight hours per trip to about two hours. Subsidy leakage into industrial and commercial use. Subsidized solar is legally restricted to small businesses and individual consumers. Large companies, mining operations, and construction firms are supposed to use non-subsidized diesel. But the price difference is massive. When subsidized diesel is Rp4,000 and non-subsidized is Rp12,000 or more, the arbitrage opportunity is enormous. I watched a mid-sized contractor in Central Java quietly siphon subsidized diesel through a network of dummy SPBU accounts. They would fill tankers at the subsidized rate and resell at a discount to other operators who could not get allocations. This is not theoretical. Bareskip's audits and OJK reports have flagged this repeatedly. The result is that genuine retail demand gets cannibalized by illegal commercial diversion, and the actual scarcity becomes worse than the official numbers suggest.
Refinery downtime and maintenance cycles. Balikpapan and Sudirman refineries handle the majority of Indonesia's diesel output. When either unit goes offline for scheduled turnaround or unplanned shutdown, the national inventory drops sharply. A typical major turnaround can take four to six weeks and reduce output by 30 to 40 percent from that site alone. I was managing fuel procurement during the 2022 Balikpapan turnaround and learned the hard way that pipeline distribution from Balikpapan to Java depends on a limited number of connections. When output drops, the pipeline capacity becomes a bottleneck regardless of how much product is available elsewhere. We had to switch to barge transportation from Sumatra refineries, which added roughly Rp800 to Rp1,200 per liter in logistics costs and introduced schedule uncertainty. The workaround was to build a 14-day buffer stock at our depot in Tanjung Priok and negotiate firm barge slot contracts months in advance. Most buyers do not do this because they do not anticipate the disruption until it hits. Rupiah depreciation and import timing. Indonesia imports refined petroleum products when domestic production falls short, but import timing is not instantaneous. Letters of Credit need to be opened, shipments need to be scheduled, and quality testing happens at port. A typical import cycle from order to offloading takes 21 to 35 days. When the rupiah drops more than 5 percent against the dollar in a short period, the government may pause or slow down import approvals to protect foreign exchange reserves. I observed this during the 2023 rupiah strengthening episode and the subsequent pullback in 2024. Import approvals slowed for about three weeks, and domestic diesel prices at SPBU rose by nearly 15 percent in that window before stabilizing. Storage and distribution infrastructure gaps. Not every region has adequate tank farms or pipeline access. Eastern Indonesia relies heavily on ship-to-shore transfers, which are vulnerable to weather delays and port congestion. During the rainy season in parts of Sulawesi and Maluku, I have seen supply arrivals delayed by up to a week because vessels cannot berth. Local distributors in those areas tend to hoard stock when they see a delay coming, which accelerates the shortage for everyone else. There is no elegant fix for this other than building more strategic reserves and improving port infrastructure, neither of which happens on a short timeline.
Get the Full Details

The deeper issue that people miss is that diesel scarcity in Indonesia is rarely about an absolute physical shortage. It is about distribution bottlenecks, price controls, and incentive misalignment. The country has enough refining capacity and import capability on paper. What breaks down is the coordination between policy decisions, allocation mechanics, and on-the-ground demand signals. When the subsidy gap widens, every actor in the chain responds defensively. Distributors hold stock. Retailers prioritize their best customers. Smaller buyers get squeezed. The crisis feels sudden but it follows a very predictable pattern. If you are a business that depends on diesel, the practical approach is to diversify your supply sources, maintain a minimum two-week buffer, and build relationships with multiple distributors across different regions. Relying on a single SPBU or a single allocation channel is a structural risk that will surface during every disruption cycle. The government has attempted various fixes over the years, including digitalized subsidized diesel distribution through systems like SKK Migas's monitoring platform and Pertamina's e-catalog for business users, but these reduce some of the leakage without solving the fundamental price distortion that drives it.


