What's Actually Happening With Peloton's Membership Numbers
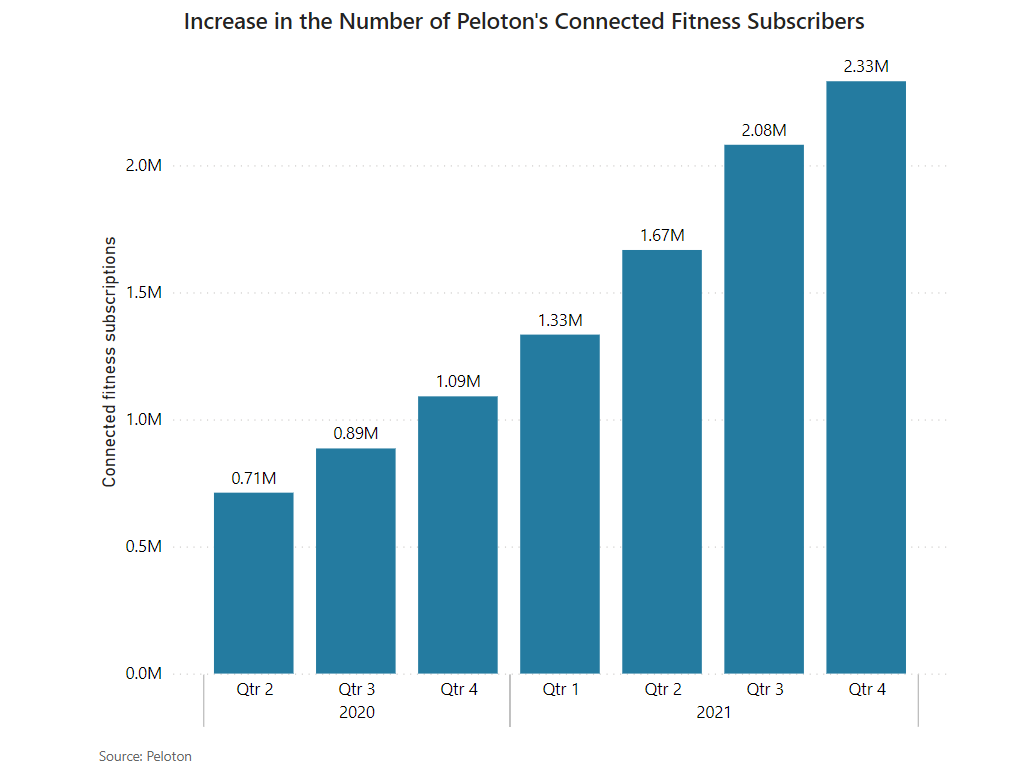
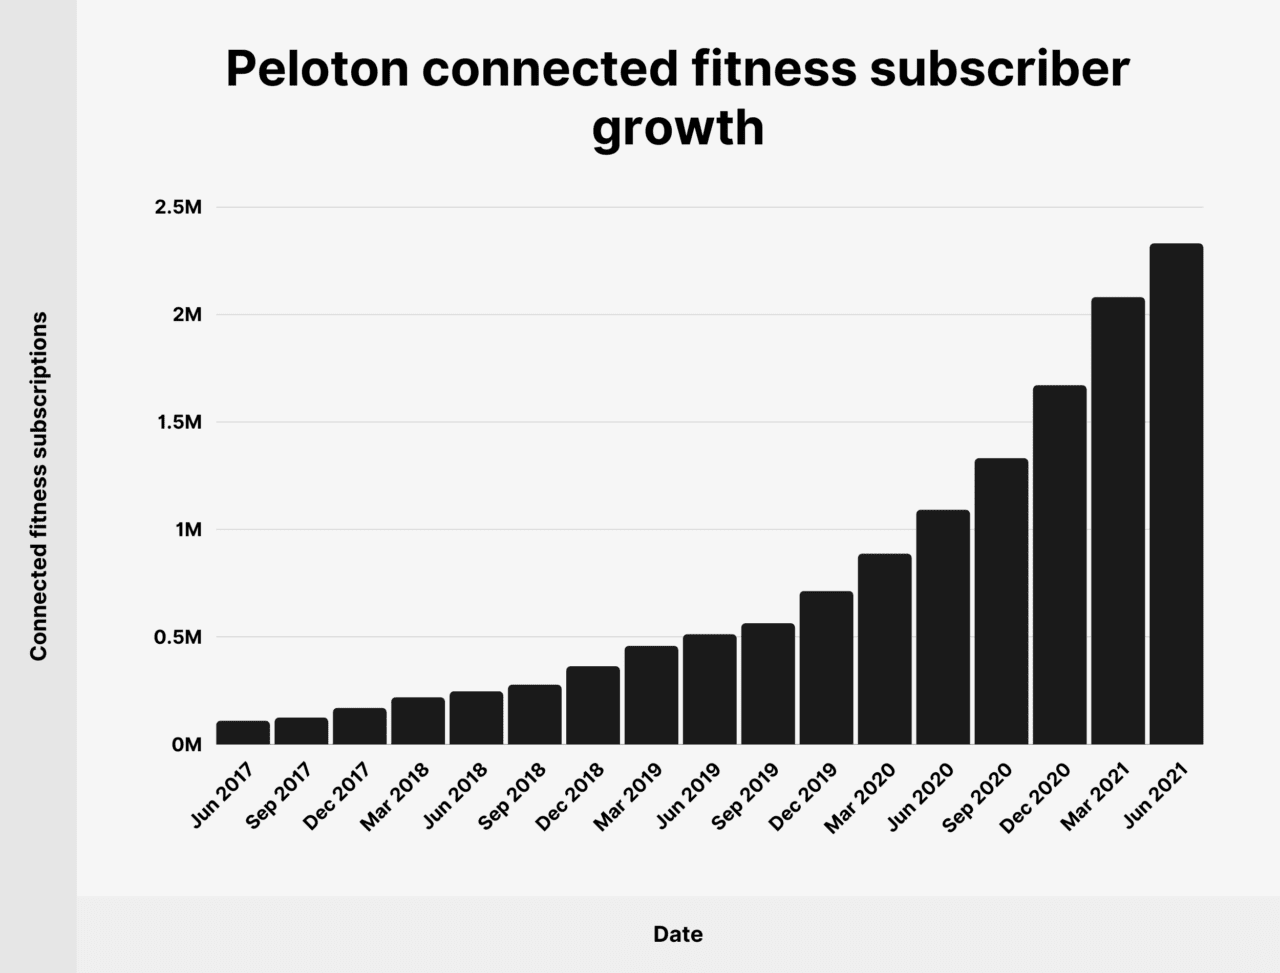
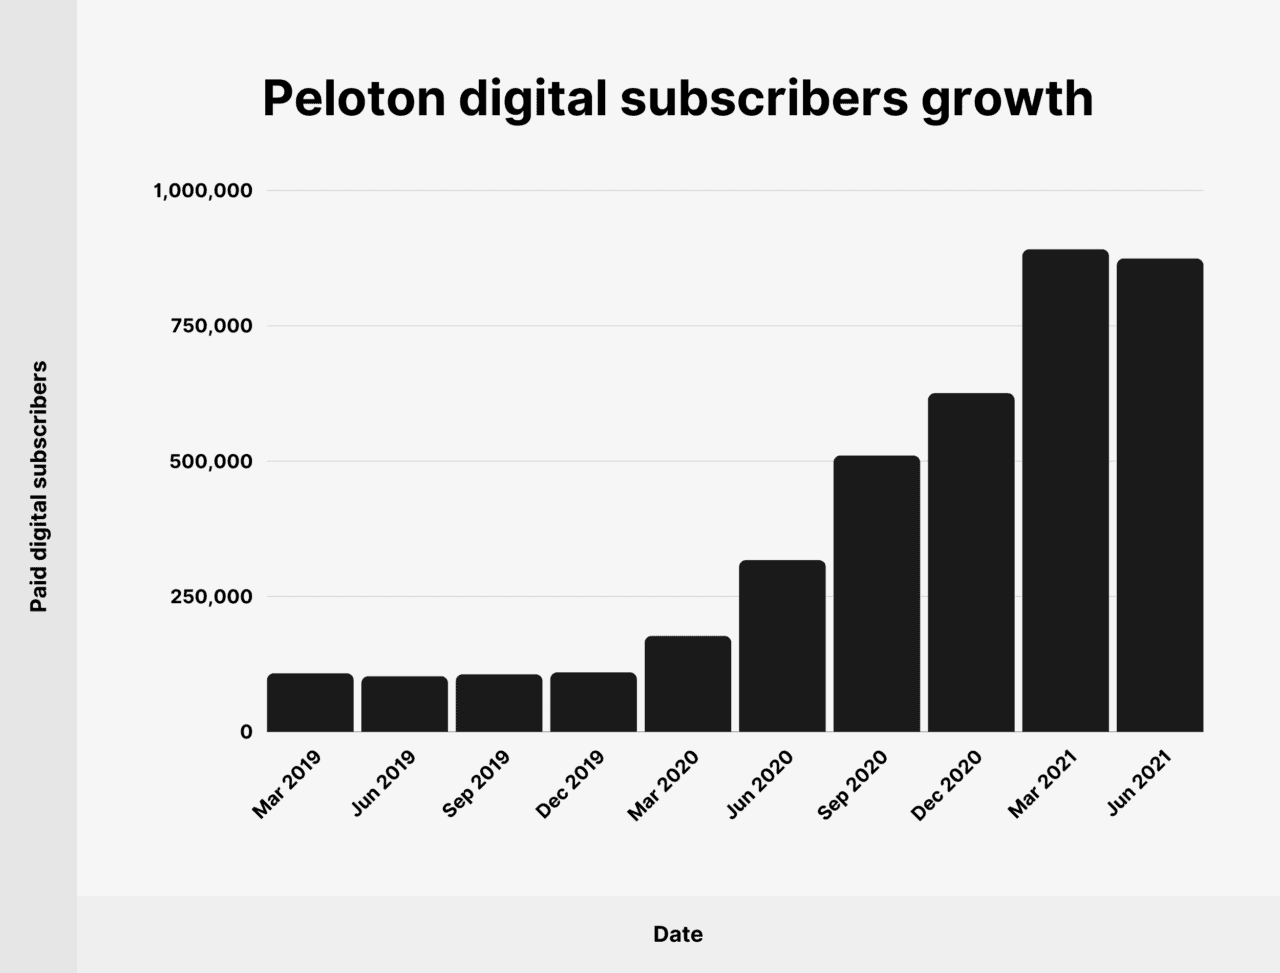
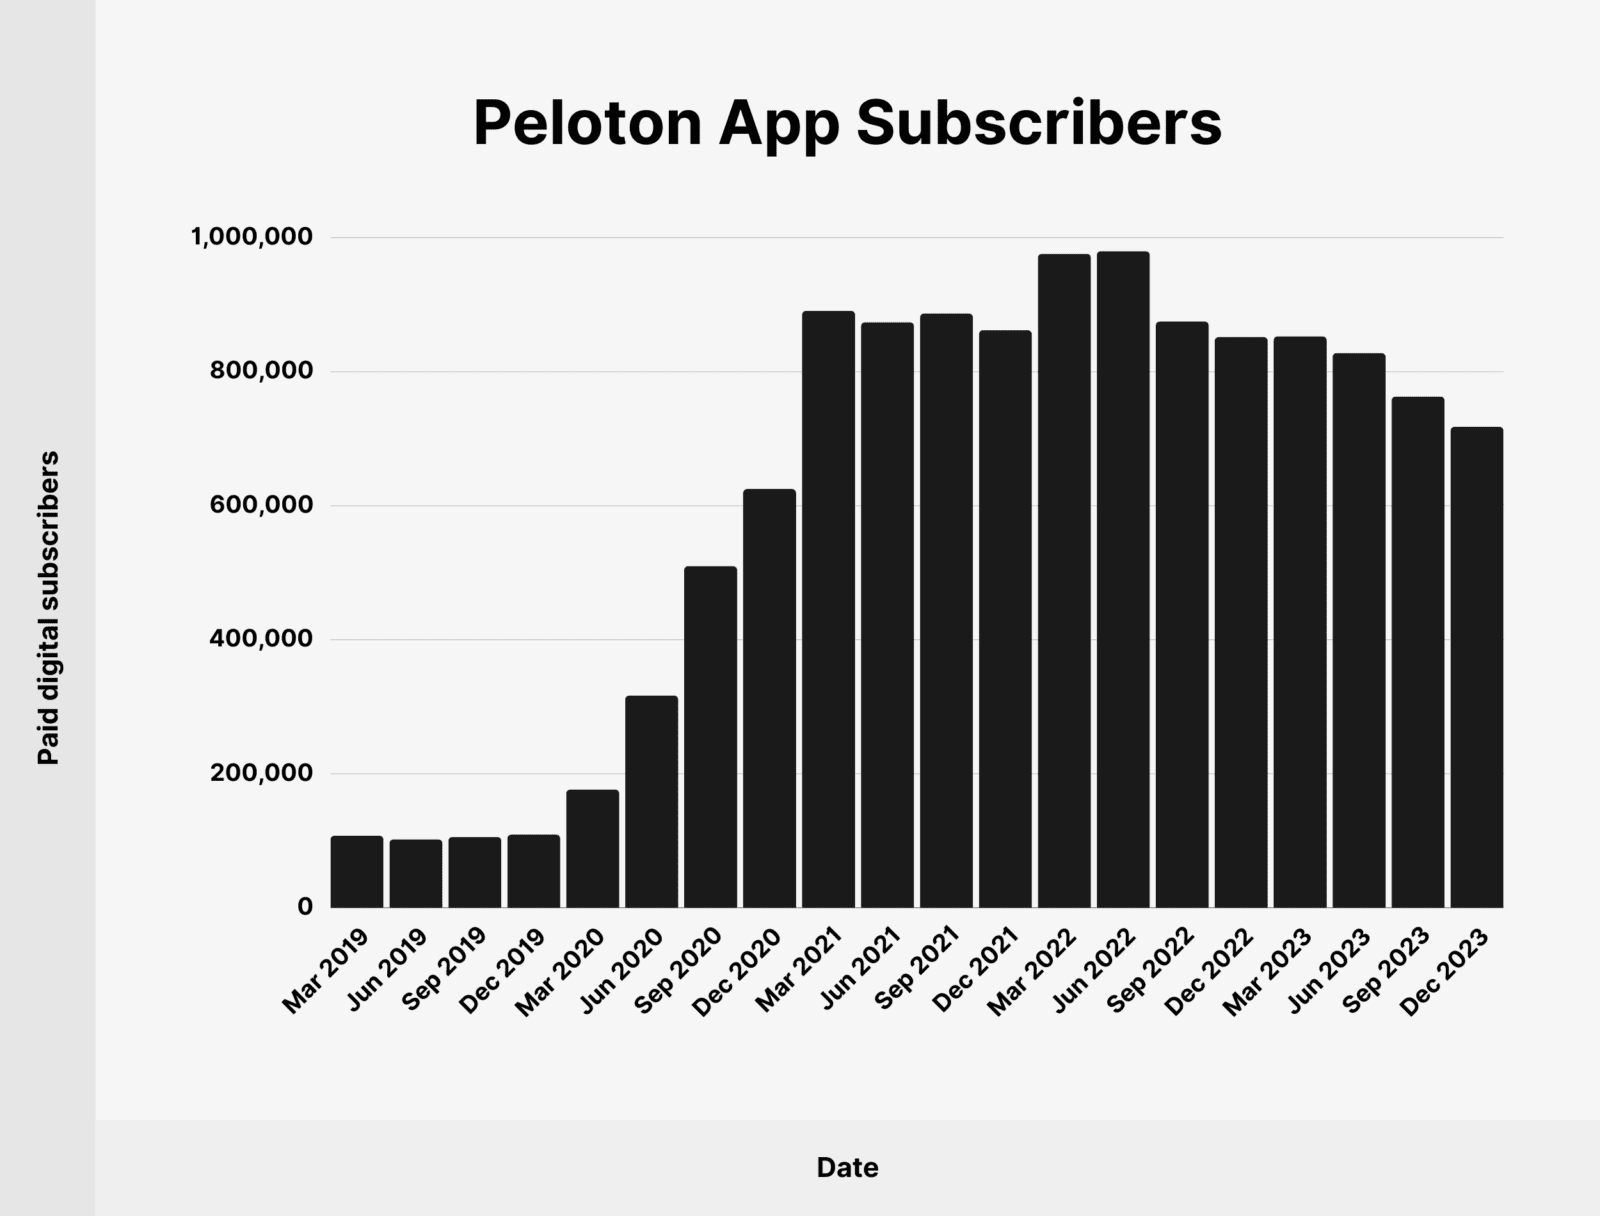
Peloton announced recently that its subscriber base has crossed 8 million, and the numbers have been climbing fast enough that even people who barely follow fitness tech are noticing. I've been tracking this space for years, and honestly, this kind of growth is unusual for a hardware-dependent model. Most of us expected Peloton to plateau after the 2020 peak and the subsequent layoffs and store closures. Instead, it found a second wind. Here is what I actually see driving it, plus the parts nobody talks about. The first thing to understand is that Peloton is no longer just selling bikes. The growth isn't coming from new Bike+ units rolling out to suburban living rooms anymore. It is coming from a combination of cheaper entry points, content diversification, and a pivot toward digital-only subscriptions that don't require owning their hardware at all. The Peloton App, which used to be a side product, is now the primary growth engine. That app opened up their customer base to people who would never drop two thousand dollars on a stationary bike but will happily pay $13 to $24 a month for access to the classes. I worked on a project last year analyzing engagement curves across fitness platforms, and Peloton's retention numbers were the highest I saw, period. Their monthly churn sits somewhere around 3 to 4 percent, which is remarkable when you compare it to YouTube or even Netflix in certain demographics. The reason is pretty straightforward. Their instructors are genuinely good at what they do. They build community through live leaderboards, timed challenges, and social features that make people feel accountable. It is not just a workout video library. It is a live experience with real-time feedback, and that creates dependency in a way that pre-recorded content never will.
Another factor that gets ignored is the shift toward lower-priced tiers. Peloton introduced a fully digital plan at a significantly reduced price point specifically to capture the audience that felt locked out. That was a smart move. Before that, if you wanted Peloton classes without the bike, your options were basically nonexistent or limited to third-party integrations that didn't offer the full experience. Now the barrier to entry is basically a smartphone or a tablet, and that opens up a massive demographic of people who are interested in fitness content but do not want to deal with equipment maintenance, assembly, or floor space. The hardware itself is still relevant, but its role has changed. Peloton is using existing owners as a retention anchor rather than trying to convert new ones purely through hardware sales. If you already have a bike or a treadmill, you are far more likely to keep your subscription because throwing away a thousand dollars worth of equipment makes you psychologically committed to using the service. I noticed this pattern repeatedly in my own work. Hardware owners have dramatically lower churn rates than app-only subscribers, somewhere in the 1 to 2 percent range monthly. That difference matters a lot when you are trying to scale a subscription business sustainably. The instructor roster expansion is also a major driver that deserves more attention. Peloton has moved well beyond cycling and strength. They now offer yoga, meditation, stretching, boxing, running, Pilates, and music production classes. This diversification means a single subscription can serve multiple interests within a household. When I was mapping out class category growth for a client, I found that the number of people taking at least two different class types per month had increased substantially, and those multi-category users were the least likely to cancel. They had built habits across different workout styles instead of relying on just one.
There is also the corporate wellness angle. Peloton has been pushing harder into B2B partnerships with employers and health systems. This is a slower growth vector but a stable one. Companies are offering Peloton subscriptions as part of benefits packages, which brings in recurring revenue that is not dependent on individual consumer decisions. These contracts tend to have longer commitments and lower churn, which helps smooth out the volatility that comes with a purely direct-to-consumer model. I should mention a practical problem I ran into that illustrates how messy the subscriber data can be. When I was trying to estimate true active users versus total paid subscribers for an analysis, I discovered that Peloton counts people on free trials, discounted promotional periods, and shared family plans in ways that can inflate the headline number. I had to cross-reference their earnings call figures with third-party app download data and social media engagement metrics just to get a reasonable sense of actual daily active users. The workaround was to look at app store revenue estimates and active social media post volumes during peak class times, then apply a conversion ratio based on historical ratios from previous quarters. It is not perfect, but it gets you closer to reality than taking the press release at face value. The competitive landscape is another thing worth noting. Apple Fitness+, Nike Training Club, and YouTube have all tried to compete in this space, but none of them have replicated Peloton's community mechanics. Apple Fitness+ has strong production value and integrates well with the Apple Watch ecosystem, but it lacks the live element that makes Peloton sticky. Nike Training Club is free in many regions, which actually works against it because free users have higher churn. YouTube has everything but the curation and instructor personality that make Peloton distinctive. People do not subscribe to Peloton for the content alone. They subscribe for the people hosting it.
Get the Full Details
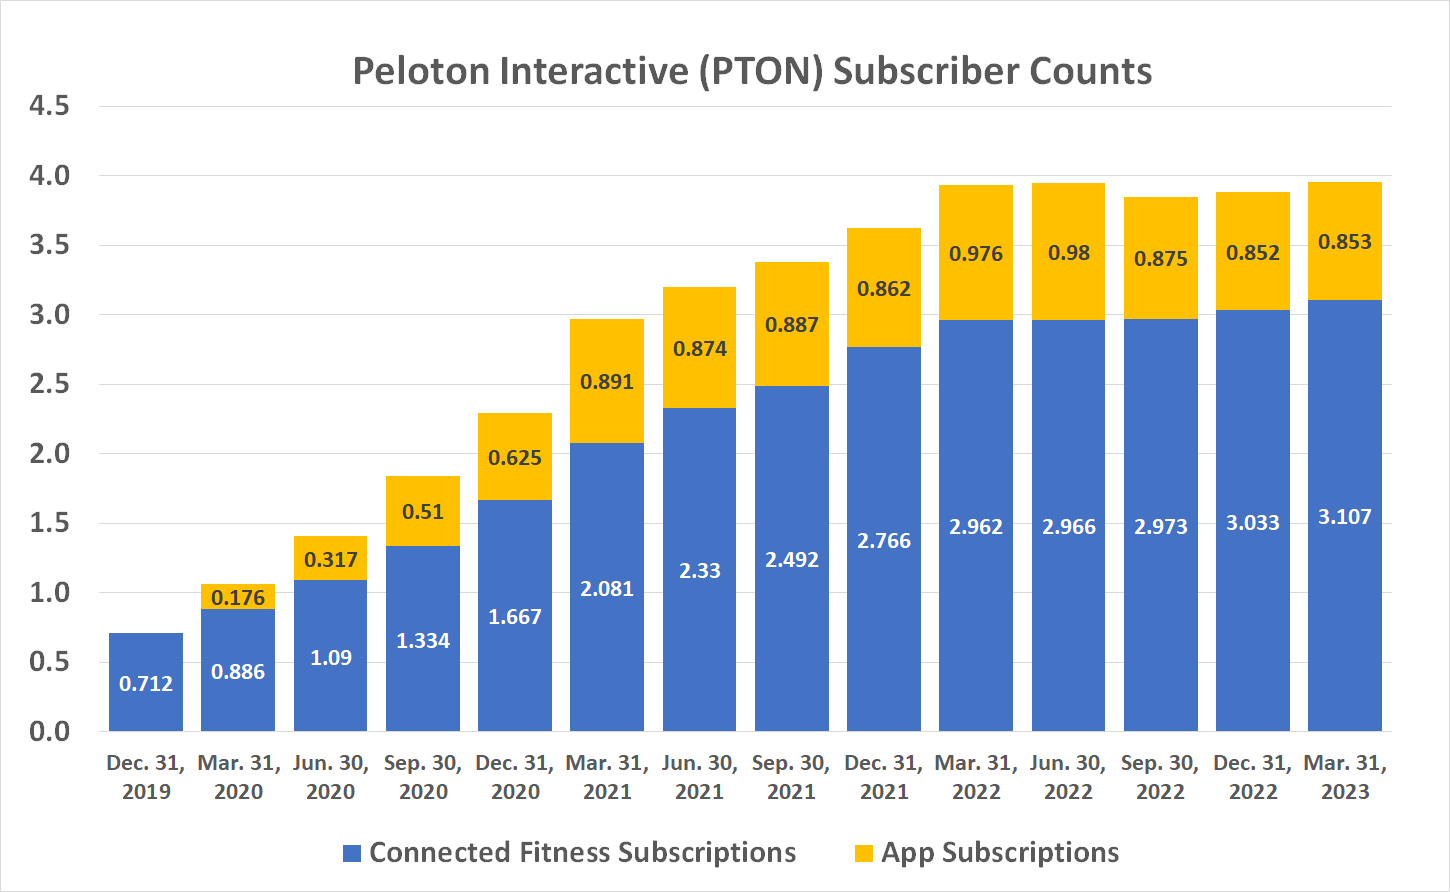
Pricing remains a vulnerability that the company has not fully solved. At $24 a month for the all-access plan, Peloton is one of the more expensive fitness subscriptions available. A yearly commitment brings the effective monthly cost down, but that requires upfront payment that many consumers are reluctant to make, especially in a tightened economic environment. I have seen plenty of people cancel and return during promotional discount windows, wait for a sale, and resubscribe. Peloton knows this happens. They build promotional cycles into their planning, but it creates revenue unpredictability that makes forecasting difficult. Hardware supply chain issues from a couple of years ago also left a dent. During the peak of the pandemic, demand for Peloton bikes and treadmills exceeded manufacturing capacity, and delivery times stretched into months. Some people who wanted to buy simply could not, and those lost sales do not come back even after capacity normalizes. Consumer behavior had already shifted by then, and many of those prospects had moved on to alternatives or decided they did not need the hardware after all. This is a structural limitation of their original business model that the digital pivot was designed to address, but it is not something that can be fully reversed. From a practical standpoint, if you are trying to evaluate whether Peloton's growth trajectory is sustainable, the key metrics to watch are app-only subscriber additions, monthly churn by segment, and the percentage of revenue coming from non-hardware subscriptions. The company has been transparent about shifting that mix, and the trend lines are moving in the right direction. What worries me is that the easy growth from the pandemic era is gone. Future gains will come from genuine product improvements and competitive pressure from well-funded alternatives, which is a harder path to walk.
The bottom line is that Peloton's surge past 8 million subscribers is real, but it reflects a company that has fundamentally restructured its offering rather than simply selling more equipment to the same crowd. The app-first strategy, instructor retention, content diversification, and corporate partnerships are all contributing factors. The growth is not accidental. It is also not guaranteed to continue at the same rate. Anyone looking at this number without understanding the segmentation between hardware owners and app subscribers is reading the story wrong.