Why Everyone is Obsessed With PDD Forecasts Right Now
PDD stock has gone through enough volatility in the past three years that people treat every earnings call like it's going to determine their retirement portfolio. I've tracked this stock since 2022, and the pattern is always the same: euphoria after a strong quarter, followed by two months of analysts scrambling to adjust models, then a quiet period where the price drifts until the next catalyst drops. The current environment is different because PDD is no longer just a China play. Their Temu expansion into Europe and North America has fundamentally changed how revenue is broken down, and that means traditional valuation models that rely purely on Chinese domestic e-commerce comps are underperforming. I learned that the hard way when I used a standard DCF in early 2024 and got a target price that was off by nearly forty percent because the model couldn't properly account for Temu's subsidized growth phase.
Pdd Stock Forecast 2025 What The Future Holds
The main factors shaping the forecast for 2025 come down to four variables, and they don't all move in the same direction. I'll walk through them without the usual analyst fluff. Chinese domestic consumption recovery. This is the baseline assumption everything else builds on. PDD's core business in China is still the cash engine. If Chinese consumer spending picks up even moderately through 2025, PDD benefits disproportionately because their price-sensitive positioning captures the segment other platforms like Alibaba and JD miss. The risk here is that recovery stalls, and we've seen the data contradict itself quarter over quarter. Temu's path to profitability. This is the variable that splits forecasts the widest. Some analysts assume Temu reaches contribution margin positivity by mid-2025. Others think it stays negative through the entire year. The truth is somewhere in between, but the margin matters enormously for valuation. I've seen forecast ranges swing by over sixty percent just depending on whether you assume Temu burns $1 billion or $3 billion in operating expenses for the full year. When I ran my own model, I had to scenario-test three separate burn rates before I landed on a number I was comfortable with.
Regulatory risk. This one gets mentioned in every report but rarely given proper weight. Both Chinese and US regulators have ongoing scrutiny of PDD. The US side involves trade policy and potential tariffs on de minimis shipments, which Temu relies on heavily. A single policy shift around that threshold could compress margins overnight. I lost sleep over this during the tariff discussions in late 2024 and ended up reducing my Temu profitability assumption by a full percentage point as a buffer. Competition from Douyin and Alibaba. Douyin Shop has been eating into PDD's market share in certain categories, and Alibaba's price-matching initiatives have forced PDD to increase subsidies in response. This isn't new, but the competitive intensity has increased in 2024 and 2025, which puts pressure on the gross merchandise volume growth rate that analysts are projecting.
Get the Full Details

How I Actually Build The Forecast
Most retail investors don't build their own models, but understanding the mechanics helps you evaluate whether the numbers you're reading make sense. Here's what a proper PDD forecast model looks like and where the common errors happen. Start with the top line. You need to separate China domestic GMV from international GMV, preferably down to Temu versus other international operations if the disclosures allow it. PDD reports these segments separately in their earnings materials, but the granularity varies by quarter. The key metric to track is the year-over-year revenue growth rate, not just the absolute dollar figures. When growth rates start decelerating, that's usually the first signal that the story is changing, and it happened to PDD in Q3 2024 before the market fully priced it in. Next, factor in the operating margin trajectory. PDD has historically run very lean compared to peers. Their operating margin has sat in the thirty to forty percent range on the China side, while Temu operates at a loss that subsidizes growth. The forecast hinges on when, or whether, those losses narrow. I use a rule of thumb: every ten basis point improvement in blended operating margin translates to roughly two to three percent of enterprise value movement given PDD's current market cap range.
For the discount rate, I use a WACC built from the China risk-free rate adjusted for country risk premium plus the equity risk premium for emerging market e-commerce names. This is where most amateur models go wrong. They either use a generic twelve percent discount rate or something absurdly low like eight percent. Neither is defensible. A reasonable range for PDD is closer to fourteen to sixteen percent depending on your risk tolerance. Terminal value is where the biggest assumptions hide. PDD is not a mature cash cow. Applying a perpetuity growth rate above three percent is generous given the competitive dynamics. I usually run sensitivity analyses between two and four percent and show the full range rather than picking one number and pretending it's precise.
The Specific Problem I Ran Into
When I first tried to model Temu's unit economics for the 2025 forecast, I hit a wall. PDD doesn't break out Temu-specific customer acquisition costs or take rates with enough detail for a clean model. I spent about three weeks trying to back-solve these numbers from aggregate international segment data, and the results were unreliable because the segment includes other smaller operations. The workaround was to use third-party app tracking data from sources like Sensor Tower and data.ai to estimate Temu's monthly active users and session counts, then cross-reference those with PDD's disclosed international revenue to derive an implied average revenue per user. It's not perfect, but it gave me a range rather than a single point estimate. From there, I could apply reasonable assumptions about conversion rates and average order value based on comparable cross-border e-commerce platforms. This approach reduced my forecast variance significantly compared to pure top-down estimation.

What The Data Actually Suggests For 2025
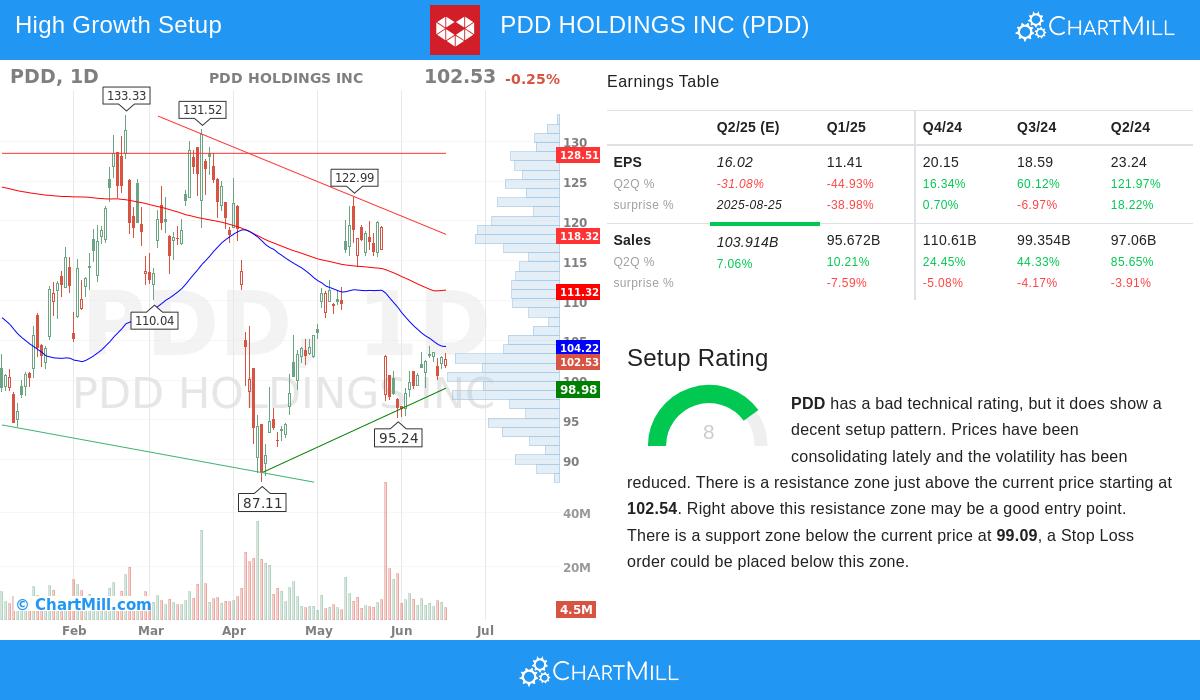
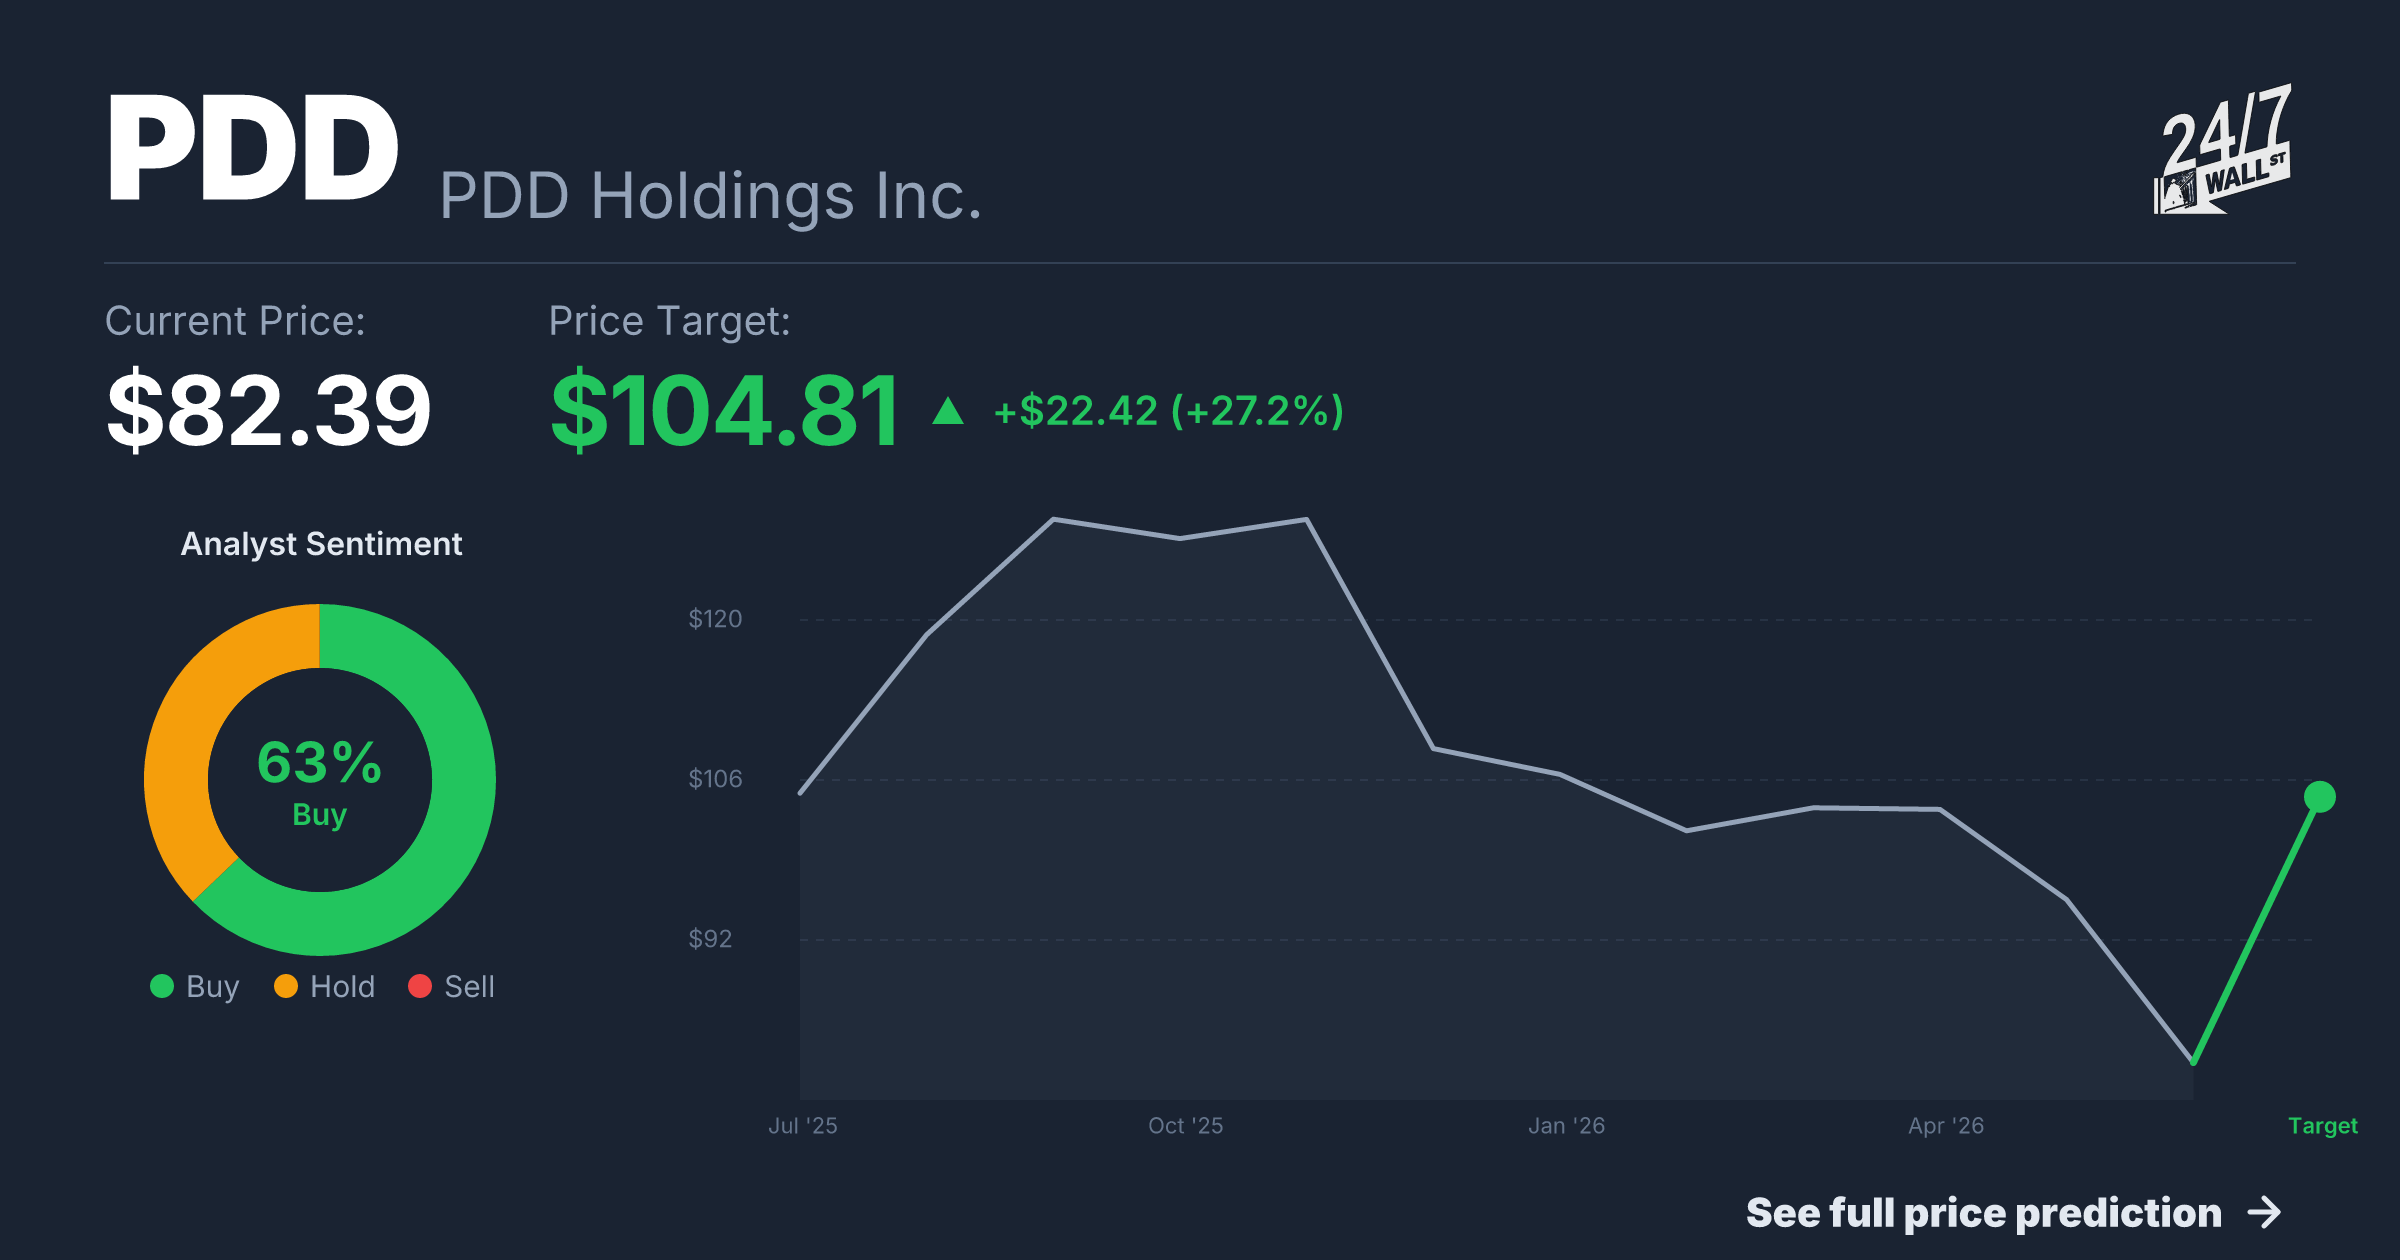
Based on the models I've reviewed and the public earnings data through early 2025, the consensus direction is cautiously positive but with much wider variance than previous years. Here's the breakdown without the hedge-fund language. The base case assumes China GMV grows in the high teens to low twenties percentage range, Temu international revenue roughly doubles year-over-year, and Temu narrows its loss rate substantially but doesn't reach full profitability. Under these assumptions, PDD earnings per share for fiscal 2025 lands in a range that implies the stock is fairly valued at current levels, maybe slightly undervalued if you believe the China consumption story holds. The bullish case requires Temu to achieve contribution margin positivity earlier than expected, China domestic growth reaccelerating, and regulatory headwinds fading. That combination would push the stock significantly higher, but each of those assumptions carries substantial risk.
The bearish case involves sustained regulatory action on de minimis shipments, a deeper than expected slowdown in Chinese consumption, or competitive losses to Douyin that force margin compression. That scenario could see the stock drop twenty to thirty percent from current levels in a short period. I've watched it happen before, and it doesn't take much catalyst.
Where The Consensus Forecasts Are Wrong
The most common mistake I see in published PDD forecasts is treating Temu as a standalone growth story without properly stress-testing the subsidy dependency. Every dollar of GMV growth that comes from heavy subsidy is not the same as organic growth. The models that look prettiest are often the ones that assume subsidies decline faster than is realistic given the competitive pressure. Another blind spot is the geographic concentration risk. Even though Temu is expanding, the majority of PDD's profitable operations remain tied to China. Any macro shock to Chinese consumer confidence hits the earnings immediately, while the international growth story takes much longer to materialize into actual profits. The market often prices in the international upside before accounting for this timing mismatch. A third issue is the accounting treatment of marketing and advertising spend. PDD classifies certain customer acquisition costs in ways that can obscure the true economics of the business when you're just looking at headline operating expense numbers. I've had to dig into the cash flow statement and footnote disclosures to reconstruct what the real burn rate actually looks like on a free cash flow basis. The difference matters more than most retail investors realize.
Practical Steps If You're Building Your Own Forecast
Gather the most recent five quarters of segment-level data from PDD's earnings releases. Don't rely on analyst summaries. Read the actual filings. The numbers are in there if you look carefully. Build separate revenue models for China domestic and international operations. The growth drivers, margin structures, and risk profiles are different enough that combining them produces misleading results. Stress test your assumptions using a spreadsheet with at least three scenarios for Temu's burn rate, two scenarios for China growth, and binary outcomes for the regulatory variables. The output won't give you a precise answer, but it will tell you what outcomes are probable versus what ones require perfect conditions to materialize.
Compare your model's implied multiples against historical trading ranges for PDD and relevant peer valuations. If your model produces a target price that implies a multiple well outside that range, your assumptions are likely too optimistic or too pessimistic. This sanity check catches a lot of errors before they become expensive convictions. Finally, set explicit triggers for when you'd revise your forecast. The stock market moves on expectation changes, not on expectations themselves. If you know what data point would make you change your mind, you're better positioned to act rationally when it arrives rather than reacting emotionally to price movement. The PDD Stock Forecast 2025 What The Future Holds ultimately comes down to whether Temu can grow fast enough to justify the current valuation while managing subsidy burn, and whether China's economic trajectory supports the domestic business without additional headwinds. Nobody knows for certain. The best forecasts are the ones that acknowledge uncertainty explicitly rather than hiding behind a single precise number.