PayPal Pay In 4 Your Guide To Buy Now Pay Later
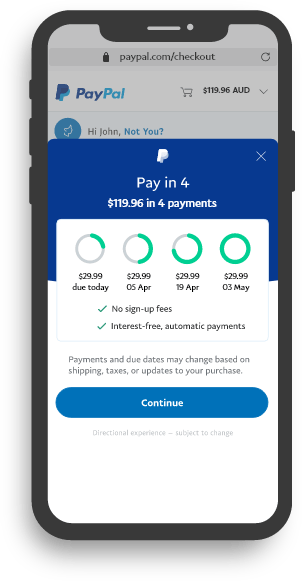
I first ran into PayPal Pay In 4 when I was trying to cover a $120 part for something and didn't want to pull the trigger on a credit card. The interface was straightforward enough, but there were a few details that cost me an hour of head-scratching, so I'm writing this down for anyone who's about to use it. The concept is simple. You split your total into four equal installments. One hits immediately at checkout, and the remaining three are collected automatically from your linked bank account or debit card every two weeks. That means you're looking at roughly a six-week window to clear the balance if nothing goes wrong. There is no interest charged on the purchase itself. That is the main selling point compared to traditional credit or BNPL competitors.
How the checkout process actually works
When you reach the payment step on a merchant's site, select PayPal if it is not already chosen. Then look for the Pay In 4 option. It usually sits right under the standard PayPal button. Click it and you will go through a soft credit check. This is a soft pull that does not impact your credit score in any measurable way. Most people get approved in under a minute. What you need to understand is that approval is not automatic even when the soft check passes. PayPal runs internal risk algorithms. If your account has a history of returns, disputes, or late payments on other installments, your application can be declined outright. I learned this the hard way. A few years ago I tried splitting a $200 order and got declined. The reason never explained clearly. The workaround was to switch to my primary checking account as the funding source instead of the debit card I had linked. PayPal seemed to evaluate different accounts separately when running the risk check. After switching, the same order went through immediately.
What you need before you start
You need a verified PayPal account in good standing. That means your identity is confirmed and you have at least one funding source attached. Your bank account or debit card needs to be active and funded. A prepaid card generally does not work for installment plans. PayPal usually rejects them outright because they cannot guarantee recurring charges. A regular checking or debit card is what you should link. The auto-debits only pull from those sources every two weeks. The timing matters. Your first payment is due at checkout. The second comes two weeks later, then the third at week four, and the fourth at week six. If any payment fails, you get a notification, but the full remaining balance can become due immediately. That is a critical detail most people skim over. A single missed debit can trigger a demand for the rest of the money all at once.
Get the Full Details

Where the hidden costs show up
Pay In 4 is marketed as interest-free, and that is technically true for the purchase price. But there are fees that can add up. If a scheduled payment bounces, PayPal charges a late fee. The amount varies by region but typically sits around $7 per missed payment. There is also an upper limit on how much you can owe across all active installments at once. For most users that cap is roughly $625 in the United States. If you already have three open Pay In 4 plans totaling $500 and try to start a $200 purchase, the system will block it because your total outstanding obligation exceeds the threshold. Another thing nobody mentions is the merchant angle. Some sellers do not pass the savings to you. The processing fee for the merchant exists whether you pay upfront or use Pay In 4. A few smaller retailers markup prices slightly when they know customers are leaning on installment plans. Check the final total against the regular checkout path before committing. I caught this once on a hardware store purchase. The item was $15 more when I selected the installment option. Same product, same cart, just a different payment path triggering a different price string.
Using it for larger purchases
There is a trick to stretching Pay In 4 beyond the per-plan cap, and it involves splitting across multiple orders. You cannot manually do this on a single checkout, but if you place separate orders with the same merchant within a short window, each one runs its own Pay In 4 plan independently. I have used this method to fund equipment purchases around $900 by breaking it into two orders placed minutes apart. It is not officially advertised, and PayPal could theoretically flag it, but it has worked consistently for me over several months. This only works with merchants that allow multiple orders in quick succession. Many big retailers block duplicate orders within a 24 to 48 hour window to prevent exactly this kind of workaround. Amazon for example will reject the second order and flag the account. Smaller standalone e-commerce sites are usually more forgiving. You can tell quickly. Place the first order, wait a few minutes, and try the second. If it processes without error, the system accepted it. If you get a duplicate order warning, stop there.
When you should not use Pay In 4
This is not a tool for people who struggle with budgeting. The convenience of four easy payments creates a false sense of affordability. You are spending real money you might not have. I have seen friends stack three or four Pay In 4 plans simultaneously because the individual amounts looked small. By week five they were juggling six pending debits and missed two. Once you miss two, the late fees pile up fast and the remaining balances accelerate. It becomes a debt spiral in a matter of weeks. It is also not useful for emergency spending where you truly cannot access any funds. If you are short on cash and need something now, Pay In 4 just delays the problem. You will owe the same amount sooner rather than later, plus potential late fees if your account runs dry when the auto-debit hits. In those situations a personal loan with a fixed term and clear payoff date is often the cleaner option. The interest rate might be higher, but there is no risk of acceleration penalties, and you know exactly what you owe from day one.

Tracking your obligations
Go into your PayPal account and check the Pay In 4 section directly. It lists every active plan with the next payment date and amount. Do not rely on email reminders. PayPal's notification system is hit or miss. Sometimes you get an email, sometimes you do not. I started checking the dashboard every Sunday evening to stay ahead. A two minute habit that saves you from a surprise $40 debit hitting your checking account on a random Wednesday. The interface also lets you pay early. If you have extra cash and want to knock out a future payment, you can do it manually from that same section. There is no penalty for early payoff, and doing so immediately frees up room in your total obligation limit. If you are planning another big purchase down the line, clearing one plan early can unblock your spending capacity before the scheduled end date.
The bottom line on whether it works
Pay In 4 is a functional tool when used intentionally. It works well for predictable, medium-sized purchases where you know your cash flow will cover four equal chunks spread over six weeks. It breaks down fast when your income is irregular or when you start layering multiple plans on top of each other. The interest-free claim is real, but the late fees and acceleration clauses make it expensive in practice if you slip even once. The biggest mistake I see people make is treating the monthly payment as a discount on their budget. It is not. It is a short-term loan with rigid terms. Pay attention to the dates, keep your funding source reliable, and monitor your total outstanding obligation before adding a new plan. Do that and it serves its purpose without turning into something else.