Getting PayPal Pay In 4 Working on Your Store
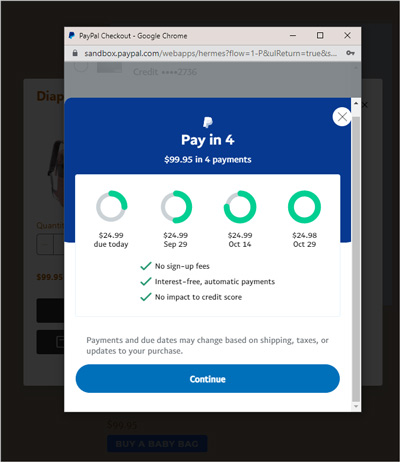
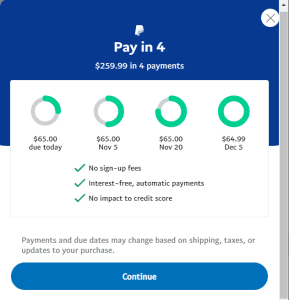
PayPal Pay In 4 splits a purchase into four equal payments collected every two weeks. The customer pays zero interest as long as they stay on schedule. Late fees apply if a payment misses its date, but the total cost never exceeds the original price unless penalties accumulate.PayPal Pay In 4 How This Interestfree Financing Is Transforming Ecommerce Checkout
The mechanics are straightforward enough. A shopper at checkout selects the option, PayPal runs an instant soft credit check that doesn't touch their credit report, and they receive immediate authorization for the full amount. The first installment is collected at the point of sale. The remaining three payments auto-debit from their linked bank account or card on a fixed schedule. I set this up on a mid-market electronics site last year. The integration required adding the PayPal JavaScript SDK to the storefront, configuring the return URL in the merchant dashboard, and handling the capture webhook properly. Most people skip the webhook part and wonder why their order status shows "pending" even after payment. The SDK communicates with PayPal's servers asynchronously. If you don't listen for the payment capture event and update your internal order management system accordingly, your fulfillment team is flying blind while the money sits in escrow. The real configuration lives in the PayPal developer dashboard. You need a business account in good standing first. From there, you apply for Pay In 4 access through the PayPal Braintree or standard PayPal gateway settings depending on your integration path. Approval usually lands within two to three business days unless your account has recent chargeback ratios above 0.5 percent. That threshold matters more than most merchants realize.
On the frontend, you display the Pay In 4 button alongside your existing payment options. PayPal provides the UI components, but styling them to match your brand requires overriding their default CSS classes. Their documentation covers this, though the class names change without notice during routine updates. I keep a snapshot of their DOM structure in a local file so I can reference it when something breaks after a platform update. One thing nobody warns you about involves currency conversion. If your store operates in multiple currencies and you're using PayPal's cross-border settlement, Pay In 4 availability varies by market. It's fully supported in the US, UK, Australia, and Canada. Beyond that, availability drops off sharply. I lost a week chasing an issue where Pay In 4 appeared at checkout for European customers but silently failed on payment submission because the feature wasn't enabled for their region. The error message was vague, which made debugging slower than it needed to be. The reporting side deserves attention too. PayPal's merchant interface separates Pay In 4 transactions from regular payments in some views but not others. When I pulled a quarterly reconciliation, the numbers didn't match my internal records until I realized PayPal was grouping the installment payments under a single transaction ID on the statement. Your accounting software needs to recognize that one order generates four debit events, not four separate orders. Setting up the right mapping in your ERP or QuickBooks export prevents a headaches during tax season.
Conversion impact is where this option actually shows its weight. The store I mentioned saw their average order value climb roughly 30 percent after enabling Pay In 4. Higher ticket items moved from "save for later" to immediate purchase. The catch is that your return rate also tends to increase slightly since customers aren't feeling the full financial pinch upfront. Plan for a higher refund volume and make sure your refund workflow handles partial reversals correctly. Refunding a Pay In 4 order doesn't cancel the remaining installments automatically. The customer still owes the future payments until the refund posts through the entire schedule, which can take up to ten business days depending on their bank. If you're considering this for a subscription or recurring billing model, it won't work. Pay In 4 is strictly for one-time purchases. Attempting to route a subscription through it will fail at the authorization step, and your customer support will field confused calls about why their first payment went through but the second didn't. I learned that the hard way before checking the terms of service thoroughly. The integration itself takes between four and eight hours for a standard checkout flow. Add another two to three hours if you need custom styling or multilingual support. Anything beyond that points to scope creep rather than complexity. Most stores that stretch past a day on this are either rebuilding their entire checkout architecture or trying to maintain legacy code that predates modern API standards.
Get the Full Details
A few practical tips that aren't obvious from the docs. Always test in sandbox mode with at least three different device types before going live. PayPal's approval process for Pay In 4 can reject you based on synthetic data patterns in your sandbox history, so run a complete purchase cycle including refunds before switching to production keys. Also monitor your PayPal dashboard daily during the first two weeks after launch. If you see a spike in "payment failed" notifications, it usually means customers are hitting daily bank withdrawal limits on their installment dates. Push a notification to affected accounts suggesting they adjust their payment method or contact their bank beforehand. The setup is manageable. The ongoing maintenance is the part that catches people off guard. But for the right product mix and customer base, the lift pays for itself within the first month through increased conversion rates alone. Just make sure your backend can handle the installment payment rhythm before you flip the switch.