What Actually Happens When You Click That Button at Checkout
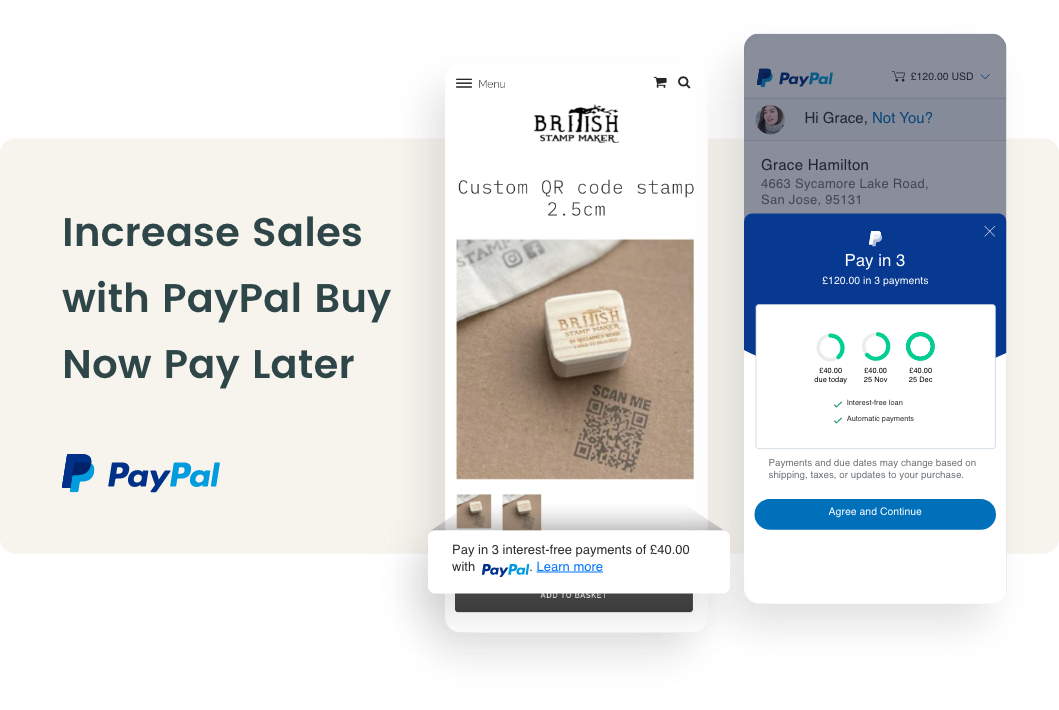
You're halfway through a purchase, the cart is sitting there, and suddenly there's this new option showing up that says you can split the total into four payments. It looks easy because it is easy. I've been running online stores and managing merchant accounts for over a decade now, and the shift from "pay everything upfront" to "just pay a quarter of it now" has changed how people actually spend money. The numbers don't lie — conversion rates at checkout climb noticeably when BNPL shows up as a payment method. PayPal's version of this financing tool is called Pay in 4. It splits your purchase into four equal installments, two weeks apart. The first chunk hits your card or bank account right away when you check out, then the remaining three charge automatically every fourteen days. There's zero interest if you stick to the schedule. That's the part everyone leads with. But here's what the marketing pages won't tell you — the approval isn't guaranteed just because you have a PayPal account. PayPal runs a soft inquiry that checks your credit profile, spending history, and account standing. If you've missed payments on other installment plans, are carrying heavy revolving debt, or your PayPal account is relatively new, the system might deny you even though you have "PayPal" sitting right there in your wallet. I learned this the hard way when a merchant in my supply chain chain tried to use it for a $2,800 equipment purchase and got declined. The message was vague, something about "funding source eligibility," which really just means they don't know exactly why the algorithm said no. You can try a different card, or wait a couple weeks and retry, but there's no appeal process that actually works.
Another thing nobody mentions: late fees. They're capped at 25 percent of the missed installment amount, up to $40 per missed payment depending on your location. So if you forget one of those biweekly charges, you're looking at a $10 fee on a $40 payment. It adds up fast if you're juggling multiple BNPL orders across different retailers. The fees aren't interest, but they function the same way — they punish you for stretching beyond what the system thinks you can handle. For merchants, enabling this option usually means a slightly higher processing fee than standard card transactions. PayPal charges their BNPL rate, which typically runs a percentage point or two above regular checkout processing. Some sellers absorb it because the average order value jumps when customers can spread payments out. Others don't bother offering it because the margin impact eats into thin-ticket sales. If you're trying to use it yourself, here's the practical path. Log into your PayPal account and go to the wallet or payment methods section. There should be a prompt about Pay in 4, or you can find it under "More Payment Options." If you don't see it, your account might not be eligible yet. New accounts with no transaction history often need to build a record first — usually three to five completed purchases before the option unlocks. Once it's available, just select it at checkout on any supported merchant site. The approval decision is instant in most cases, and if you get the green light, you'll see your payment schedule laid out before you confirm the order.
The biggest risk people don't think about is the compounding problem. Say you have a $200 BNPL plan with Nike, a $150 one with a furniture store, and a $300 one with an electronics retailer, all running simultaneously. That's $650 spread across staggered due dates, and if you miss one payment, the late fees stack. PayPal also sends reminders, but they're automated emails that are easy to ignore until the date passes. I've seen people miss a payment because their card on file expired and they never updated it. The charge fails, the fee hits, and now you're scrambling to fix it before it affects your credit score — though PayPal doesn't typically report on-time payments to credit bureaus, missed payments can sometimes show up depending on how they've classified the account. For legitimate budgeting, it works fine if you treat it like a calendar obligation rather than extra spending power. The temptation is real though — that $800 couch suddenly feels like $200, and your brain tricks you into thinking you can handle three more "just $200" purchases. You can't, not really, unless your cash flow is structured to cover all four installments across all your active plans at the same time. If Pay in 4 doesn't work for you, alternatives exist. Klarna and Afterpay offer similar four-payment structures with comparable fee models. Affirm leans more toward longer-term financing with actual interest rates, which is a different product entirely. Some credit cards now offer installment conversion at checkout, which can be cheaper if your rate is low enough. The right choice depends on whether you want zero-interest flexibility or a structured repayment plan with transparency about costs.
Get the Full Details


?$ResponsivePreset$ "BenQ Buy Now Pay Later with PayPal | BenQ US")