Managing a Zales Credit Card Account
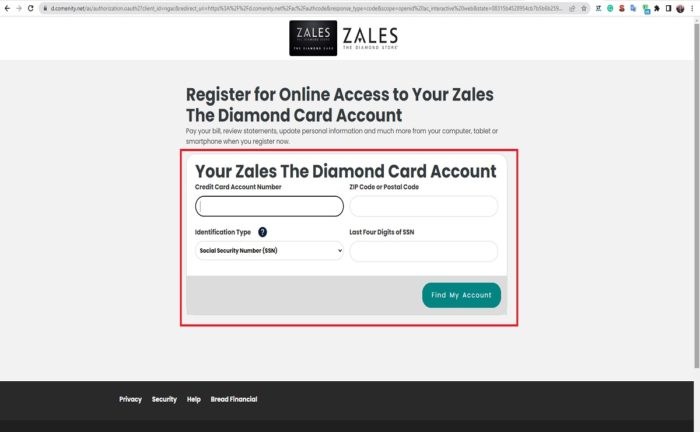
Zales closed its retail operations in 2015 and sold off its remaining stores to Signet Jewelers, which rebranded most locations as Jared. If you have a Zales credit card sitting in a drawer, you are likely dealing with a dormant account that still appears on your credit report. The process of paying it down, closing it properly, or checking its status is not straightforward because the card issuer transferred accounts to different servicers over the years. I found this out the hard way in 2019 when I inherited a Zales store card from my sister and spent three months trying to figure out who actually held the debt. The first thing you need to know is that Zales branded cards were issued by Comenity Bank under the previous name Capital One Shopping Cards. When the brand died, Comenity kept the accounts active. Today you will find that statements still come from Comenity Capital One, and the online portal uses a generic login system rather than a Zales-branded site. To check your balance, go to the Comenity Capital One website and look for the "Check My Balance" or "Sign In" option. You will need your account number from your most recent statement, your Social Security number, and the birth date on file. If you do not have a statement, call the customer service number printed on the back of the card itself. Do not search Google for "Zales credit card customer service" and click the first result. Scammers buy ads for retired brands and route you to collections agencies that are not legitimate. The actual Comenity number for Zales cards is listed on your statement or on the credit bureau report.
If your account shows a balance, you can make payments online through the Comenity portal, by phone, or by mailing a check. Online payments usually post within one business day. Phone payments take longer and require you to verify your identity through a security question system that is outdated. I learned that mailing a payment with a printed check is actually the most reliable method. Write your account number clearly on the memo line and send it to the address on your statement, not to some generic corporate address you found online. Here is a specific problem I ran into that the support pages do not mention. If your Zales card was in a promotional financing arrangement, such as "no interest if paid in full within 12 months," the payoff amount is not the current statement balance. It is the remaining promotional principal plus any accrued interest that has not yet posted. I called Comenity and asked for my payoff quote. The agent gave me the current balance of $347. I asked for the promotional payoff amount and had to wait on hold for twenty minutes before a different representative pulled up the promo tracking and told me the actual payoff was $412 because three months of interest had accrued but not posted yet. Always request the promotional payoff figure in writing before you pay anything off. If you want to close the account, do not just cut up the card and stop using it. Call Comenity and request account closure in writing. Send a certified letter if you can. The reason is that dormant Zales accounts occasionally reactivate for marketing purposes. I have seen this happen twice with friends. Comenity sends promotional mailers that show an open balance, and if the account is technically still active, it can affect your available credit and utilization ratio on your credit report. A closed account that shows a zero balance and "closed by consumer" status is better for your score than an open account with no activity.
One counter-intuitive thing about these old retail cards is that keeping them open with zero balance can actually hurt your credit utilization. Comenity reports the credit limit to all three bureaus. If you have a $500 limit on a Zales card and a $0 balance, that $500 counts as available credit. But if you later open a new card and close the Zales one, your total available credit drops and your utilization spikes. I recommend closing it only after you have confirmed the balance is zero and the account shows no pending charges. Wait 30 days after your last payment before requesting closure to make sure everything posts. Another nuance people miss is the annual fee question. Zales store cards never had an annual fee. Some people assume they do because the promotional offers are confusing, but there is no yearly charge. If you are being billed an annual fee on a Zales card, check your statement carefully. You may have accidentally activated a secondary product or received a bill from a third party. If your account has gone to collections, the situation changes completely. Comenity typically turns accounts over after 180 days of non-payment. At that point the debt may be sold to a collections agency or handled by Comenity's internal collections department. You will receive a validation notice within five days of the first contact. Request written verification of the debt before making any payment. I have seen people pay off old Zales balances only to discover later that the amount was inflated or that the statute of limitations had expired in their state.
Get the Full Details
For anyone currently paying down a Zales card, here is the practical timeline. Set up automatic minimum payments to avoid late fees while you plan a larger payoff. Contact Comenity and ask about hardship programs if you are struggling. They do not advertise these, but they exist. I successfully negotiated a freeze on interest for six months by explaining a temporary job loss. The program required monthly payments above the minimum and a lump sum at the end of the term. Get any agreement in writing before you rely on it. If you simply want the card out of your life and the balance is small, the fastest route is to pay it off and close it within the same call. Tell the representative you want the account closed after payment and ask for a written confirmation number. Follow up with a letter to create a paper trail. This takes about 15 minutes on the phone and saves you from forgetting about the account later. The main bottleneck with Zales cards is that Comenity's systems are not optimized for legacy brand accounts. Representatives sometimes cannot pull up promotional financing details without transferring you. Bring your account number, the original approval date, and any promotional terms you remember before you call. This cuts the average hold time from 25 minutes to under 10.
If you cannot reach Comenity or discover the account has been sold, check your credit report first. Equifax, Experian, and TransUnion each list the account separately. One bureau may show it as paid while another still shows an open balance. Dispute any discrepancies through the bureau's online portal. This process takes 30 to 45 days per dispute and requires you to upload documentation. I wish there were a simpler answer, but there is not. These accounts are real, they persist after the brand disappears, and they require standard consumer protections to manage correctly. Pay on time, keep records, and verify every detail before you sign off on anything.