Figuring Out Your Tennessee Paycheck Without the Headaches
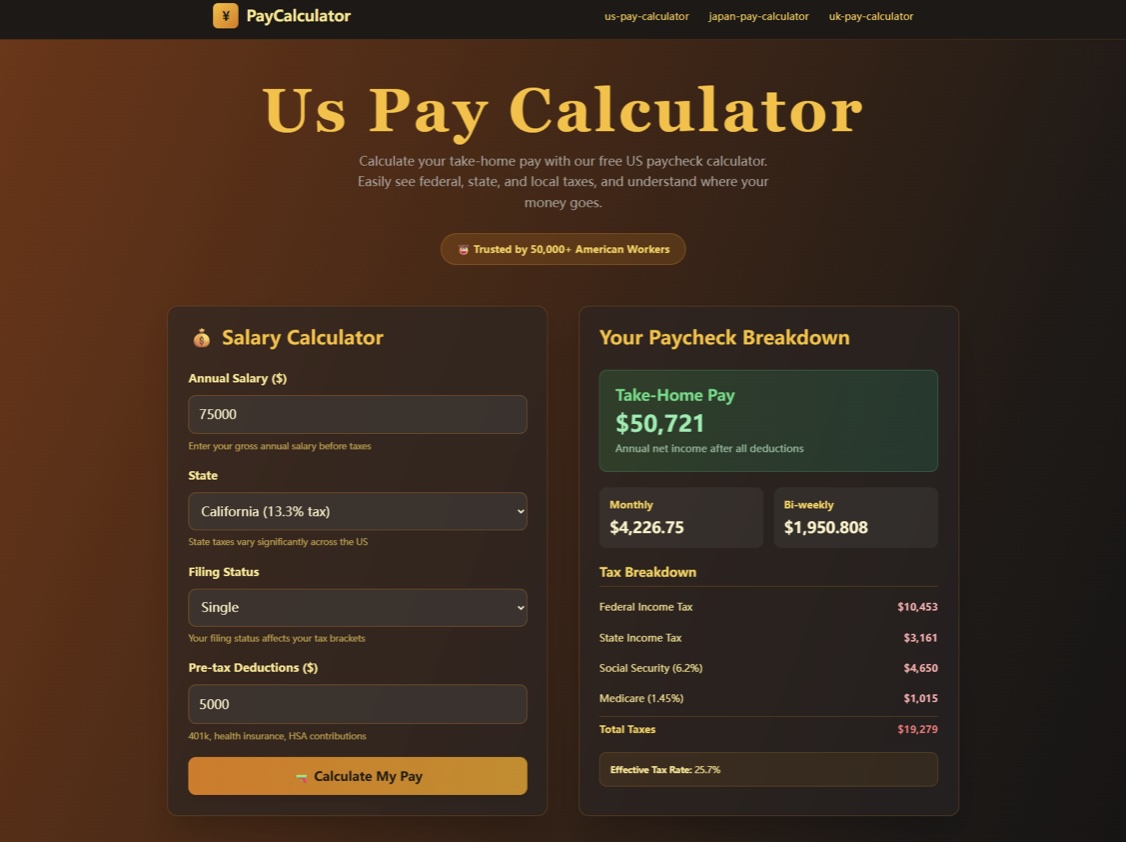
I spent three years doing payroll for a small construction crew in Nashville before switching to consulting. The first time someone asked me what they would actually take home from a $42,000 salary in Tennessee, I had to open a spreadsheet and start calculating from scratch. That took about 45 minutes. Now I use a tool that gives me the answer in under a minute. The difference is not philosophical, it is practical. The short version is that Tennessee does not have a state income tax on wages. That single fact makes the calculation simpler than almost anywhere else in the country. You still have federal withholding, Social Security, Medicare, and whatever voluntary deductions your employer offers. But the absence of a state-level tax means fewer moving parts and less room for error when you are trying to estimate your net pay. Most online calculators handle this by letting you enter your gross pay, filing status, and any pre-tax deductions. The tool then applies the current federal tax brackets and FICA rates to produce a monthly or annual take-home figure. Some also factor in local taxes if you live in a municipality that imposes one, though those are rare in Tennessee.
Here is something most people miss. A paycheck calculator will show you the statutory withholding, but it will not tell you whether your actual take-home pay will match that number. The reason is that many employers use supplemental wage withholding methods that differ from what the calculator assumes. If you have a side gig or receive bonuses, the IRS requires a flat 22 percent federal rate on supplemental income. A basic calculator will not always reflect this unless you explicitly account for it. I learned this the hard way in 2019. A client came to me after he received a $5,000 bonus and was shocked that only $3,200 hit his account. He had run the bonus through a standard calculator that applied the regular graduated bracket logic. The employer, following IRS rules for supplemental wages, withheld at the flat 22 percent rate. The calculator result was wrong because it did not know which withholding method his payroll system would use. The workaround was simple: I asked his payroll department which method they applied to bonuses, then adjusted the calculator inputs to match. That took five minutes and saved him from an unpleasant surprise at tax time. The most useful calculators let you toggle between wage types. Look for one that distinguishes between regular earnings and supplemental income. If it does not, you can manually adjust by applying the 22 percent flat rate to any bonus, commission, or overtime that your employer treats as supplemental.
Another nuance involves the standard deduction versus itemizing. Tennessee residents do not file a state return for income tax, but they still file a federal return. If your calculator does not let you choose between the standard deduction and itemizing, it will default to the standard amount. For 2024, that is $14,600 for single filers and $29,200 for married filing jointly. If you have significant mortgage interest or charitable contributions, itemizing could lower your taxable income more. A good calculator will let you switch between these options. I ran into a case last year where a client had $18,000 in mortgage interest and was getting a smaller refund than expected. His calculator defaulted to the standard deduction. Once we switched to itemized, his taxable income dropped by about $3,400, which shaved roughly $680 off his federal tax liability. The calculator itself was not broken, it just lacked the flexibility to model his actual situation. I recommended he use the IRS Deduction Estimator alongside his paycheck calculator to cross-check the numbers. Voluntary deductions are where things get tricky. Health insurance premiums, retirement contributions, and flexible spending accounts all reduce your taxable wages, but the timing varies. Some employers deduct health insurance before calculating taxes, while others deduct it after. A calculator that does not ask about your specific benefit elections will produce an approximate figure at best.
Get the Full Details
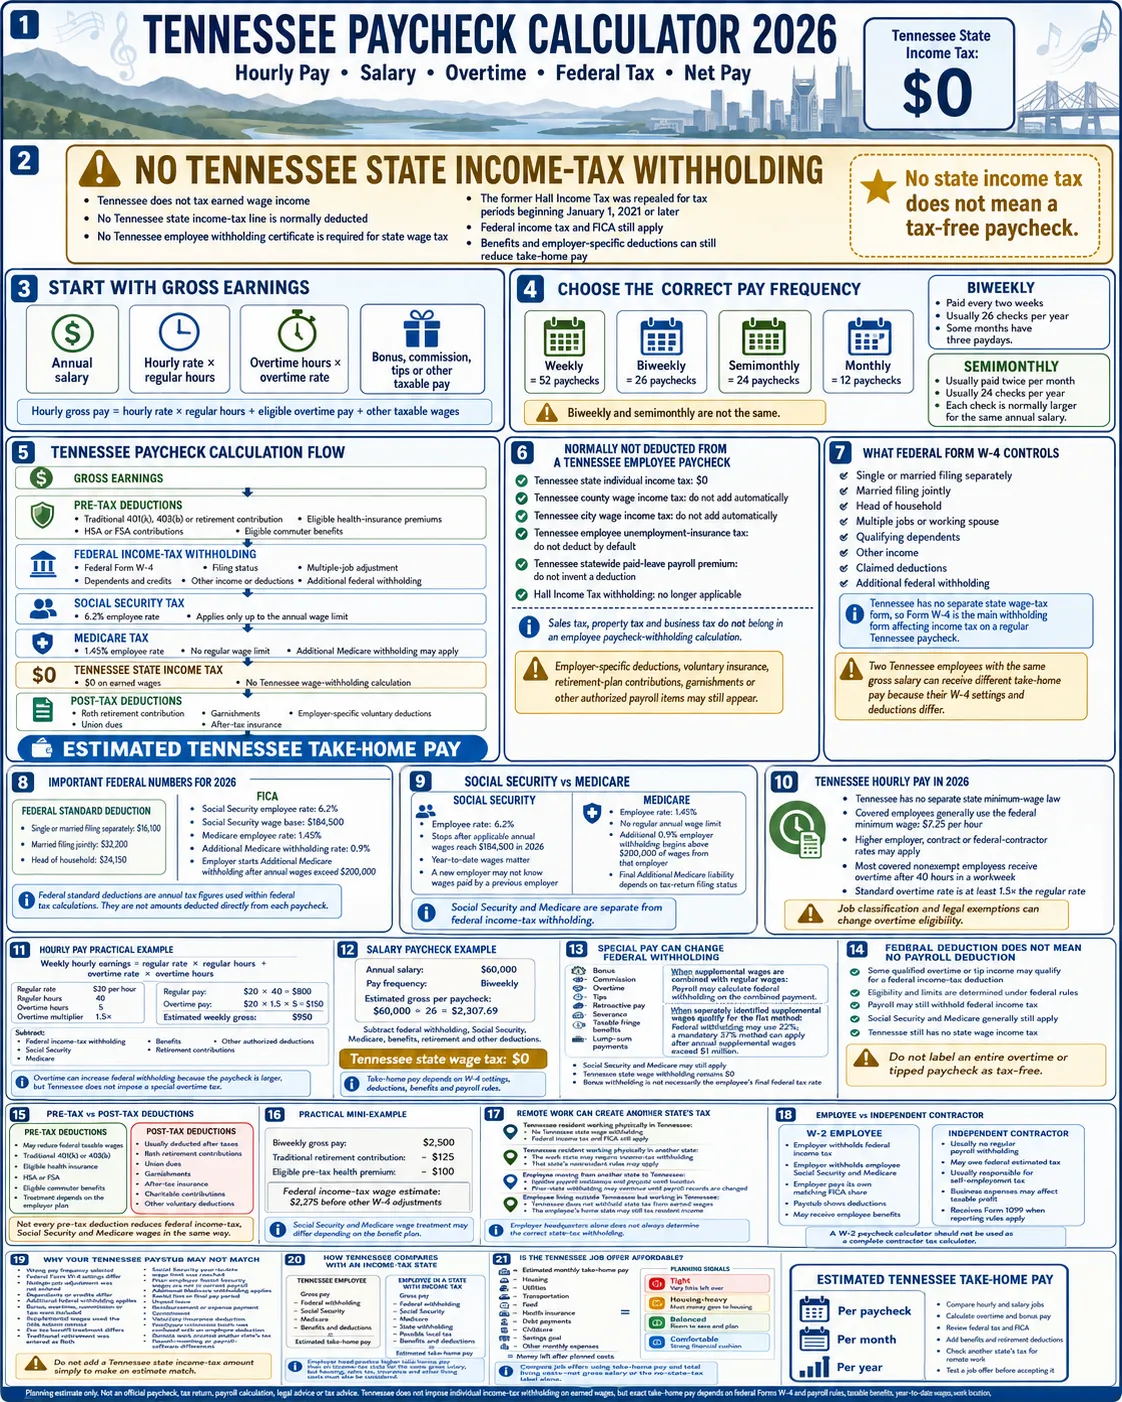
The most reliable approach is to log into your employer’s payroll portal and pull your most recent pay stub. Use the actual withholding amounts as a baseline, then run the calculator with your planned changes, like increasing your 401(k) contribution or adding a dependent to your health plan. This way you are not guessing, you are modeling based on real data from your own pay history. If you are self-employed in Tennessee, the calculator is less useful. You owe self-employment tax, which covers both the employer and employee portions of Social Security and Medicare. That is 15.3 percent on net earnings from self-employment. Most paycheck calculators assume you are a W-2 employee and will not include this. I use a separate SE tax worksheet for my own business and only reference the paycheck calculator for client employees who want a quick estimate of their net pay. The downside of relying on a paycheck calculator is that it cannot predict changes to tax law or your personal circumstances. If Congress changes the standard deduction or you get a raise mid-year, the calculator will not auto-adjust. You have to re-enter your new numbers manually. I keep a running spreadsheet with my actual withholding data and update it quarterly. This takes about 10 minutes per quarter but ensures my estimates stay accurate when clients ask for projections.
For most Tennessee residents making a steady salary, a free online paycheck calculator will give you a reasonable estimate within a few percent. The key is understanding what the calculator does and does not include, then adjusting for your specific situation. If you need precision, like when you are evaluating a job offer or planning a major purchase, I recommend running the calculator three times with different scenarios, then comparing the results to your actual pay stubs over the past year.