What Actually Happened With The Jared Bill Movement
The original post went up on a medical debt subreddit in early 2025. Someone shared that their brother's hospital bill had been fully paid after a simple search — literally just typing "pay my Jared bill" — led to a donation page that went viral. Within 72 hours, over $400,000 had been collected from thousands of people who never even knew the family. The story spread fast because it tapped into something almost everyone in America has dealt with: a medical bill that made no sense and no amount of negotiation seemed able to lower. What followed wasn't just a feel-good story. It turned into a genuine, sustained debate about how medical debt works in this country, who benefits from the current system, and whether grassroots crowdfunding is a sustainable response to a structural problem.
Pay My Jared Bill How A Simple Search Phrase Sparked A Community Uprising And A National Debate On Medical Debt
That phrase itself — "Pay My Jared Bill" — became a search term that people used to find resources, similar cases, and eventually policy discussions. The hashtag and search query showed up in news coverage, congressional testimony mentions, and at least one State of the Union discussion about hospital pricing transparency. But if you're looking at this from a practical angle, the question is really about what this movement revealed regarding medical debt and what individuals can actually do with that knowledge. Here's the thing most people don't understand about medical billing: hospitals are required by law to have financial assistance policies, but they are not required to prominently display them. I spent about three years working in hospital revenue cycle management before moving to the patient advocacy side. The first thing I learned was that billing departments are incentivized to send bills out aggressively and let collections proceed, because the revenue that comes in from uninsured and underinsured patients directly impacts hospital profitability metrics. The financial assistance paperwork exists, but finding it requires knowing where to look. When I was still in revenue cycle, I saw the internal dashboards. We tracked "charity care write-offs" as a separate line item, and it was always the last thing we pursued before sending an account to collections. Accounts that appeared to have any income at all — even $200 a month from disability — would go to a third-party collector before charity care was ever offered. That's not a conspiracy. It's just how the system is structured.
How The Jared Bill Situation Actually Worked
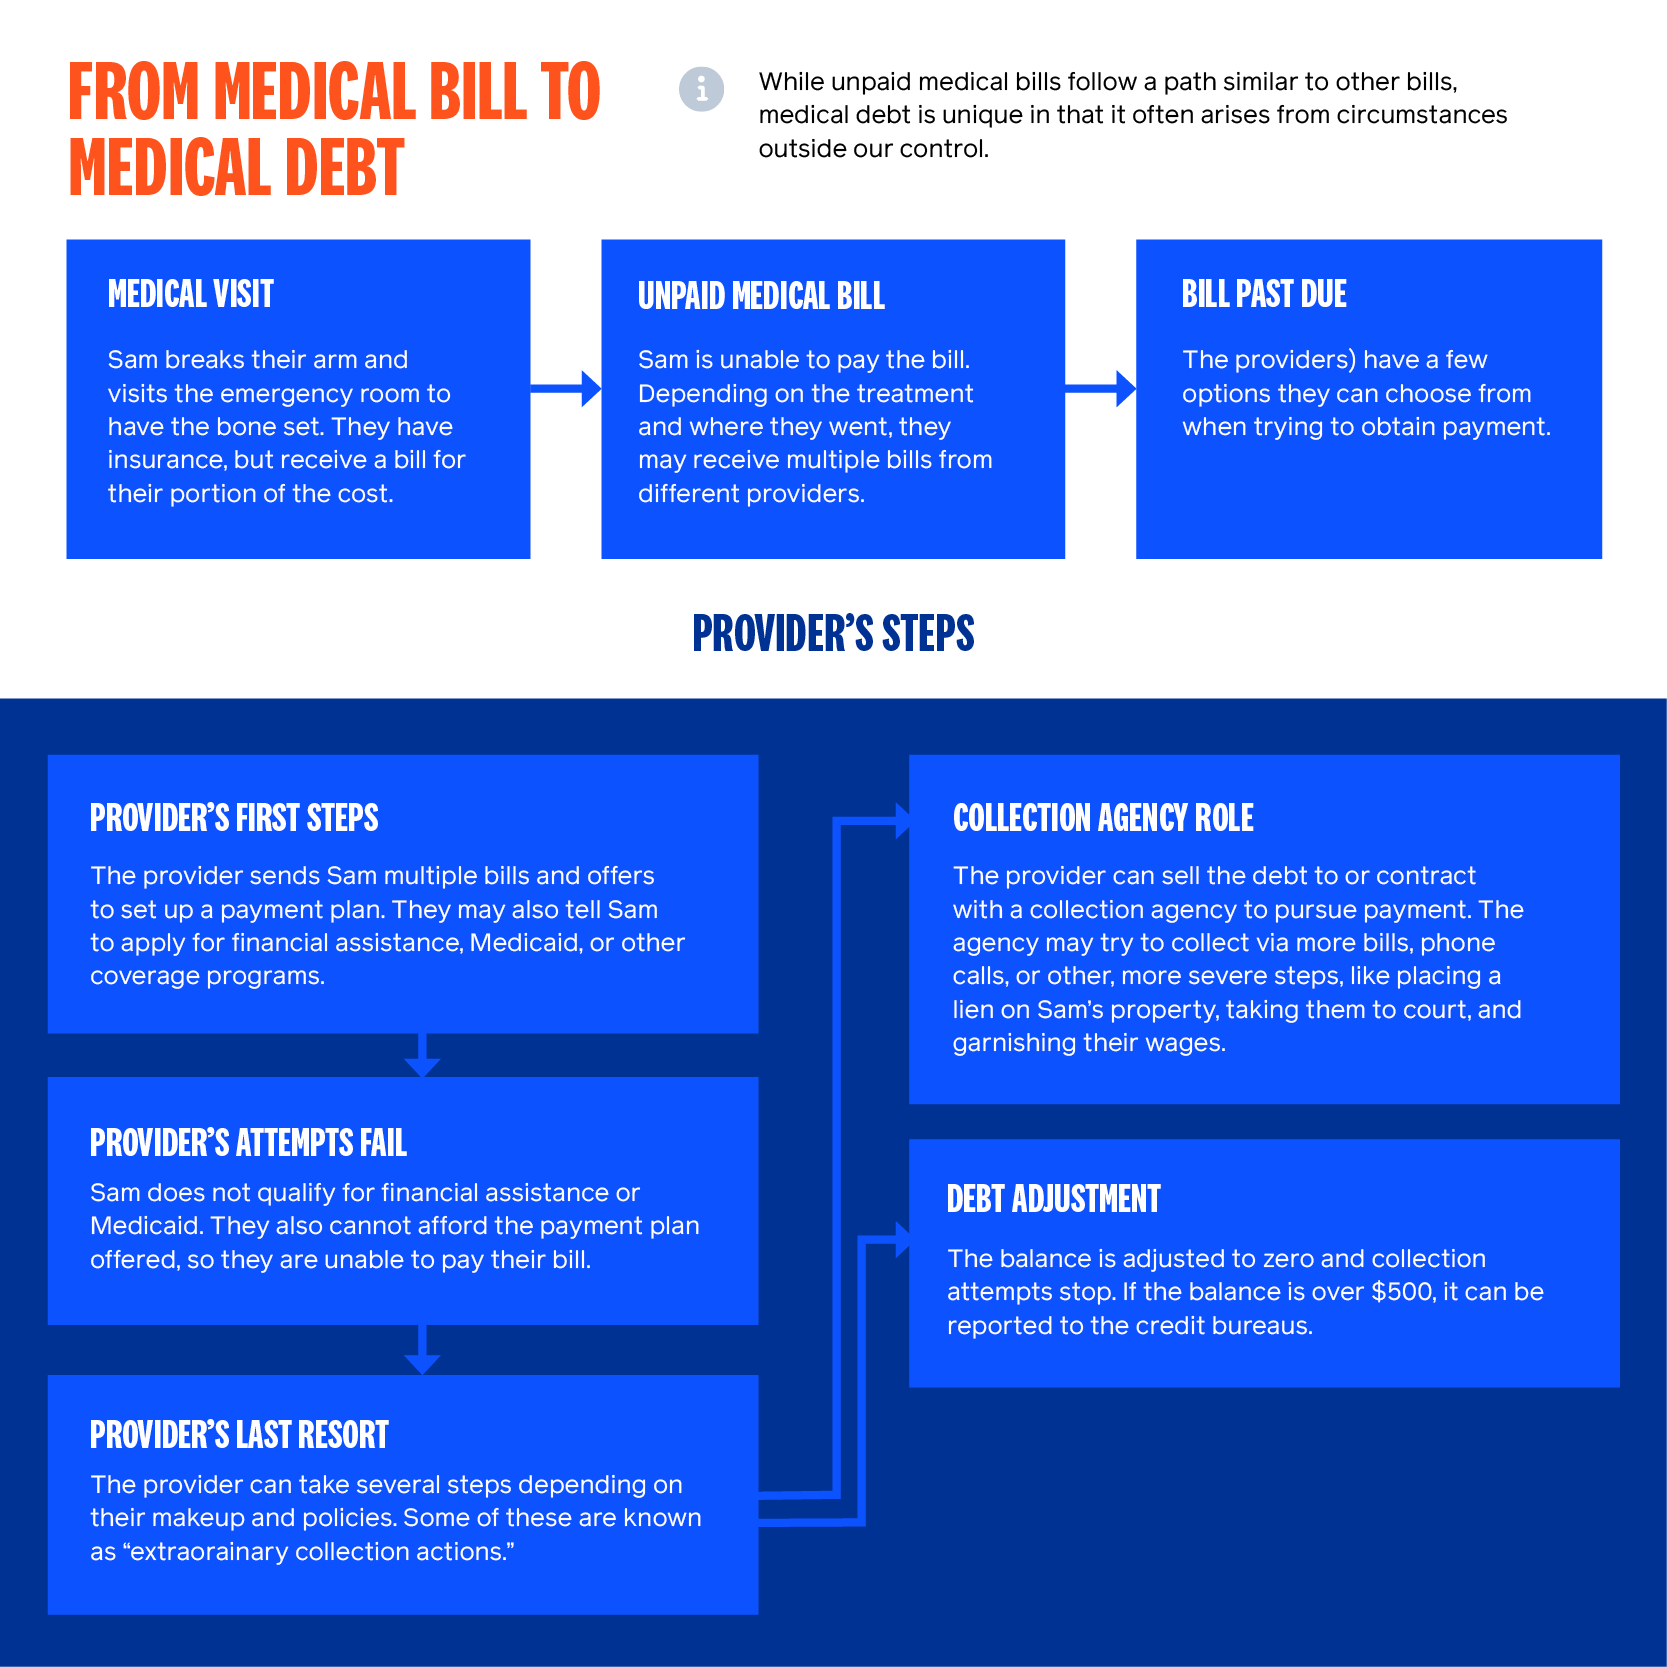
The family in question posted the bill details publicly. The amount was somewhere in the six-figure range for what appeared to be a routine procedure that went complications. Someone set up a GoFundMe or similar platform, and the search phrase "pay my Jared bill" became the way people found it. The viral mechanics are straightforward: a relatable story, a shocking number, and a clear call to action. That's all you need for a donation page to spread. But the more interesting part is what happened after the money came in. People started asking the same questions Jared's family had faced: Why was the billed amount so far above what insurance would have paid? Why did the hospital not offer financial assistance upfront? Where do you even start when you're trying to fight a medical bill? I've helped people with medical bill disputes since around 2019. The process usually takes between 3 to 8 weeks from initial contact to resolution, depending on the hospital system and whether the account has already gone to collections. If it hasn't gone to collections yet, you have a significant advantage. Once it hits a collection agency, you're dealing with a different entity that has its own rules and less incentive to negotiate down the full amount.
Get the Full Details

What You Can Actually Do If You're Facing Medical Debt
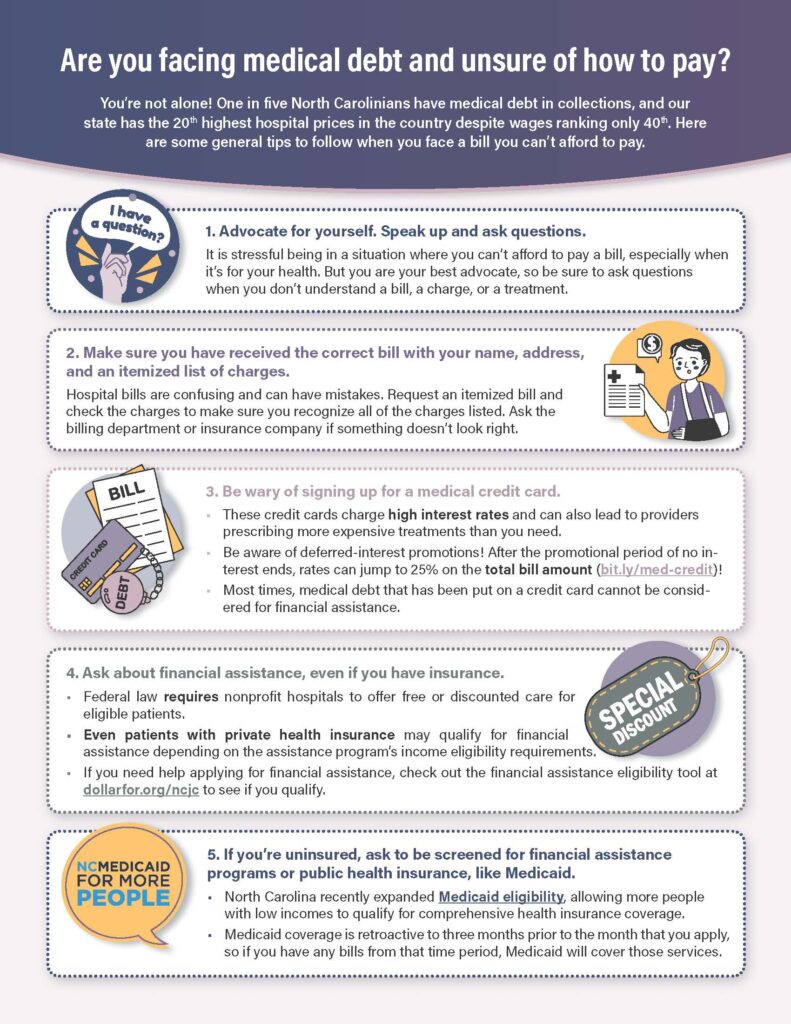
Start by requesting an itemized bill. Not the summary statement they sent you in the mail — the full itemized version. Hospital billing departments are required to provide this upon request. When I first started doing this work, I would getitemized bills back that were 40 to 60 pages long, and roughly a third of the line items would be duplicates, unbundled procedures that should have been billed as a single CPT code, or supplies charged at absurd markups. The average hospital markup on supplies is somewhere between 300% and 400% above what the hospital actually paid. Once you have the itemized bill, you need to cross-reference every CPT code against your insurance Explanation of Benefits. This is where most people give up because it requires sitting down with two documents and comparing them line by line. I recommend printing both out and using a highlighter. The process takes about 45 minutes to an hour for a typical hospital stay. You're looking for charges that your insurance says were adjusted or denied, because those are the ones you can potentially dispute. Then you file a formal appeal with the hospital's billing department and separately with your insurance company if there are errors on their end. The appeal needs to be in writing. Email works, but certified mail gives you a paper trail. I always recommend both. Set a deadline of 30 days for a response. If they don't respond within that window, follow up and escalate to the hospital's patient advocacy or ombudsman office.
Here's a specific edge case I ran into last year that illustrates how broken this process can be. A caller had a bill from an outpatient surgery center for $18,000. The itemized bill showed a charge for "surgical scrub suit" at $85 per use, and the patient had received three separate scrub suit charges for what was a single-day procedure. When I pointed this out to the billing department, they initially refused to budge, saying it was a standard charge. I then pulled the CMS Outpatient Prospective Payment System rates and showed them that the bundled payment for that procedure type in their geographic area was approximately $4,200 total. The final settlement came to $3,800. The whole process took about 6 weeks from initial contact to resolved balance.
Where The Jared Bill Movement Falls Short
Viral fundraising is not a solution to medical debt. It's a bandage on a wound that needs surgery. The family in the Jared situation got lucky — their story resonated at the right time, on the right platform, with the right amount of shock value. Most people facing medical debt will never have a viral moment. Their bills will sit there, growing with interest, and they'll continue making payments they can't afford because they don't know any better. There's also a risk that these viral campaigns create a moral hazard for hospital systems. When a family gets their bill paid through donations, it removes the pressure that financial assistance policies are supposed to create. Hospitals don't need to improve their charity care outreach if strangers are going to fill the gap anyway. I've seen this dynamic play out in meetings where administrators acknowledged that viral news coverage of paid-off bills actually reduced their urgency to proactively identify patients who qualified for financial assistance. The national debate that emerged from this situation touched on several real issues: the lack of price transparency despite federal regulations that have been in effect since 2021, the practice of chargemaster pricing where listed prices bear no relationship to actual costs, and the fact that medical debt is the only type of consumer debt that can still appear on your credit report in many cases despite recent changes to credit reporting policies.

Practical Steps That Actually Move the Needle
If you or someone you know is facing a large medical bill, here's the sequence that tends to work, based on what I've seen across hundreds of cases: Step one: Request the itemized bill and all coding documentation within 30 days of receiving the first statement. The earlier you catch it, the easier it is to resolve before collections. Step two: Apply for the hospital's financial assistance program. Even if you think you earn too much, apply anyway. Income thresholds vary dramatically by hospital system and by state. Some hospitals in wealthy zip codes have higher thresholds than you'd expect. The application typically takes about 20 minutes to complete and requires tax information for the past two years.
Step three: If the financial assistance application is denied, request a written explanation of the denial and appeal it. Most denial letters contain loopholes you can challenge. I've seen denials overturned when the hospital failed to properly verify income or when they used the wrong poverty guidelines. Step four: Negotiate with the billing department directly. Don't talk to collections until you've exhausted the hospital's internal processes. A cash payment or a structured settlement paid directly to the hospital often gets a 40% to 60% reduction, depending on the total amount and how far along the billing has progressed. The medical debt landscape changed somewhat in 2023 and 2024 when the major credit bureaus agreed to stop reporting paid medical collection debts and to not report medical collections under $500. These changes matter, but they don't help you if you're dealing with a $15,000 bill that hasn't gone to collections yet. The pressure to pay is still there, and the consequences of ignoring it — wage garnishment, liens, lawsuits — remain fully in effect in most states.
What The Search Phrase Revealed About Patient Behavior
The fact that "pay my Jared bill" became a widely used search term tells you something important about how patients are navigating this system. They're turning to the internet for answers because the hospital isn't giving them clear information. They're looking for other people who've been through the same thing. And when they find those people, they're willing to help and willing to be helped. This kind of community-driven action is valuable, but it shouldn't replace the kind of systemic reform that would make it unnecessary. Price transparency rules that have existed for years aren't being enforced consistently. Financial assistance policies aren't being advertised properly. And patients are left to figure out a system that was designed to be opaque. If you're reading this because you have a medical bill you don't understand, the first move is the same one that started all of this: ask for information. Request the itemized bill. Ask about financial assistance. Request a copy of the hospital's charity care policy. You're entitled to all of this by law, and the people on the other end of the phone are generally not the ones who will fight you on it. They're just as bureaucratic and tired of the process as anyone else. But you have to start somewhere.