Managing Your Amazon Store Card Without Losing Your Mind
Most people sign up for the Amazon Store Card without really reading what they're getting into. I've seen it dozens of times. The application takes thirty seconds on mobile, and the approval is nearly instantaneous. Then the statements start arriving, and suddenly you're confused about billing cycles, deferred interest, and why your APR jumped from 0% to something closer to 29% overnight. The Amazon Store Card comes in two flavors: the RedCard (which gives you 5% back on everything) and the Store Card (which offers promotional financing like 6 or 12 months special financing on purchases over a certain amount). They're administered by Synchrony Bank. Understanding which one you have matters because the rules are completely different.
Pay My Amazon Store Card The Ultimate Guide To Managing Your Amazon Credit
To pay your Amazon Store Card, you log into your Amazon account, navigate to the Payment Options section, and select your card. From there you can set up automatic payments or make a one-time payment. The minimum payment is either $35 or 1% of your balance, whichever is greater. That's not a typo. If you have $500 in charges, your minimum could be just $5. Here's the thing nobody warns you about: making only the minimum payment on a Store Card with promotional financing is catastrophic if you don't track the promo end date. I learned this the hard way in 2019. I bought a $1,200 laptop using the 12-month special financing offer. I paid the minimum every month because I was cash-strapped after moving apartments. The promo period ended. The remaining balance of $847 got hit with retroactive interest at the standard APR of 27.99%. I owe you about $230 in interest on that one transaction alone. It took me eight months to stop talking about it with my therapist.
How Promotional Financing Actually Works
When Amazon advertises "6 months special financing on purchases of $149 or more," they mean it literally. If you pay off the entire purchase amount within six billing cycles, no interest is charged. But here's where people screw up: "special financing" doesn't apply to your entire balance. It only applies to the specific purchase that qualified for the offer. If you already had a $200 balance and then made a $149 purchase, only that $149 gets the promo rate. The old balance sits there at the standard variable APR, which was around 26.99% last I checked. Another trap: if you miss a single payment during the promotional period, even by one day, the deferment of interest is revoked. The interest accrues retroactively from the original purchase date. This is called "deferred interest," and it's different from "no interest." No interest means you only pay interest on what you carry over. Deferred interest means you pay zero interest as long as you clear the balance, but if you don't, they charge you interest on the full amount from day one.
Get the Full Details

Payment Strategies That Actually Work
The best approach depends on whether you're carrying a promo balance or running your regular purchases through the card. If you're using the card for everyday spending and paying it off monthly, the RedCard version is straightforward. Five percent cash back with no annual fee is genuinely good if you shop on Amazon regularly. Set up automatic payments for the full statement balance. Never pay less than the full amount unless you're intentionally carrying a balance, which is a terrible idea at 26%+ APR. If you're using the Store Card for larger purchases with promotional financing, set a calendar reminder for two weeks before the promo period ends. I use a recurring note in Google Calendar that says "Pay off Amazon Store Card promo" with the date circled. When the reminder fires, log in and pay the remaining promo balance in full. Don't wait for the statement to arrive. Check your balance directly in your Amazon account to see exactly what's left.
Common Problems and Workarounds
Synchrony's customer service is notoriously difficult to reach by phone. Wait times regularly exceed 45 minutes. The chat feature on their website is more reliable but sometimes disconnects mid-conversation. My workaround is to call right at 8 AM Eastern on a Tuesday. The lines open at 8, and you're hitting the queue before the lunchtime surge. Another issue: automatic payments sometimes fail if your linked bank account has insufficient funds or if there's a hold on the account. I had this happen twice in one year. The solution is to enroll in auto-pay but also set up a notification so you know when a payment processes. Amazon will notify you via email when your autopay succeeds. If it fails, you'll get a separate error notification. Check both inboxes regularly.
When to Walk Away
The Amazon Store Card is not a good financial product if you have a history of missing payments or carrying high balances month to month. The penalties for missing payments during promotional periods are severe. If you're the type of person who forgets billing dates or regularly spends beyond your means, this card will punish you. A regular debit card or a no-frills cashback card with an intro 0% APR period and no annual fee is a better choice. The card also doesn't build credit well if you're already carrying a high utilization ratio. Amazon reports your balance to all three major bureaus. If you're using 80% of your limit every month, your score takes a hit regardless of whether you pay on time. Keep utilization below 30% and the card is fine. Above that, you're actively damaging your credit profile.
What the Statements Actually Tell You
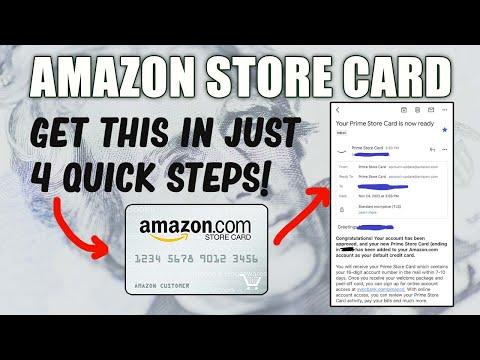
Your monthly Amazon Store Card statement has several line items that confuse people. There's your purchases, your payments, any fees, and your interest charges. The "new balance" is the total you owe. The "minimum payment due" is what you need to pay by the due date to avoid a late fee. The "statement closing date" is when your billing cycle ends and your balance is calculated. Pay attention to these dates. They're not arbitrary. If you see a charge labeled "purchase adjustment" or "balance transfer adjustment," it means Synchrony modified your balance for some reason. This could be a price adjustment from Amazon, a return that posted late, or a fee adjustment. Call customer service if you see an adjustment you don't recognize. Don't just assume it's an error and move on. I once missed a $40 price adjustment because I didn't read the statement carefully. Took three calls and two weeks to get it resolved.