Understanding Online License Payment Platforms
There are plenty of ways to pay for software licenses, digital subscriptions, and professional services online these days. The landscape has shifted significantly over the last few years. What used to require emailing a sales team and waiting three business days for a wire confirmation now happens in minutes through automated checkout systems. I have watched this transition up close from the inside. The core mechanism is straightforward. You select a product or service, enter your payment details, and the system processes the transaction through a payment gateway. The gateway communicates with your bank or card issuer, verifies funds, and returns an authorization code. Once approved, the license key or subscription activation is delivered—usually via email or directly within the application. This entire flow typically completes in under thirty seconds for standard card payments.
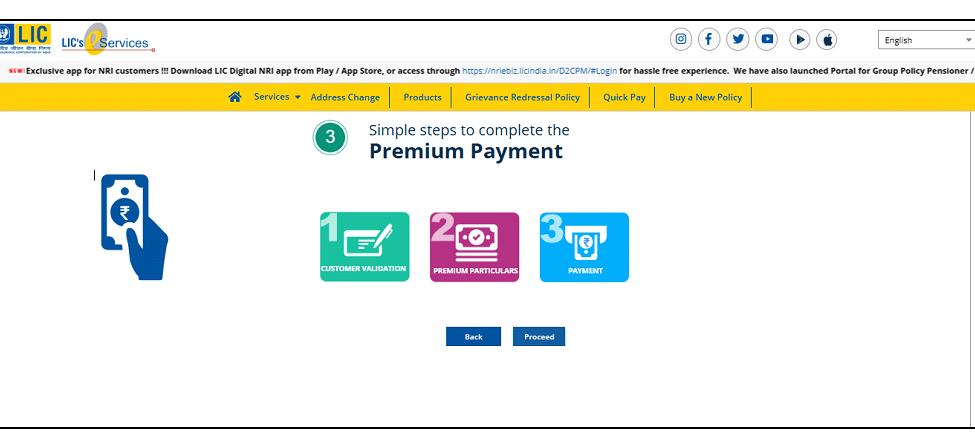
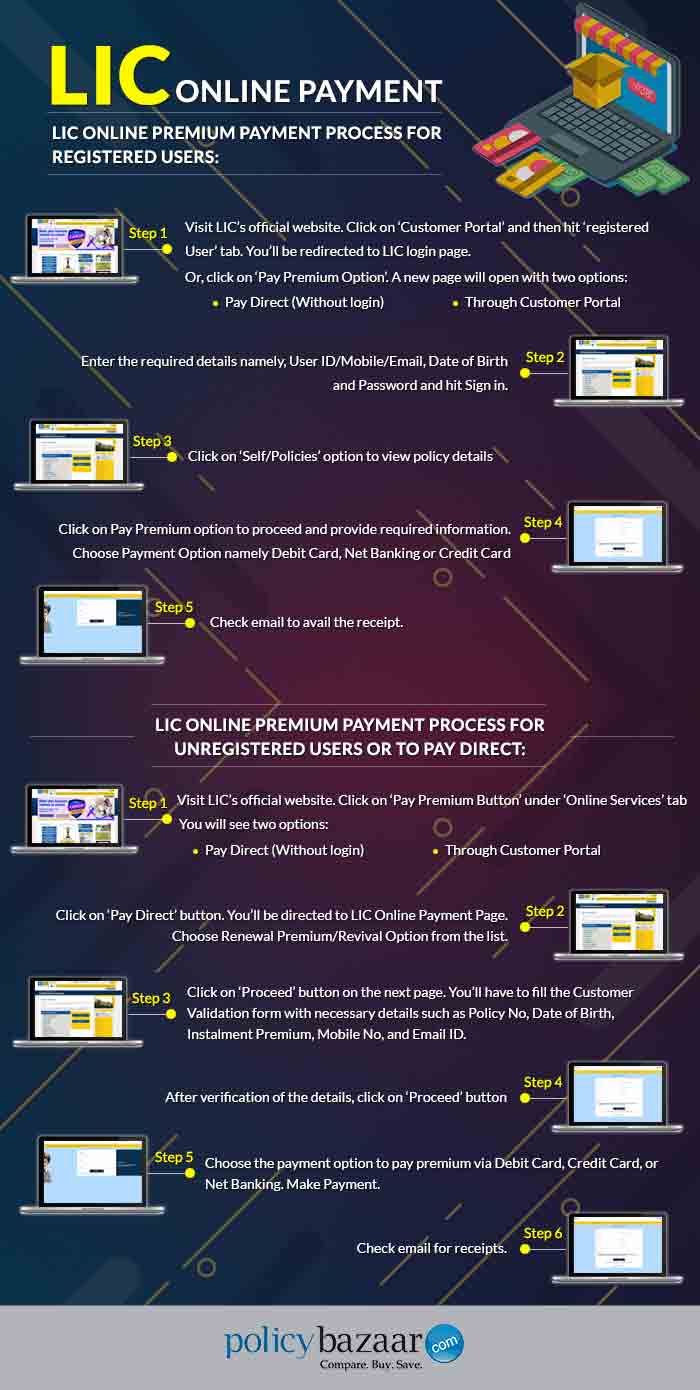
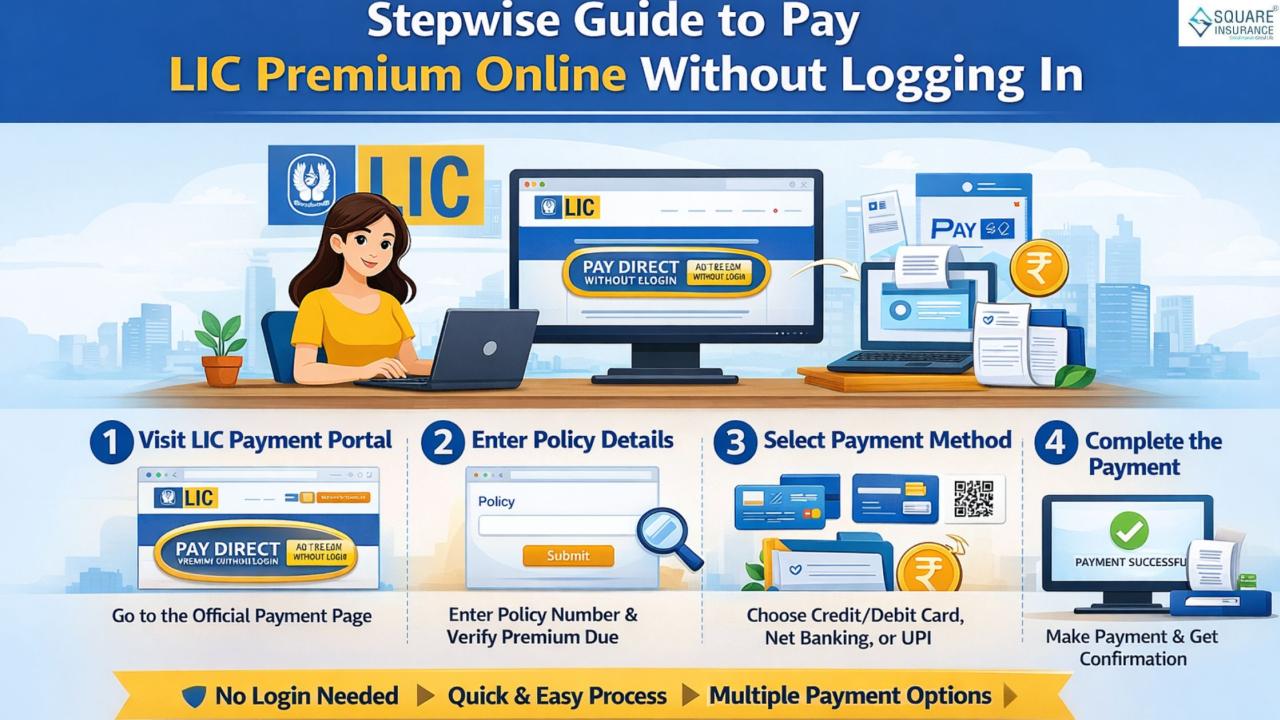
Pay Lic Premium Online A Quick And Easy Guide Secure Instant Professional
When I first started dealing with enterprise license procurement, I used a platform that billed itself as a premium online payment solution for professional licenses. The interface was clean enough. You uploaded your invoice, entered company details, and selected a payment method. The system supported major credit cards, ACH transfers, and sometimes cryptocurrency for international clients. My first transaction went through without issues, but that changed when I tried to pay for a multi-year subscription renewal. The system accepted my payment, generated a receipt, but never activated the license. I spent four hours on hold before discovering that the platform had a known bug with recurring payment triggers—specifically, second-year subscriptions over two thousand dollars required manual approval that was not happening during peak processing windows. The workaround was simple once I figured it out: split the payment into two separate transactions, one per year, and include the purchase order number in the comments field. That triggered an automatic review cycle instead of falling into the manual approval black hole. This kind of edge case does not make it into most guides. Most vendors assume you will hit the activation wall and blame themselves for doing something wrong. The reality is that payment platforms have limits, routing quirks, and approval thresholds baked into their backend logic that are rarely documented anywhere accessible.
Here is how the process actually works on the practical side. First, verify that the platform supports your specific payment type before committing. Some systems process one-click card payments instantly but routeACH transfers through a secondary settlement queue that adds two to four business days. If you need immediate license activation for a project deadline, sticking to credit card payments is the safest route even if you absorb the processing fee, which typically runs between two and three percent of the transaction amount. Second, always capture the transaction ID and the full receipt immediately after payment. Do not rely on the confirmation email arriving within minutes. I have seen cases where the email delivery was delayed by up to six hours due to spam filtering on the vendor side. Having the transaction ID means you can call support and resolve discrepancies without waiting for paper trails to materialize.
Get the Full Details
Common Pitfalls and How to Avoid Them
Payment rejections are the most frequent issue users encounter, and they are usually caused by one of three things. The billing address on file with your card issuer does not exactly match the address entered during checkout. Even a minor mismatch—like using "St." instead of "Street"—can trigger a fraud check that declines the transaction. The second cause is hitting a daily or per-transaction limit on your card. Corporate cards especially have tight limits that trip people up when purchasing annual subscriptions. The third cause is the payment gateway flagging the merchant category code as suspicious. Some platforms route license payments through codes that certain banks consider high-risk. If your payment gets declined, do not simply retry it repeatedly. Each failed attempt adds to the fraud score associated with your account and makes subsequent attempts less likely to succeed. Instead, contact your card issuer first to confirm the card is cleared for online international transactions if applicable, then try the payment again with a slightly modified billing address format. Remove abbreviations, use the exact format on your bank statement, and avoid special characters. Another issue that comes up periodically involves currency conversion. Many platforms default to charging in the merchant's local currency. If you are paying in a different currency, the conversion rate applied by your bank is almost always worse than what the platform would have offered through a dynamic currency conversion option at checkout. I learned this the hard way when paying for a European software license and ending up with an effective exchange rate that was point eight percent worse than the interbank rate. Selecting to pay in your local currency when given the option saved me roughly forty dollars on a five hundred dollar transaction.
Security Considerations When Paying Online
The security landscape for online payments has improved considerably, but there are still genuine risks to be aware of. Phishing sites that replicate legitimate payment portals are common, especially for high-value transactions where the stakes are higher. Before entering any payment details, verify that the URL matches the official domain exactly and that the SSL certificate is valid. Look for the padlock icon, but do not rely on it alone since phishing domains can obtain certificates through automated services now. Using a virtual card or a payment service that generates one-time-use card numbers adds a meaningful layer of protection. Services like Privacy.com or features built into certain business banking platforms let you create a single-use card with a preset spending limit. If the merchant's site is compromised or the payment goes to a fraudulent party, the damage is capped at the preset amount. This is especially relevant when paying smaller vendors or unfamiliar platforms where you have limited recourse if things go wrong. Keep detailed records of every transaction. Save the invoice, the confirmation email, the receipt, and any support correspondence in a dedicated folder. If a dispute arises—which happens more often than most people expect—having a complete paper trail cuts resolution time significantly. Chargeback processes typically take between thirty and ninety days, and having organized documentation speeds things along considerably.
When Online Payment Platforms Fall Short
No single platform handles every scenario well. If you are making large recurring payments across multiple vendors, consolidating everything through one service creates a single point of failure. A platform outage or account freeze locks all your payments simultaneously. I once experienced a three-day outage during a licensing renewal window that put our project timeline at risk. Spreading payments across two or three services provides a fallback when one goes down. Some platforms also impose strict geographic restrictions. If you are operating from or paying to merchants in certain regions, you may find that the available payment methods are severely limited. In those cases, alternative routes like direct bank transfer or using a regional payment processor designed for cross-border transactions tends to work better. It is slower, but it avoids the platform-level blocks that appear without warning. Another limitation is the lack of flexibility for non-standard payment terms. Net-30 invoicing, milestone-based payments, or custom contract structures rarely fit into the standardized checkout flows that most platforms offer. When you need something outside the template, you are usually forced back onto manual processes involving purchase orders, wire transfers, and extended approval cycles. This is not a flaw in the platform design so much as a fundamental constraint of automating heterogeneous financial arrangements.
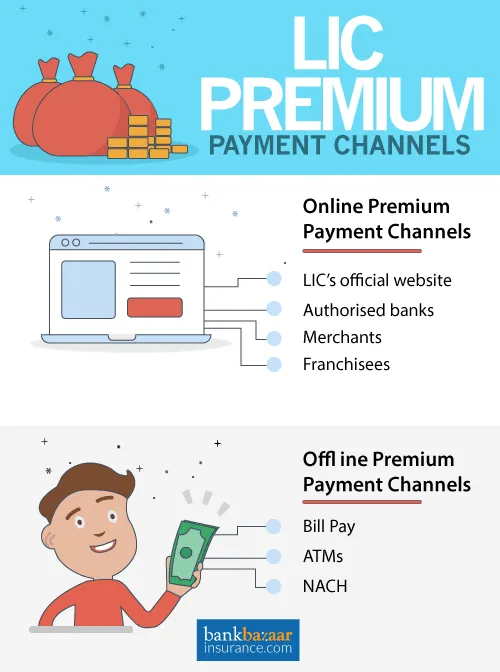
Practical Steps for a Smooth Transaction
Before initiating any payment, confirm the exact amount including taxes and any processing fees. The displayed price is rarely the final charge. Sales tax varies by jurisdiction, and some platforms add a small convenience fee for certain payment methods. Budgeting for the final amount prevents surprises on your statement. Use a dedicated credit card for business-related purchases rather than your primary personal card. This separation makes expense tracking cleaner and isolates your main financial instrument from potential disputes or holds. If a merchant places a temporary hold on your card, it affects only that account and not your everyday spending capacity. After payment, verify that the license or subscription is active within the first twenty-four hours. Do not assume everything is fine just because you received a receipt. Some platforms process payments successfully but fail to trigger the activation on their end due to synchronization delays between the payment gateway and the licensing system. Logging into the service and confirming the subscription status yourself catches these issues while support response times are still fast.
Ideal resolution time for any post-payment issue is within the first two business days. After that, the support queue shifts toward handling longer-term problems, and your ticket gets deprioritized. Acting quickly on discrepancies pays off consistently.