How Pay In 4 Actually Works When You Try It
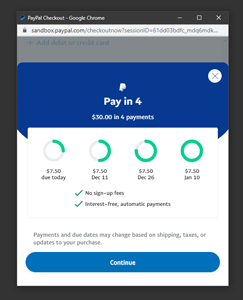
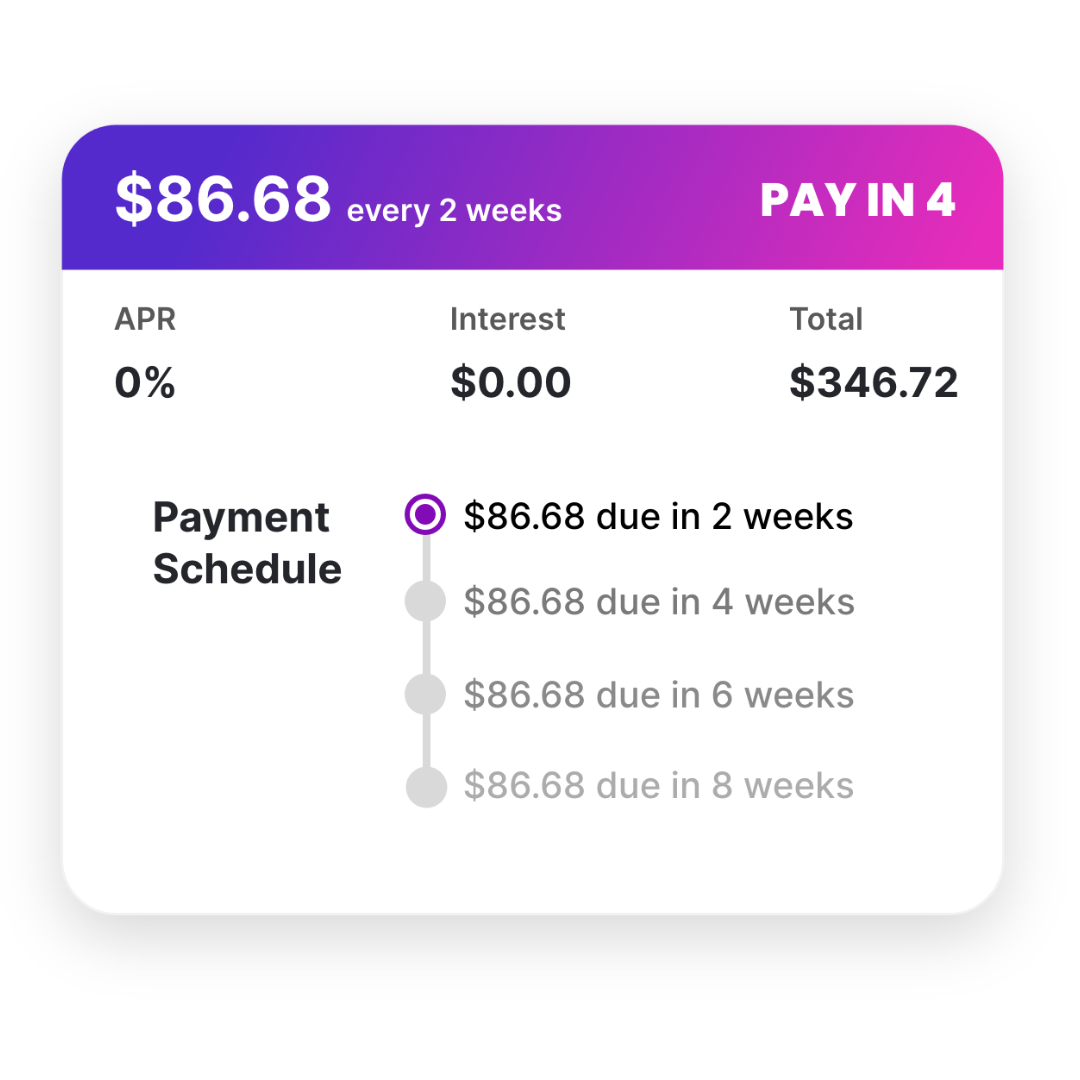
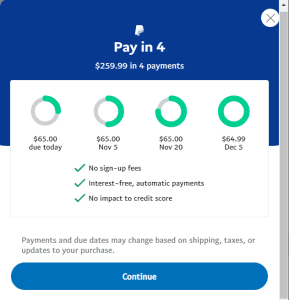
I bought a $400 set of wireless headphones last month using a four-installment plan. The checkout process took about twelve seconds longer than a normal purchase. I entered my card details once, confirmed I wanted to split the charge, and the first payment of $100 went through immediately. The remaining three charges of $100 each are scheduled for fourteen days, twenty-eight days, and forty-two days out. No interest was charged. No hidden fees appeared on my statement. I did get a confirmation email that basically said the same thing four times in slightly different wording. The technology behind this is not complicated. The payment processor divides the total amount by four and schedules automated charges at set intervals. The merchant receives the full amount upfront minus a processing fee, usually between four and eight percent depending on the provider and transaction volume. That fee is why stores push these options aggressively at checkout. They're getting paid faster and more reliably, even after the cut.
Pay In 4 Revolutionizes Checkout How Interestfree Instalments Are Reshaping Consumer Spending
What's actually happening with consumer spending here is behavioral, not technological. When people pay in installments, they mentally separate each charge into its own budget category. Paying $100 feels manageable. Paying $400 upfront triggers a different psychological response. Multiple studies from behavioral finance researchers have documented this effect. The total amount owed is the same, but the perceived burden drops significantly when it's broken into smaller pieces. This is why retailers see higher average order values when BNPL options are available. The data is consistent across platforms. I spent about three weeks setting up Afterpay for a small online store. The integration with Shopify took roughly twenty minutes using their official plugin. Getting it working with a custom WooCommerce build took longer because the REST API documentation was slightly outdated and two endpoints returned deprecated warnings. I ended up using a middleware script written in Node.js that translated the current API calls into the format the older plugin expected. This added about four hours to the setup but prevented constant webhook failures. If you're building on a non-standard platform, budget time for API compatibility issues rather than assuming plug-and-play installation. One thing nobody mentions prominently is the credit check nuance. All major providers say they perform soft credit checks that don't affect your score. This is technically true for the initial approval. However, several providers now report payment history to credit bureaus. If you miss payments, that negative information can appear on your credit report. A few people I know found this out the hard way after their second or third missed payment. The soft pull stays clean, but the hard consequences arrive later. Read the terms about reporting before you assume your credit is untouched.
Another edge case that tripped me up involved partial refunds. When a customer returns only part of an order paid through a four-installment plan, the refund distribution varies by provider. Afterpay returns funds proportionally across all remaining charges and adjusts the future payment amounts. Klarna handles it differently, often applying the refund to the first charge first. Affirm has its own logic. If you're running a store and dealing with returns, factor in the extra support time required to explain the refund schedule to customers. It frustrates people who expect the full refund amount to disappear from their upcoming charges immediately. There's also the matter of spending limits. Each provider sets a limit that increases gradually as you make payments on time. New users often start with limits between $500 and $1,000. This means you cannot stack multiple BNPL accounts to bypass the limit. Some people try anyway by signing up on different devices or using different email addresses, and the providers have identity verification systems that catch this. Accounts get suspended. Money already paid gets locked in pending investigation for two to four weeks. It's not worth the risk. The real downside for consumers involves the spending trap. People routinely spend more when BNPL is available because the friction of a large upfront payment disappears. A customer who would have walked away from a $300 purchase might complete it when facing four payments of $75 instead. This is by design. The companies offering these plans profit from increased transaction volume, not from interest charges. Late fees are where they make serious money, though individual late fees are capped at reasonable levels in most cases.
Get the Full Details
Merchants should know about margin compression. If twenty percent of your sales go through BNPL and you're paying a five percent processing fee on those transactions, your effective margin on that portion drops by five percentage points. On a product with a twenty-five percent margin, you're now working with twenty percent. This matters on thin-margin businesses where every percentage point counts. Calculate your blended margin including BNPL fees before promoting the option heavily on your storefront. If you're looking at alternatives, there are a few worth considering. Some credit unions now offer small installment loans at rates significantly lower than the implicit cost of BNPL late fees. A personal line of credit from a local credit union typically runs between six and twelve percent APR, which is cheaper than any penalty structure these services use. Traditional layaway programs still exist at larger retailers and involve no credit check, no borrowing, and no risk to your credit score. You pay over time but only receive the item after the balance clears. It's slower but completely risk-free. The bottom line is that these payment plans work exactly as advertised for responsible users. The four equal payments arrive on schedule, no interest accumulates, and the merchant gets paid promptly. The system only breaks down when people miss payments, return items, or accumulate multiple active accounts without tracking their total obligations across providers. Keep your combined BNPL commitments under your monthly cash flow capacity and you should have no issues.