Why People Misunderstand Military Pay Charts
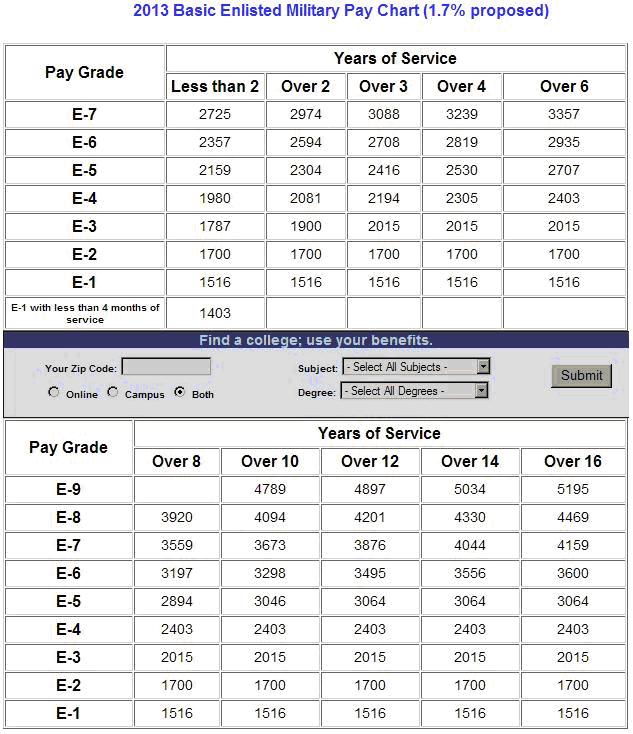
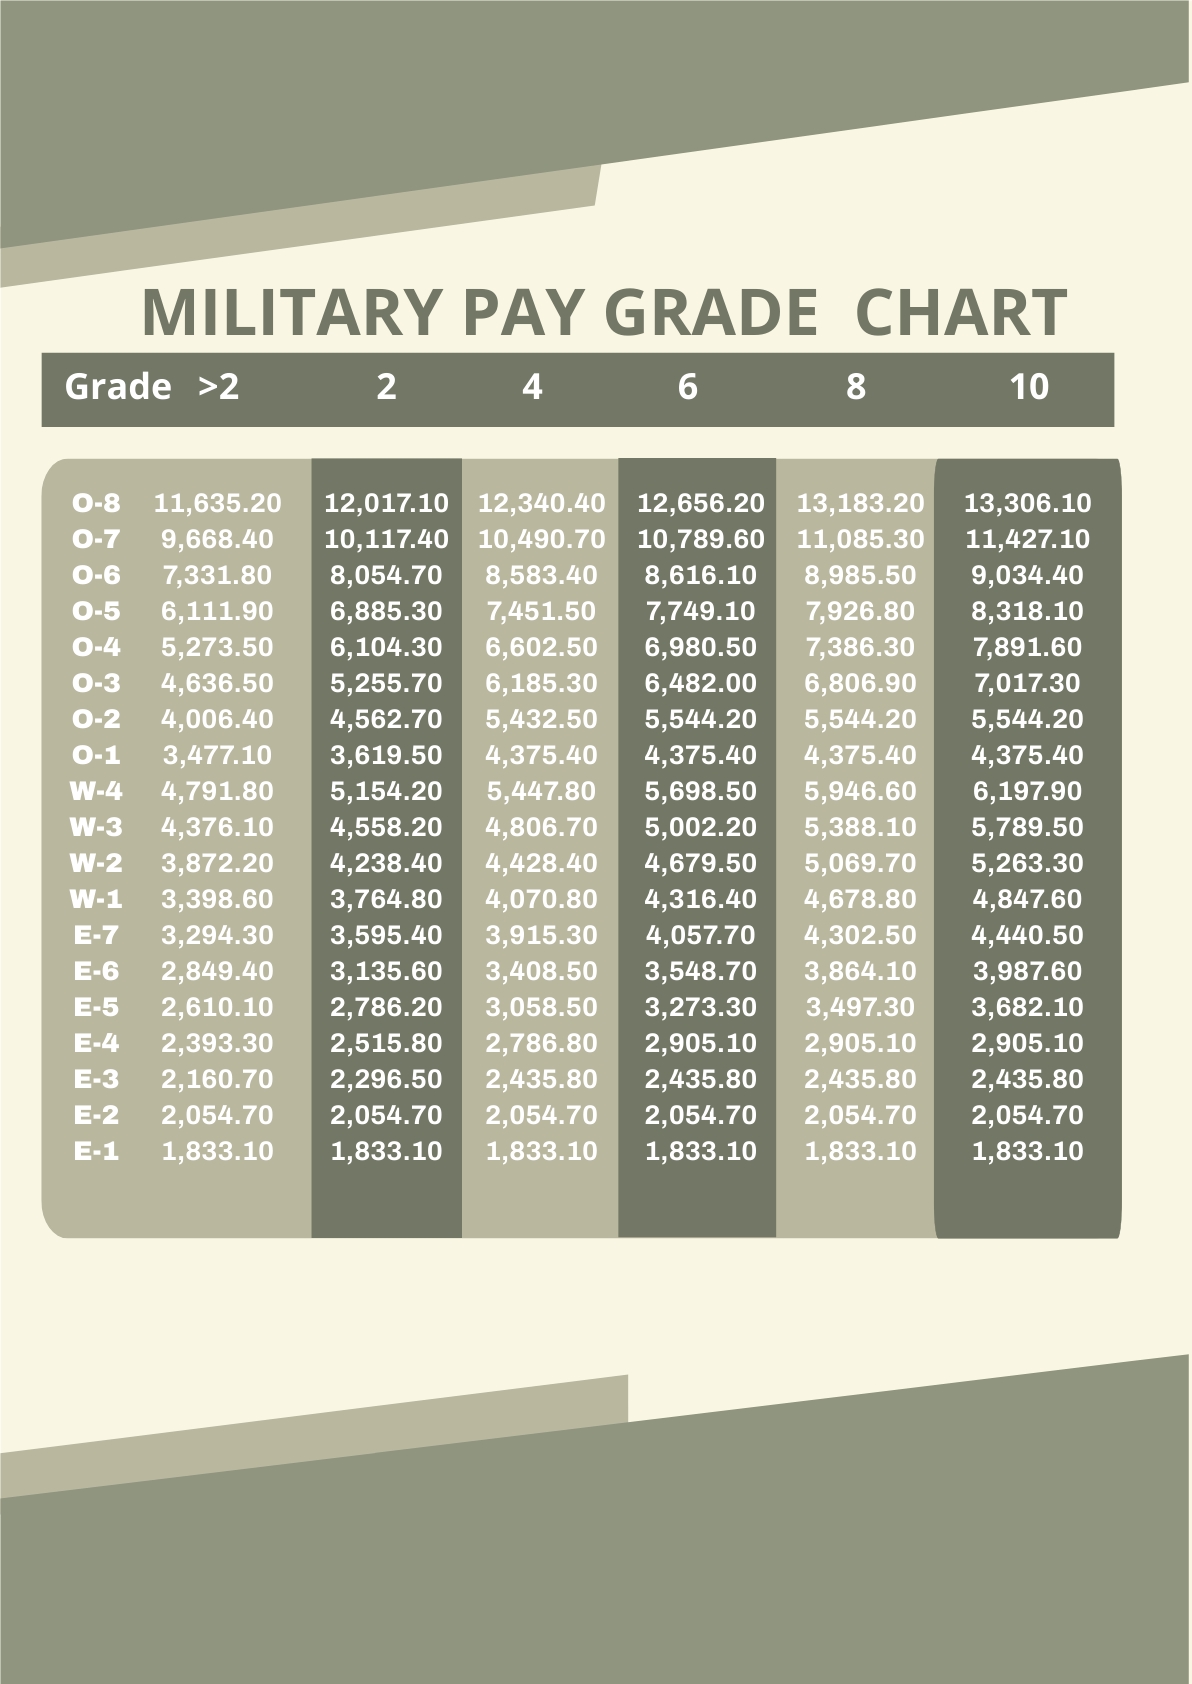
Most service members don't actually read their pay entitlements in full until something goes wrong. The system calculates everything automatically through DFAS, so there's no real reason to look at the numbers unless you're suspicious about a check or preparing for a move. The problem is that military compensation isn't one salary. It's a stack of separate payments that get paid differently, taxed differently, and change based on entirely different variables. Trying to understand the whole thing from a single chart will always leave you confused. The core of everything is the pay table itself. Basic pay is determined by your pay grade and years of service. A 2013 pay chart will show a Private First Class at roughly $1,800 monthly with four years of service, while a Captain with six years sits around $4,800. Those are before-tax amounts and they form the foundation, but they're only about half the story for most service members with families. The other half is made up of allowances that don't show up as taxable income. BAH (Basic Allowance for Housing) is the biggest variable. It's calculated by zip code, dependency status, and pay grade. Two Captains with the same years of service can receive drastically different BAH amounts depending on where they're assigned. A Captain in San Diego gets nearly double what a Captain in Honolulu receives, even though the local cost of housing is arguably lower in some parts of California. The rates for 2013 reflected the post-2008 budget adjustments, and several locations saw noticeable increases that year compared to 2012.
BAS (Basic Allowance for Subsistence) is a flat rate for most enlisted members and officers, but it does vary slightly between tiers. It was approximately $252 per month in 2013 for the standard rate. This covers food and doesn't change based on location or family status. It's simple, predictable, and largely forgotten until you compare net pay after a move where housing costs spike. The combination of basic pay plus BAH plus BAS creates what people call \"military pay,\" but it's not a single number. It's a composite that shifts every time you get a promotion, complete another year of service, get married, have a child, or get reassigned. The 2013 charts captured a specific snapshot in time, and rates adjusted annually for CPI-W increases. If you're looking at a chart from that year now, the actual dollar amounts will differ from current tables. The structure remains the same though.
The Components Nobody Talks About
There are supplemental payments layered on top of the base allowances that most people overlook. Flight pay for aviators adds a fixed monthly amount based on rank, ranging from about $300 to over $900 depending on seniority. Hazardous duty pay covers roles like parachute jumping, demolition, and certain medical specialties. Re-enlistment bonuses are negotiated amounts paid during your first few years after re-upping, and they're taxable as income despite being called \"bonuses.\" The Family Separation Allowance is another one. If you're separated from your dependents for more than 30 days due to orders, you get an additional $250 monthly. It's not automatic. You have to be on orders that trigger the eligibility, and DFAS won't start paying it without proper documentation in your file. I learned this the hard way when my first PCS move left my family behind for six weeks while I handled housing setup. The FSA check never came because nobody in my unit's admin office had submitted the proper paperwork to flag the separation period. I ended up eating out for three weeks straight because I hadn't accounted for the missing allowance. The fix was straightforward once I knew what to ask for — file a DD Form 4 and make sure your command administrator processes it through the finance channel — but the delay was entirely preventable. Combat pay (Imminent Danger Pay) adds another layer for service in designated zones. It's $250 per month and is separate from any deployment per diem. Deployment per diem itself, known as DPM, varies by location and can add several hundred dollars monthly on top. These are taxable, which surprises a lot of people who assume all military pay is tax-free.
Get the Full Details
How the Numbers Break Down in Practice
Let me walk through a concrete example from the 2013 timeframe. An E-5 with six years of service, married with dependents, assigned to Fort Hood, Texas, would look something like this: Basic pay: approximately $3,100 per month. BAH at the with-dependents rate for Fort Hood zip code: roughly $1,200. BAS: $252. Total monthly compensation before any deductions or special pays: about $4,552. That's not all taxable. Basic pay is taxable. BAH and BAS are not. So the effective taxable income is closer to $3,352, which significantly impacts what shows up on your W-2 and how much federal tax gets withheld. Now take the same E-5 and assign them to Travis Air Force Base in California. The basic pay and BAS stay identical. The BAH jumps to roughly $2,400 because of the local housing market. Total monthly compensation is now about $5,752, and the gap is entirely due to geographic location. This is the part that trips people up during Permanent Change of Station moves. You might get a higher gross amount but also face a higher cost of living, and the BAH isn't designed to cover market rent in every case. It covers a standard housing cost for your pay grade and dependency status in that specific area.
If that same E-5 deploys to a designated combat zone, you add the $250 imminent danger pay on top, and possibly a deployment per diem that could range from $150 to over $300 depending on the location. All of that is taxable income. So your take-home might actually decrease slightly relative to your gross because of the higher tax bracket impact on the supplemental amounts.
Common Mistakes When Reading Pay Charts
The biggest mistake is treating a pay chart as a complete picture. A chart shows basic pay by grade and years. That's it. Everything else requires additional lookup tools or personal circumstances. When I worked with service members trying to figure out their actual compensation, I'd see people comparing basic pay figures between ranks and wondering why their friend at the same grade made more. The answer was almost always BAH location differences, not basic pay discrepancies. Another frequent error is not accounting for how raises actually work. Military basic pay increases happen on October 1st each year through the annual COLA adjustment, but you also gain credit for each year of service. The increments aren't linear. There are bigger jumps at certain thresholds, particularly around the E-4 to E-5 transition and the O-1 to O-2 promotion. The 2013 chart reflected a COLA increase of about 1.5 percent, which was modest compared to the double-digit increases seen during earlier years. You also need to understand what deductions actually come out. Federal income tax withholding for military members uses standard withholding allowances, and many people choose to have extra withheld to avoid surprises at tax time. FICA taxes (Social Security and Medicare) still apply to basic pay. There's no military-specific exemption. SGLI (Servicemembers' Group Life Insurance) premiums are deducted pre-tax. Thrift Savings Plan contributions reduce your taxable income if you elect to contribute. All of these interact in ways that a simple pay chart cannot show you.

There's also the question of retainer pay versus active duty pay. If you're looking at older pay charts that include reserve components, the calculations diverge significantly. Reserve members typically earn fewer months of pay per year unless they're on active duty orders. A Reservist at the same grade and years of service as an Active Duty member might earn roughly 12 percent of what that member earns annually under normal conditions. That gap closes completely during extended active duty deployments.
What the Charts Don't Tell You About Real Compensation
The 2013 landscape included several policy changes that affected compensation in ways a static chart couldn't capture. The expansion of healthcare access through TRICARE modifications changed the real value of military service for families with medical needs. The introduction of the Blended Retirement System hadn't happened yet in 2013, so all service members at that time were under the legacy Defined Benefit plan. That means anyone who served through 2013 and stayed in for 20 years received the full annuity calculation, which was generally considered more generous than the BRS that replaced it for those entering after 2018. The housing allowance cap was also a factor in 2013. Congress had imposed limitations on BAH for service members sharing quarters, which affected a significant portion of junior enlisted personnel. If you were single and assigned to base housing with roommates, your BAH was reduced. This policy targeted cost containment but created genuine hardship for some junior members who found themselves underwater on the allowance if they chose to live off base. The workaround was to request a waiver through your command, but approval rates varied by installation and the commanding officer's priorities. Pay gaps for certain specialties represent another area where charts fall short. Medical professionals, lawyers, and chaplains enter at higher ranks than their years of service would normally indicate. A Navy doctor with two years of commissioned service might enter as a Lieutenant Commander (O-4), which puts their basic pay in a completely different tier than an E-5 with two years. The charts show the O-4 rate, but the context of why someone is at that rank level matters enormously for understanding total compensation trajectory.
Working With What You Have
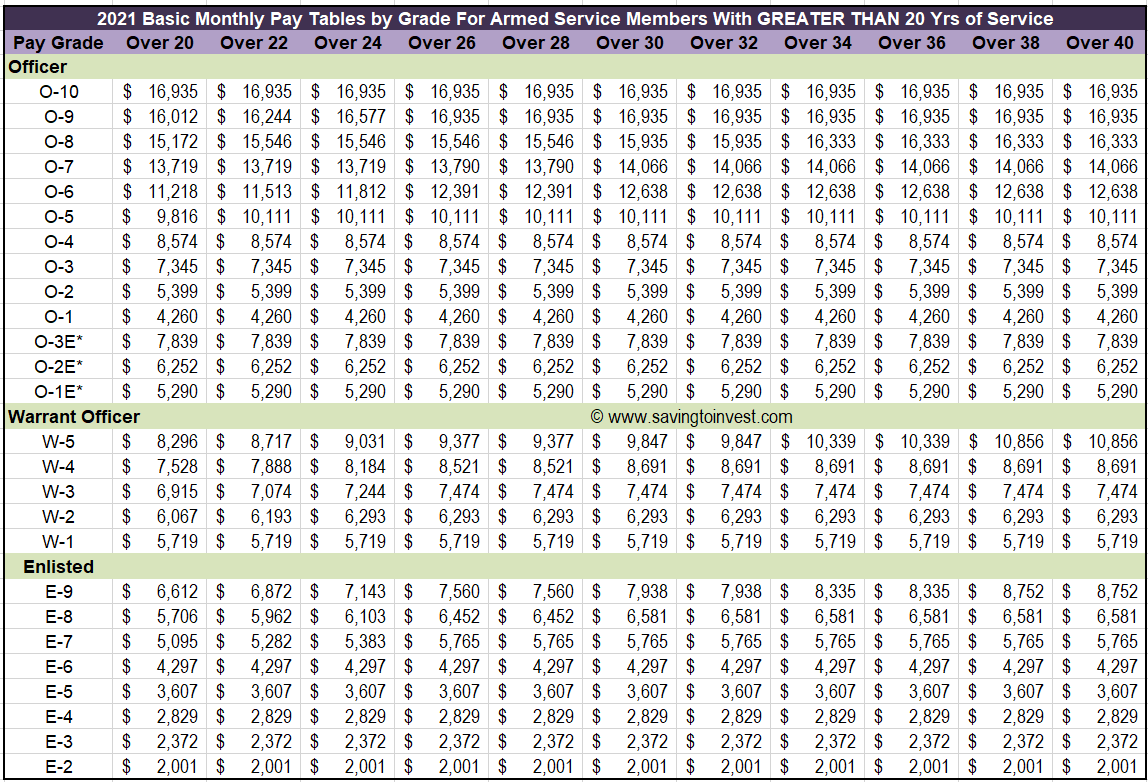
If you're trying to reconstruct or reference the 2013 pay structure, the official source remains the Defense Finance and Accounting Service website. They archived the pay tables, and the PDF documents contain the full monthly rates for every grade and year-of-service combination. The BAH rates for 2013 are available through the VA's BAH lookup tool, which maintains historical data. Combining both sources gives you the complete picture for that fiscal year. The practical approach is to start with your specific situation and work outward. Know your pay grade and years of service. Determine your dependency status. Identify your duty station zip code. Then pull the basic pay from the DFAS chart and the BAH rate from the VA table. Add BAS. Factor in any special pays your role qualifies for. Subtract the deductions you know apply. What remains is your actual monthly compensation for that year. Don't rely on memory or rough estimates. The differences between brackets and locations are large enough that approximations lead to significant miscalculations. A misread BAH rate can account for a $500 to $1,000 monthly error, which compounds to thousands over a career. The effort to look up the exact figures takes less than ten minutes and prevents costly mistakes down the line.
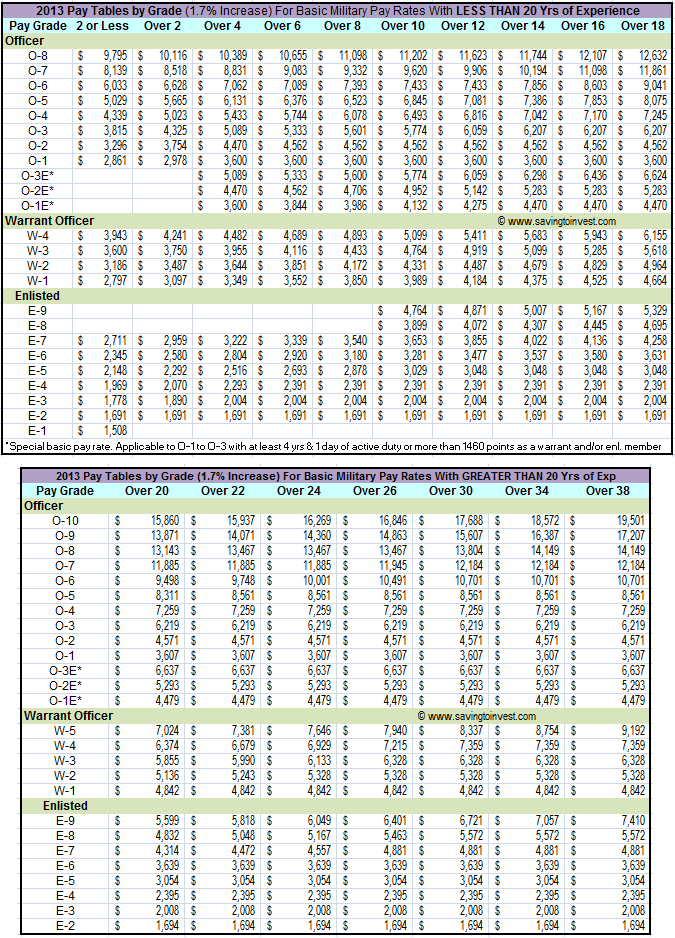
The system is designed to be transparent if you're willing to dig into the details. The charts exist. The formulas are public. The allowances follow clear rules. What's missing from every chart is the context of how your personal circumstances shift the numbers, and that's something you have to calculate for yourself.