Paying Without an Account at CareCredit Checkout
Most people showing up at a merchant's checkout page with CareCredit don't realize there's actually a guest checkout path built into their application flow. It works, it's faster than creating an account, and very few people use it because they go straight for the login button out of habit. When you start a CareCredit application mid-checkout, the merchant passes a redirect URL back to Synovus (which services the account) along with the purchase amount and merchant category code. The application itself is a soft-pull FICO decision in most cases. You answer basic income, housing status, and SSN questions. The whole thing takes about ninety seconds on a clean session. I learned the hard way that CareCredit's guest flow has a bug where the return URL drops if you navigate away from the tab during the credit check. Once, while applying for a dental procedure, I accidentally clicked my browser's back button during the identity verification step. The application hung on a blank screen with the loading spinner still going. I waited five minutes, closed the tab, restarted from the merchant page, and this time made absolutely sure not to touch anything until I saw the approval screen. Since then I just keep the tab still and let it finish.Pay Carecredit As Guest Quick Guide How To Get Instant Approval At Checkout
Start by reaching the checkout page of any store that accepts CareCredit at payment. Look for the CareCredit logo or button — usually sitting next to PayPal and the credit card fields. Click it. You'll land on a CareCredit application page. You do not need an existing account. Enter your date of birth, the last four digits of your Social Security number, your email, and a phone number that can receive texts. This is where most people stall because they confuse the "existing customer" path with the new applicant path. Make sure you're on the new application form. Next you'll fill in income, monthly housing payment, and employment details. The exact income number matters less than consistency — if your stated income conflicts with what shows up on a quick database lookup, the system flags it and routes you to manual review, which kills your instant approval odds. Don't inflate it. Use your actual gross monthly income.
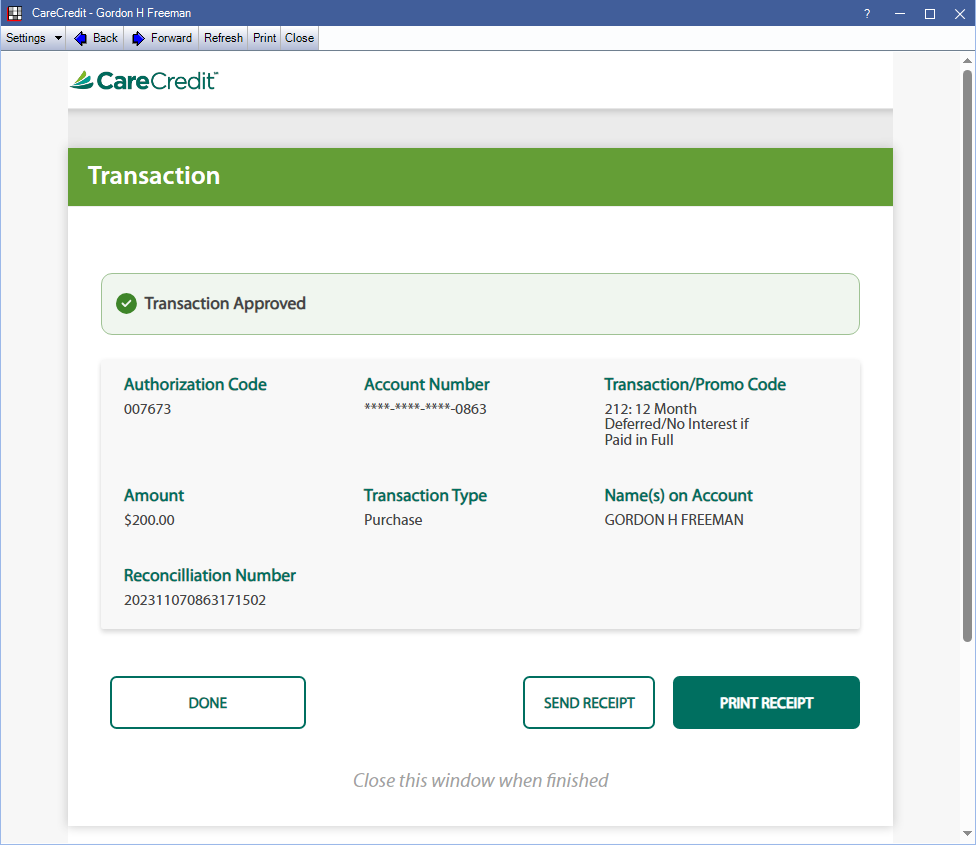
Once you submit, you get a decision in seconds if the soft pull comes back clean. Approved means you see the financing options: zero percent promotional periods, the standard 21.99% variable APR after promotion, or the minimum payment calculation. Select the option you want and you're sent back to the merchant to complete the purchase. The approval is good for thirty days from the decision date. If you don't finish the purchase at the original merchant within that window, you start over. I've seen people get approved, walk away to compare prices elsewhere, come back two weeks later, and get surprised when the old application was stale. Just finish the transaction the same day.
There are several things that go wrong that nobody warns you about. Your browser's cookie settings matter more than you'd think. If you're running aggressive cookie blocking or private browsing with strict third-party cookie rejection, the session token that ties your application to the merchant's return URL sometimes fails to persist. The result is you get approved but then get sent back to the merchant with a "transaction expired" error. Close your cookie blocker for the checkout domain, or use a normal browsing session. Another edge case that catches people: the application shows one purchase amount but the final total at the merchant includes tax and shipping that push the balance above the approved credit line. This happens especially on medical and dental offices where the procedure estimate was $800 but after the scheduled hygiene add-ons and state tax the receipt comes to $892. CareCredit will approve the application but decline the transaction at point of sale if the final amount exceeds your limit. Call the merchant before you finish checkout and ask them to hold the exact total, or pay the difference with another method. I learned this one after a $47 discrepancy ruined a $2,200 dental application on a $2,500 line. The instant approval itself is not the same as being pre-approved. Pre-approval is a marketing term CareCredit uses forSoft-pull offers sent to you in the mail or via email. Those just mean you have a higher likelihood of approval, not a guaranteed one. The actual instant approval at checkout is the real decision. Treat it as binding. Once you click accept, the account is open and the first statement cycles immediately. If you already have a CareCredit card and just want to pay with it at a merchant that supports it, guest checkout still applies in some cases, but it's simpler — you just enter your account number and the PIN you set up when you opened the card. The system recognizes you and skips the application entirely. This is the fastest path by far. Common reasons the system rejects an instant approval request: recently opened multiple credit lines within the last ninety days, a hard inquiry from another lender in the past month, an existing CareCredit account with a balance that pushes your utilization above 80%, or an SSN that doesn't match the name on file. If you hit any of those, the application will either decline you outright or route you to a longer manual underwriting process that takes three to five business days. There is no workaround for a hard rejection other than waiting out the inquiry window and reapplying. For merchants that don't display the CareCredit button prominently — some smaller veterinary clinics and chiropractors hide it in their financing FAQ instead of on the payment screen — you can still initiate a guest application directly at carecredit.com and select "apply at point of sale." Enter the merchant's tax ID or store number when prompted. This gets you the same approval flow but skips the merchant redirect entirely. It's marginally faster and sometimes more reliable if the merchant's integration is lagging. One final thing that people always miss: the promotional financing terms vary by merchant category. A dental office might offer six months no interest on purchases over $1,000 while a retail eyewear shop offers twelve months on $500 minimum. Read the specific offer on the approval screen before you commit. The default term is the standard revolving account, which carries the full variable APR from day one unless you explicitly select a promotional plan. Selecting the wrong option is how people get hit with retroactive interest they didn't expect.