Why Most Financial Flow Optimization Fails Before It Starts
I spent three years trying to fix broken payment cycles at a mid-market logistics company. We had $14 million in monthly revenue, but the cash conversion cycle was sitting at 67 days. That is not a typo. Sixty-seven days. The problem was not a lack of tools or a lack of effort. It was that nobody in the organization actually understood how their individual decisions compounded across the entire flow from invoice to collection to disbursement. The concept behind Otimizando Fluxos Financeiros Guia Completo Para Maior Eficincia E Rentabilidade is straightforward enough on paper. You map every dollar as it moves through your business, identify where it stagnates, and remove friction. But the gap between the paper version and what actually happens is where most companies lose money. I learned this the hard way when we implemented a perfect theoretical model and watched it collapse within six weeks because nobody had accounted for the reality of how invoices actually get approved on a Friday afternoon.
Otimizando Fluxos Financeiros Guia Completo Para Maior Eficincia E Rentabilidade: What It Actually Means in Practice
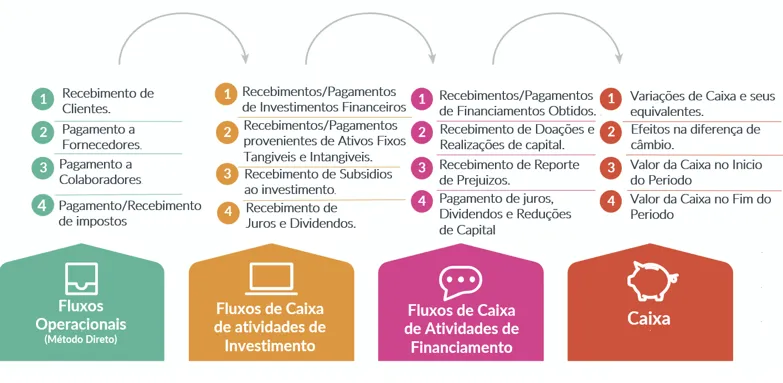
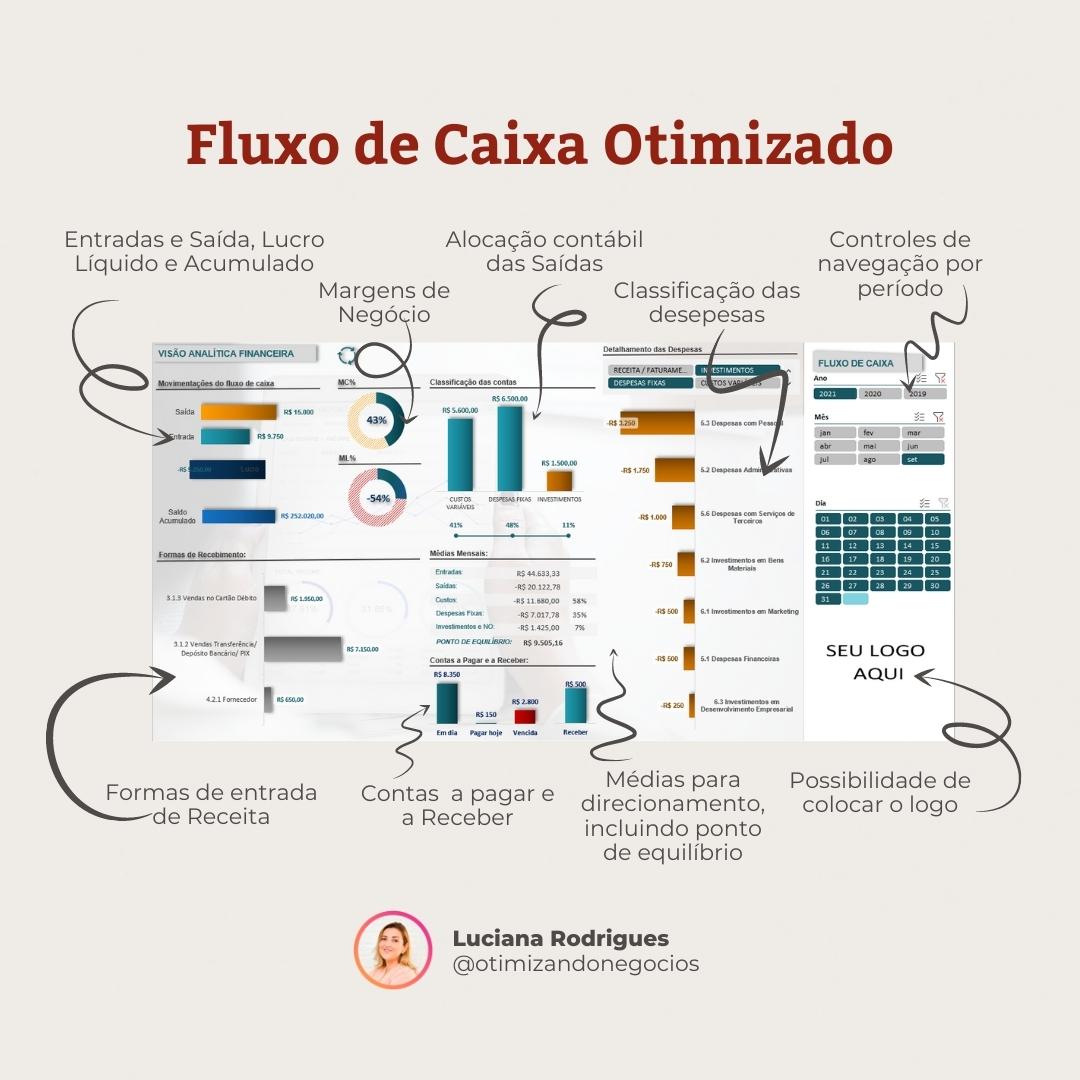
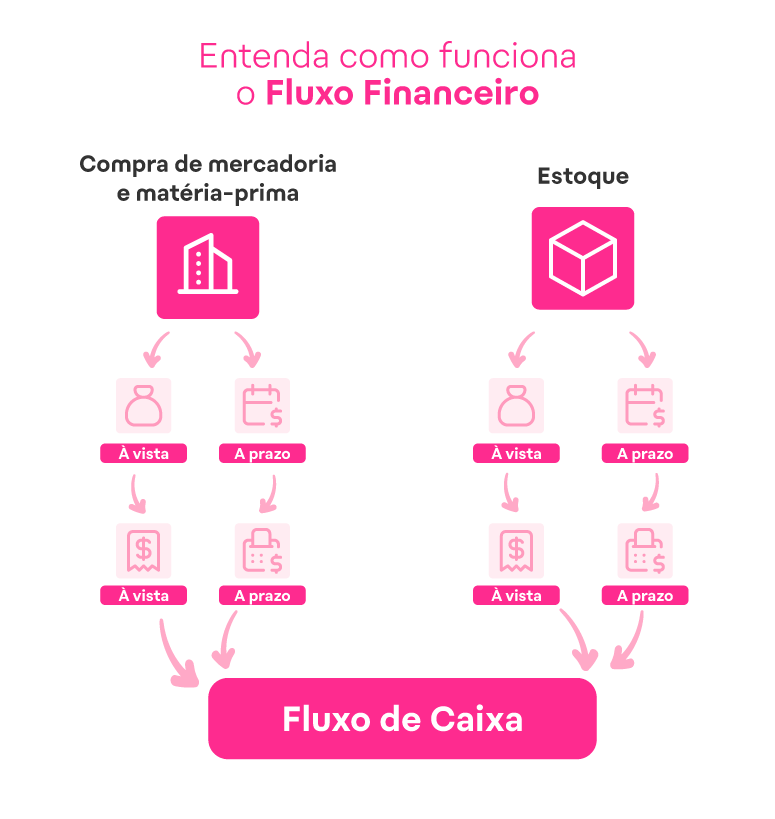
The Portuguese phrase translates to optimizing financial flows for greater efficiency and profitability, and the complete guide framework around it covers three interdependent layers. The first layer is visibility. You need to know exactly where money enters, where it sits, and where it leaves. Most companies have weak visibility here because they track revenue and expenses separately rather than as a unified flow. The second layer is control. Once you can see the flow, you need gates and timelines that prevent delays from accumulating. The third layer is acceleration. This is where you actively shorten the time between value creation and cash realization. I ran into a specific edge case that took me four months to resolve. We had a client base where 40 percent of invoices were submitted with one missing attachment, usually a delivery confirmation or a signed acceptance form. These invoices went into an approval queue and sat there for an average of 11 days waiting for the missing document. We could not just auto-approve them because compliance required the documentation. But we also could not keep losing 11 days of float on nearly half our invoicing volume. The workaround was relatively simple but required changes across two departments. We moved the delivery confirmation requirement from a post-invoice checkpoint to a pre-invoice gate. Sales reps had to upload the signed delivery note before the invoice system would even generate a draft. It felt like adding friction at first, but it actually reduced total processing time by an estimated 60 percent because the invoices that did get submitted were complete. Collection cycles dropped from 38 days to 22 days within the next quarter.
The Three Levers That Actually Move the Needle
There are essentially three actions you can take to optimize financial flows, and they do not all require technology investments. Sometimes the biggest gains come from changing a policy or a sequence of events. The first lever is receivables acceleration. This is about reducing the time between when you deliver goods or services and when you receive payment. The standard advice is to tighten payment terms, send invoices immediately, and follow up aggressively. Those things matter, but the counter-intuitive insight most people miss is that the timing of your invoice delivery matters more than the payment terms themselves. A 2/10 net 30 term means very little if your invoice arrives two weeks after the work was completed. I once worked with a consulting firm that changed nothing about their pricing or their collection practices but started sending invoices on the same day the project milestone was signed off. Their average collection period dropped from 44 days to 29 days. That is a purely operational change with zero financial cost. The second lever is payables optimization. This is not about delaying payments indefinitely. It is about aligning your outflows with your inflows so you are not constantly bridging gaps with short-term borrowing. The pitfall here is confusing payables optimization withsupplier relationship damage. If you stretch payments to the point where vendors start charging late fees or refusing credit terms, you have made the problem worse. The sweet spot is negotiating payment windows that match your actual cash receipt patterns. Most vendors would rather get paid in 45 days consistently than in 30 days sporadically with disputes attached.
Get the Full Details
The third lever is working capital restructuring. This involves inventory management, prepaid expense timing, and the structural alignment of your operating cycle. Companies with significant inventory holdings often have the largest hidden margin leak. Every dollar tied up in slow-moving stock is a dollar that cannot be deployed elsewhere. I analyzed a manufacturing operation where $2.3 million in inventory was sitting 90 days past its optimal turnover window. By implementing a more aggressive dead-stock liquidation process and renegotiating reorder points, we freed up $1.7 million in cash within eight weeks. That is not theoretical. That was real cash that went directly to reducing their revolving credit line and cutting interest expense.
Common Pitfalls That Waste More Money Than They Save
The most expensive mistake I see companies make is treating financial flow optimization as a technology problem when it is really a process problem. You can implement the most sophisticated cash flow management software in the world, and it will still produce garbage output if your underlying processes are broken. Automation amplifies existing workflows. If your workflow has delays built into it, automation just makes those delays happen faster. Another pitfall is over-optimizing at the wrong level. I watched a regional hospital system spend $340,000 on a financial optimization platform that promised to reduce their days sales outstanding by 15 days. They achieved a 3-day improvement. The reason was that the system was optimized for transactional efficiency but completely ignored the clinical approval workflows that sat between service delivery and billing. No amount of software would fix that without clinical buy-in, and there was none. We ended up recommending they stop the platform rollout and instead restructure their charge capture process, which cost $12,000 and reduced DSO by 11 days over six months. A third trap is optimizing for cash flow at the expense of revenue. Shortening collection periods by being aggressive with customers can work until it stops working. I encountered a situation where a software company was so focused on reducing their AR aging that they started withholding feature access for invoices just 15 days past due. Their collections improved, but their customer churn rate increased by 8 percent in the following quarter. The revenue loss from churn far exceeded the interest savings from faster collections. There is a point where pushing cash flow optimization too hard becomes self-defeating, and most companies do not know where that point is until they cross it.
How to Build a Working Framework Without Overcomplicating It
Start with a cash flow map. Not a forecast, not a budget, a map. Draw every transaction type that moves money in and out of your business. Include the timestamps. Note who approves each step. Identify where money waits. This exercise alone usually reveals three to five bottleneck points that account for 60 to 70 percent of your delay. Once you have the map, prioritize the bottlenecks by impact and effort. A bottleneck that costs you $40,000 per month in delayed float but requires two days of process redesign should be addressed before a bottleneck that costs $5,000 per month but requires a full system migration. I use a simple scoring matrix: estimated monthly cash impact divided by estimated implementation effort in person-days. Higher scores get addressed first. It is not sophisticated, but it prevents the common mistake of solving easy problems while ignoring important ones. From there, implement changes in isolation whenever possible. Do not try to optimize everything at once. Pick one bottleneck, fix it, measure the result, and then move to the next. When we ran the workaround I described earlier with the missing delivery confirmations, we isolated it from the broader invoice process. We tracked the collection cycle for that specific client segment separately before rolling it out company-wide. This approach lets you catch failures early without destabilizing your entire financial operation.
When This Approach Does Not Work
Financial flow optimization has hard limits. If your business model is fundamentally misaligned, no amount of process improvement will fix it. A company that sells custom enterprise solutions with 12-month delivery cycles and 5 percent retention deposits will always have a long cash conversion cycle. The structure of the revenue model dictates the floor on how efficient your flows can be. You can optimize within that constraint, but you cannot eliminate it. Similarly, this approach does not help if your margins are negative. Reducing collection time from 60 days to 45 days does not matter if you are losing money on every transaction. I have seen too many operators focus on cash flow metrics while ignoring unit economics. Positive cash flow with negative margins is just a faster path to insolvency. Always verify your contribution margins before investing significant effort in flow optimization. The final limitation is organizational capacity. Every optimization requires someone to change how they work. If your team is already operating at maximum capacity with no bandwidth for process changes, new workflows will either fail or create secondary problems. I recommend assessing your team's change readiness before committing to a multi-month optimization initiative. If they cannot absorb the initial disruption, the project will underperform regardless of how well designed it is on paper.
Measuring Success Without Getting Lost in Metrics
Track days sales outstanding, days payable outstanding, and the cash conversion cycle. These three numbers tell you everything you need to know about your flow efficiency. Anything else is supplementary. I have seen companies chase twelve different KPIs and end up with no clear picture of whether they are actually improving. Stick to the core trio and review them monthly. If DSO is dropping and DPO is stable while the cash conversion cycle shortens, you are moving in the right direction. Do not optimize in a vacuum. Compare your numbers against industry benchmarks relevant to your sector. A cash conversion cycle of 30 days is excellent for a software company but disastrous for a grocery retailer. Context matters more than absolute values. I once evaluated a company that was proud of their 22-day DSO, but their competitors were averaging 14 days. They were not competitive. Their pride was based on incomplete information. The framework embedded in Otimizando Fluxos Financeiros Guia Completo Para Maior Eficincia E Rentabilidade works because it forces you to look at the entire flow rather than isolated components. That holistic view is what separates companies that improve their cash position sustainably from companies that make incremental gains that erode over time. The logistics company I mentioned at the start ended the year with a cash conversion cycle of 31 days, down from 67. It was not a single miracle fix. It was 14 small process changes implemented sequentially over nine months, each one validated before the next began. That is the realistic version of financial flow optimization. Not dramatic. Just consistent.