Understanding The Intersection Of Post-Secondary Debt And Marriage Contracts In Ontario
Most people think about marriage agreements in terms of assets — the house, the savings, the retirement accounts. They rarely think about what happens when one partner walks away from $80,000 in student loans after finishing their degree, or when a business gets built during a two-year MBA program. Ontario family law doesn't make this straightforward, and the gaps in how people handle it cause real problems down the line. I ran into a situation last year where a couple had signed a simple prenup that only addressed a jointly owned condo. The wife had taken out a line of credit during her nursing program to cover living expenses while her partner worked full-time. When they separated seven years later, he argued those debts were his responsibility because he'd been the sole earner during that period. She argued they were hers because the degree was in her name. The court looked at the domestic contract, saw it was silent on educational debt, and had to determine who owed what based on general principles. It took fourteen months and cost them roughly $38,000 in legal fees between them to resolve a question that a single sentence in their agreement could have settled for free.
Os Postsc And Marriage Agreements What You Need To Know To Protect Your Future
Let me clarify what I mean by this topic, because the phrasing isn't standard legal terminology. In Ontario, "postsc" refers to post-secondary education considerations — the debts, assets, and earning capacity changes that come with advanced schooling — and how those interact with marriage agreements under the Family Law Act. The core issue is that Ontario operates on a system called equalization of net family property, and post-secondary education creates specific complications within that framework. When you marry in Ontario without a contract, the default rule is that each spouse equalizes the growth in their net worth that occurred during the marriage. Assets brought into the marriage are excluded from that calculation, but any increase in value of those assets during the marriage is shared. This sounds clean. It isn't. Here is where it gets messy. A student loan or educational line of credit taken out before marriage is typically considered a pre-marital debt and excluded from equalization. But if you take out education debt during the marriage, it becomes part of the equalization calculation. The person who borrowed the money owes it. The other spouse doesn't automatically share that burden unless the court decides otherwise based on how the funds were used. That's where disagreements happen.
There's also the question of human capital. Ontario does not directly divide future earning potential in an equalization calculation. If someone goes back to school during the marriage, gets a professional designation, and then their income jumps by $120,000 a year as a result, the other spouse has no claim on that increased earning capacity. The only way that income factor enters the picture is indirectly — through the standard of living it enables, which might allow more savings to accumulate during the marriage. But the degree itself, the license, the professional network — none of that is divisible property under Ontario law. I've seen this cause Problems in two specific ways. The first is when one spouse funds the other's education through overtime work or a second job, and then the educated spouse leaves the marriage shortly after graduation. The contributing spouse gets nothing special for that sacrifice. The second is when educational assets — things like a residency match, a licensing exam pass, or a fellowship position — have enormous financial value but zero legal recognition as property. Domestic contracts in Ontario are governed by Part III of the Family Law Act. To be enforceable, they must meet several requirements: both parties need full financial disclosure, each needs the opportunity to get independent legal advice, and the agreement can't be unconscionable at the time it's signed. Most people skip the independent legal advice piece and sign whatever template they found online. That doesn't automatically void the agreement, but it makes it far easier for a court to set aside later if one party claims they didn't understand what they were signing.
Get the Full Details
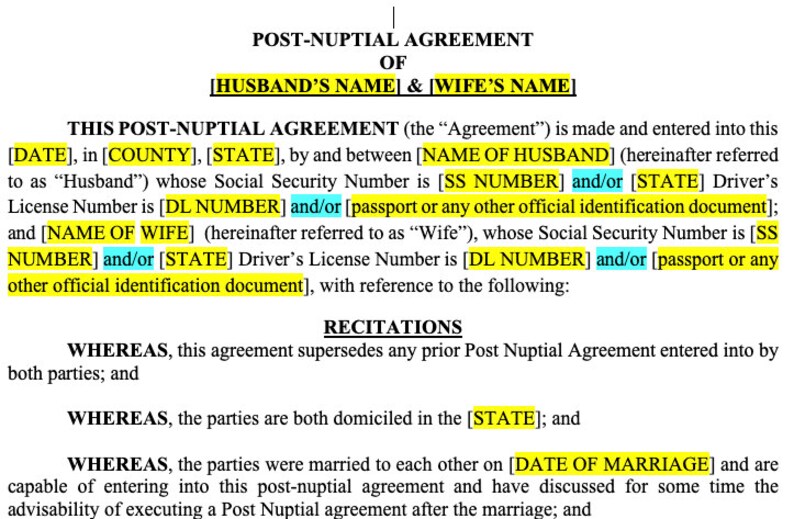
The practical workaround that actually works is to treat post-secondary education situations the same way you'd treat any other major financial event. If one partner is about to start a program that will generate significant debt or alter earning capacity substantially, you draft a specific addendum to your marriage agreement that addresses it. Here's what that addendum should cover: First, identify every education-related debt by account number, lender, and balance at the time of marriage or program commencement. Second, specify who is responsible for each debt during and after the marriage. Third, address any non-financial contributions — the stay-at-home partner who picks up extra hours so the student can focus on exams — and whether those contributions warrant compensation or a property adjustment. Fourth, define how any intellectual property, licensing fees, or professional credentials earned during the marriage will be treated. One detail people miss: if you're already married and haven't signed anything, you can still enter into a separation agreement or cohabitation agreement at any point. These don't require the same formalities as a prenuptial agreement, though independent legal advice is still strongly recommended. I had a client who signed a postnup at age thirty-four that specifically addressed her husband's upcoming medical residency. It outlined how his training debt would be handled, how his stipend income would be treated, and what would happen to his patient referral network if they separated. The agreement held up without challenge when they divorced five years later.
Another thing worth knowing: Ontario's equalization calculation uses a valuation date, which is the later of the date of separation or the date the divorce is granted. Any education-related debts that get paid down or forgiven between marriage and separation will affect the net family property calculation differently than if they remain outstanding. This matters more than most people realize because medical and dental residency programs often have loan forgiveness provisions that trigger after a certain period of practice. If your spouse is in a residency program when you separate, those future forgiveness benefits are not currently realized — they're speculative. Courts have dealt with this inconsistently, so having a contract that addresses it is valuable. Here's a counter-intuitive point: sometimes not signing an agreement is better than signing a bad one. I've reviewed domestic contracts where the language was so poorly drafted that it created ambiguity on exactly the issues it was supposed to resolve. A vague clause about "shared responsibilities" during education ended up being interpreted against the drafter under the contra proferentem rule, which is a standard principle of contract interpretation. That meant the spouse who wrote the agreement ended up with less protection than if they'd had no agreement at all. If you're considering a marriage agreement with post-secondary education considerations, the process usually takes between two and six weeks depending on how complicated the financial situation is. You'll need current tax returns, notices of assessment, lists of all debts and assets, and documentation of any ongoing educational programs. Each party should consult their own lawyer, which typically runs between $2,000 and $5,000 per person for a straightforward agreement, or $5,000 to $15,000 if there are business interests, cross-border elements, or complex debt structures involved.
The biggest limitation of marriage agreements in Ontario is that they cannot predetermine child custody or child support. Those matters are always decided based on the child's best interests at the time the issue arises, regardless of what the parents agreed to beforehand. Spousal support can be addressed in an agreement, but courts retain the power to vary support terms if circumstances change significantly and the original terms became unconscionable. This is rare but it does happen, particularly in cases where one spouse gave up a career to support the other through a professional program and the agreement didn't account for that sacrifice. If you don't want to go the domestic contract route, there are limited alternatives. You can open a separate bank account for education-related expenses and keep it completely separate from joint accounts. You can pay off education debt before marrying. You can structure any shared income during the education period through a formal loan agreement rather than treating it as a gift. None of these approaches offer the same level of protection as a properly drafted agreement, but they're better than nothing when a contract isn't feasible. The bottom line is that post-secondary education during marriage creates financial asymmetries that Ontario's default family law rules weren't really designed to handle gracefully. The system assumes relatively balanced earning patterns and straightforward asset accumulation. When one person is studying while the other is working, or when one person's future earnings are about to change dramatically, the gaps in the default rules become very visible. A marriage agreement that specifically addresses those gaps is the only reliable way to close them.