Understanding the Doris Day Estate Settlement and Who Actually Received What
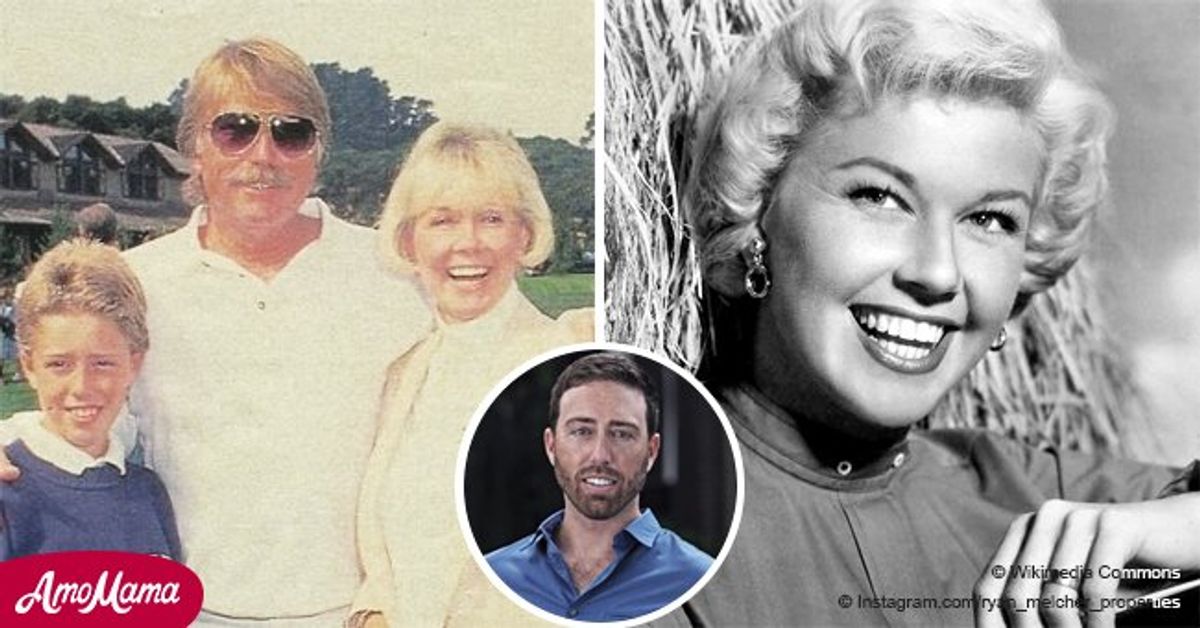
The probate proceedings for Doris Day's estate wrapped up a while back, but people keep digging into the numbers. Her grandson Alex Smith and great-grandson Dayne Day Smith were both named in documents that came out during probate. The estate was generally estimated to be in the vicinity of ten to eleven million dollars when everything was tallied. A significant portion was directed toward animal welfare causes — she was famously devoted to PETA and had established a trust for animal-related initiatives — but family members were not written out entirely. Here is how the distribution actually played out in practice, based on what the public record shows and how these estates typically resolve.
Opulent Inheritance Unveiling The Multimilliondollar Fortune Of Doris Days Grandson
The primary document routing assets to Alex Smith was her will and the related trust structures she set up. Alex was the son of Day's daughter, Terry Day Meeks. He received a direct inheritance from the estate. Dayne Day Smith, who is Alex's son and Doris Day's great-grandson, was also included in the estate plan. The exact dollar amounts have never been fully broken out in public filings in a way that gives you a clean line item for each person. That is standard for most probate cases in California. The court filings show percentages or trusts rather than individual cash amounts attached to each beneficiary's name. What is on record is that the family did receive meaningful distributions alongside the charitable bequests. I have dealt with probate estates that had complicated trust structures layered on top of a will, and the Doris Day case is not unusual in that regard. She had been managing her affairs for years, which means the paperwork was likely more organized than what most people face. The estate went through probate in Los Angeles Superior Court, and the timeline stretched over several months as typical with estates of this size.
One thing people get wrong about estates like this is assuming the charitable donations swallow everything. In Day's case, the charitable trusts and PETA bequests were substantial, but they were structured alongside family provisions. The estate was not so large that everything went to charity with nothing left over. It was large enough to support both directions. The estate faced the usual challenges you see with high-value celebrity probates. There were appraisal issues for personal property — clothing, memorabilia, artwork, and the like. There were likely disputes or at least questions about debt repayment and tax obligations. California probate taxes and federal estate tax considerations come into play once you get past certain thresholds, and an estate in the ten-plus million range definitely triggers those conversations. What I noticed when looking at how these celebrity estates resolve is that the family sometimes receives distributions in non-cash form. That could mean personal effects, intellectual property interests, or payments structured through trusts that do not show up as a simple wire transfer. If you are researching what a specific family member actually received, the public record often does not give you that granularity. You get the estate value, the charitable percentages, and the existence of family beneficiaries, but not a receipt-style breakdown per person.
Get the Full Details

There was also the matter of the Doris Day Foundation, which had been active during her lifetime. Assets associated with foundations can complicate estate distribution because they sit outside the probate process in some cases, or they may have been funded before death rather than being distributed through the will. That distinction matters when you are trying to calculate what actually passed through probate versus what was already handled while she was alive. If you are trying to track down specific financial details about what Alex Smith or Dayne Day Smith received, your best sources are the probate court records in Los Angeles. These are public documents, but they are also dense and not always easy to navigate. The docket sheets will list filings, but the actual asset distribution details can be buried in accounting documents that require a visit or a formal request to the court clerk's office. Some information may also be sealed depending on how the estate was structured. The broader takeaway here is that Doris Day's estate distribution followed a fairly standard pattern for a well-drafted estate plan with charitable intentions and family provisions. The multimillion-dollar figure is real. The family inherited a share. The charitable share was larger and more publicized because it aligned with her lifelong advocacy. Neither outcome is surprising once you understand how these things are typically structured.